
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Earnings Beat At Toll Brothers (TOL) Has Changed Its Investment Story
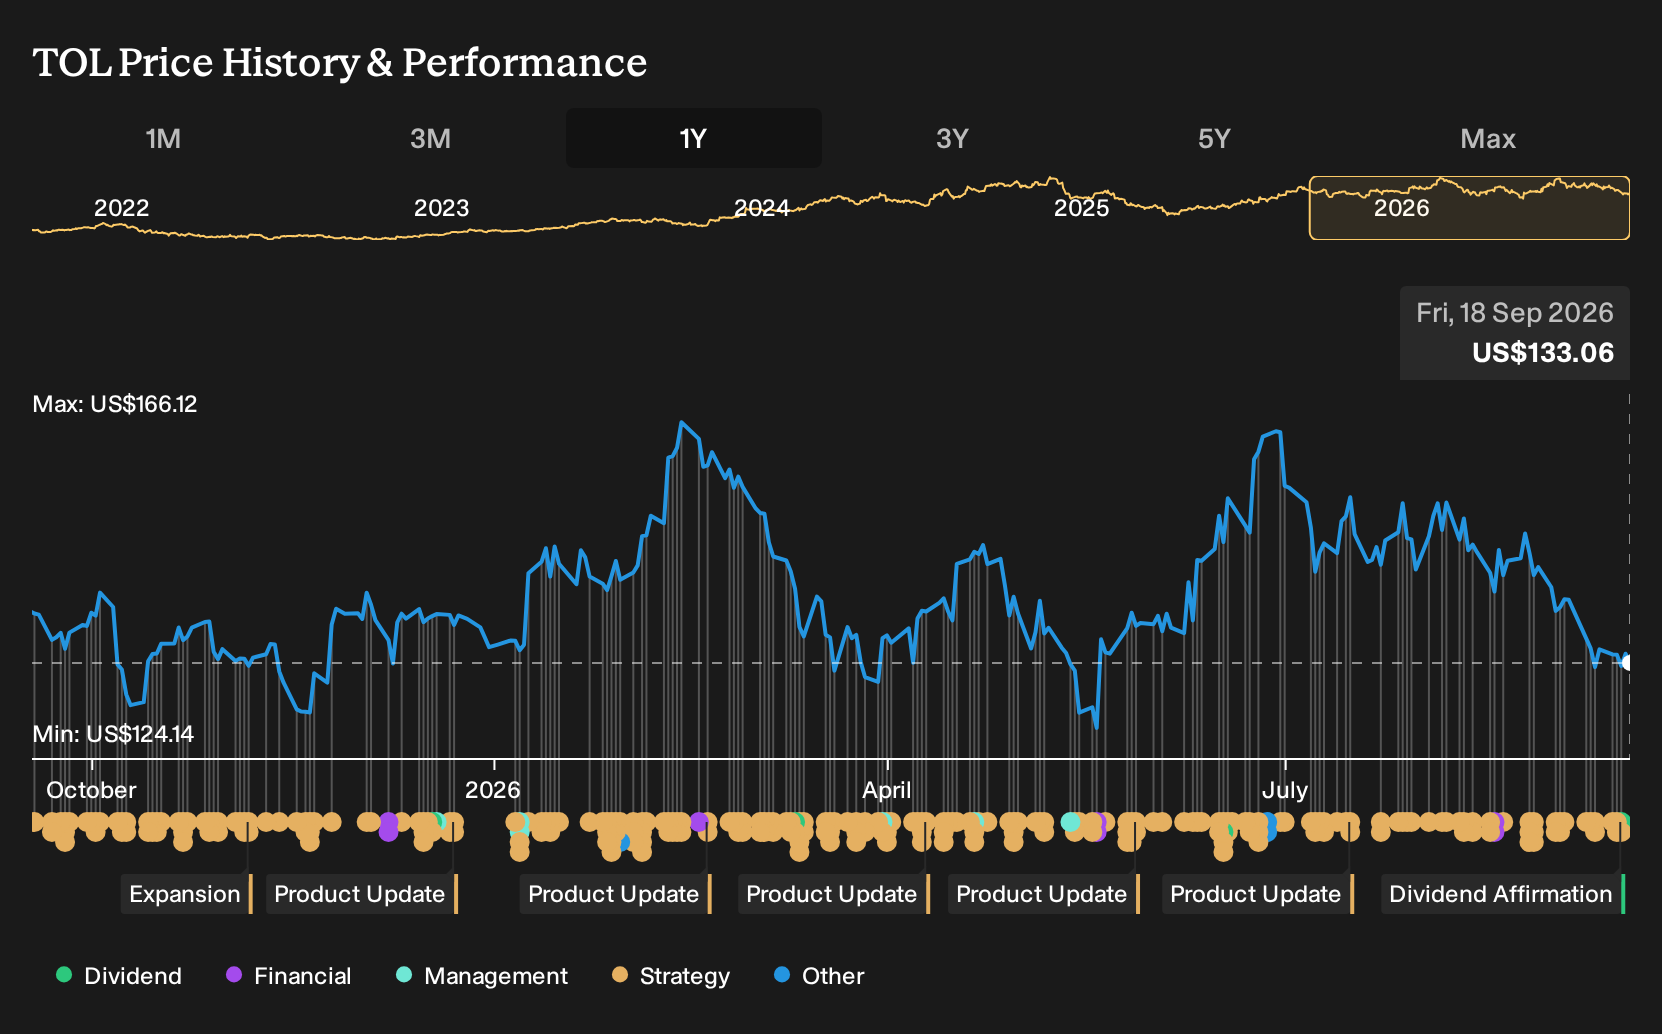
- Toll Brothers reported fiscal Q3 2026 earnings and revenue above estimates while continuing to roll out new luxury communities in Florida, California, North Carolina, and Texas and affirming a $0.26 quarterly dividend declared for payment on October 23, 2026.
- The combination of resilient demand from affluent buyers and ongoing openings of higher priced, amenity rich communities highlights how Toll Brothers is leaning into its luxury focus instead of pulling back on new projects.
- Next, the focus shifts to how Toll Brothers' earnings beat and continued luxury community expansion could reshape its existing investment narrative.
Toll Brothers Investment Narrative Recap
To own Toll Brothers, you need to believe its luxury focus and growing community count can offset pressure from incentives, spec inventory and higher funding costs. The near term hinge point is whether affluent demand stays firm enough for the current slate of openings in Florida, California, Texas and the Carolinas to convert into steady contracts and deliveries.
The biggest risk is that a softer high end buyer or sustained high mortgage rates force deeper discounts on spec homes, further pressuring margins that are already below last year. The recent earnings beat and ongoing dividend affirmations help confidence but do not materially change that risk reward balance yet.
Among the latest announcements, Summercrest by Toll Brothers in Estero looks most relevant to the current earnings story. It fits directly into the firm’s push to add luxury communities in supply constrained, higher income markets, with townhomes, amenities and personalization through the Design Studio that align with Toll Brothers typical buyer profile.
If Summercrest and similar launches in Babcock Ranch, Redondo Beach and the Austin and Charlotte areas see healthy absorption, that would support the key catalyst that analysts focus on: rising community count feeding into revenue and earnings. Weak traffic or heavier than expected incentives at these projects would instead highlight the margin and spec related risks already on investors’ minds.
Toll Brothers' current analyst narrative points to forecast revenues of about $13.2b and projected earnings of roughly $1.5b by 2029, based on an assumed 6.1% yearly revenue growth rate and an earnings increase of about $200m from current earnings of $1.3b.
Uncover why Toll Brothers' fair value indicates a 26% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle around Toll Brothers focuses on demographic headwinds. The most cautious analysts expected revenue of about $12.0b and earnings of roughly $1.4b by 2029. That is a more restrained story than the baseline. These views were set before the latest community launches, so future forecasts could shift.
Explore 5 other Toll Brothers fair value estimates, including one that suggests it could be worth just $137.74.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toll Brothers research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Toll Brothers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Toll Brothers' overall financial health at a glance.
Looking for more investment ideas beyond Toll Brothers?
Once you have a view on Toll Brothers, it can help to widen the lens and compare it with other stocks that share similar strengths or offer a very different risk profile. The Simply Wall St Screener is a quick way to surface candidates that fit the kind of portfolio you want to build next.
- If you want a mix of quality and value, consider starting with a curated set of companies that appear attractively priced on both fundamentals and balance sheet strength through the 33 high quality undervalued stocks.
- For income focused portfolios, you can zero in on businesses with higher yields and more resilient payout profiles by scanning the 6 dividend fortresses.
- When capital preservation matters most, it may be worth filtering for businesses with sturdier finances and lower risk profiles using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com