
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Canadian Growth Stocks With Revenue Growth Up To 20%
Canada is hunting for fresh capital as policymakers push to make the country one of the most tax competitive in the G7 and reduce reliance on the US. That kind of pitch can shine a light on homegrown businesses where insiders already have serious skin in the game and analysts see room for further growth. This article walks through three Canadian high growth, high insider ownership stocks from our screener.
The three stocks below are only a sample, while the full screen surfaced 45 more Canadian high growth, high insider ownership companies with similarly strong stories that are not covered here. To go deeper, head straight into the Fast Growing Stocks With High Insider Ownership screener to identify, filter, and analyze the highest conviction ideas that match your criteria.
Lightspeed Commerce (TSX:LSPD)
Lightspeed Commerce builds cloud-based tools that help retailers, restaurants, and golf operators run day to day operations and accept payments, which fits the screener’s focus on recurring software revenue backed by aligned insiders. The business generates roughly US$1.2b from software and programming and carries a market value near CA$1.7b.
For investors looking at fast growing, high insider ownership opportunities, Lightspeed Commerce offers a clear example of how recurring software and payments can turn day to day merchant activity into a compounding revenue engine.
"Accelerating adoption of digital payments and cloud-based platforms in retail and hospitality, which are core to Lightspeed's growth strategy, continues to boost subscription and transaction-based revenue, supporting an expanding total addressable market and steady revenue growth."
The real swing factor is whether one evolving cost pressure ultimately feeds through to margins faster than top line progress can offset it.
If that cost pressure is the real hinge, the full narrative for Lightspeed Commerce explains how Lightspeed Commerce balances margin risk and insider alignment, and identifies where growth ambitions may still be underappreciated.
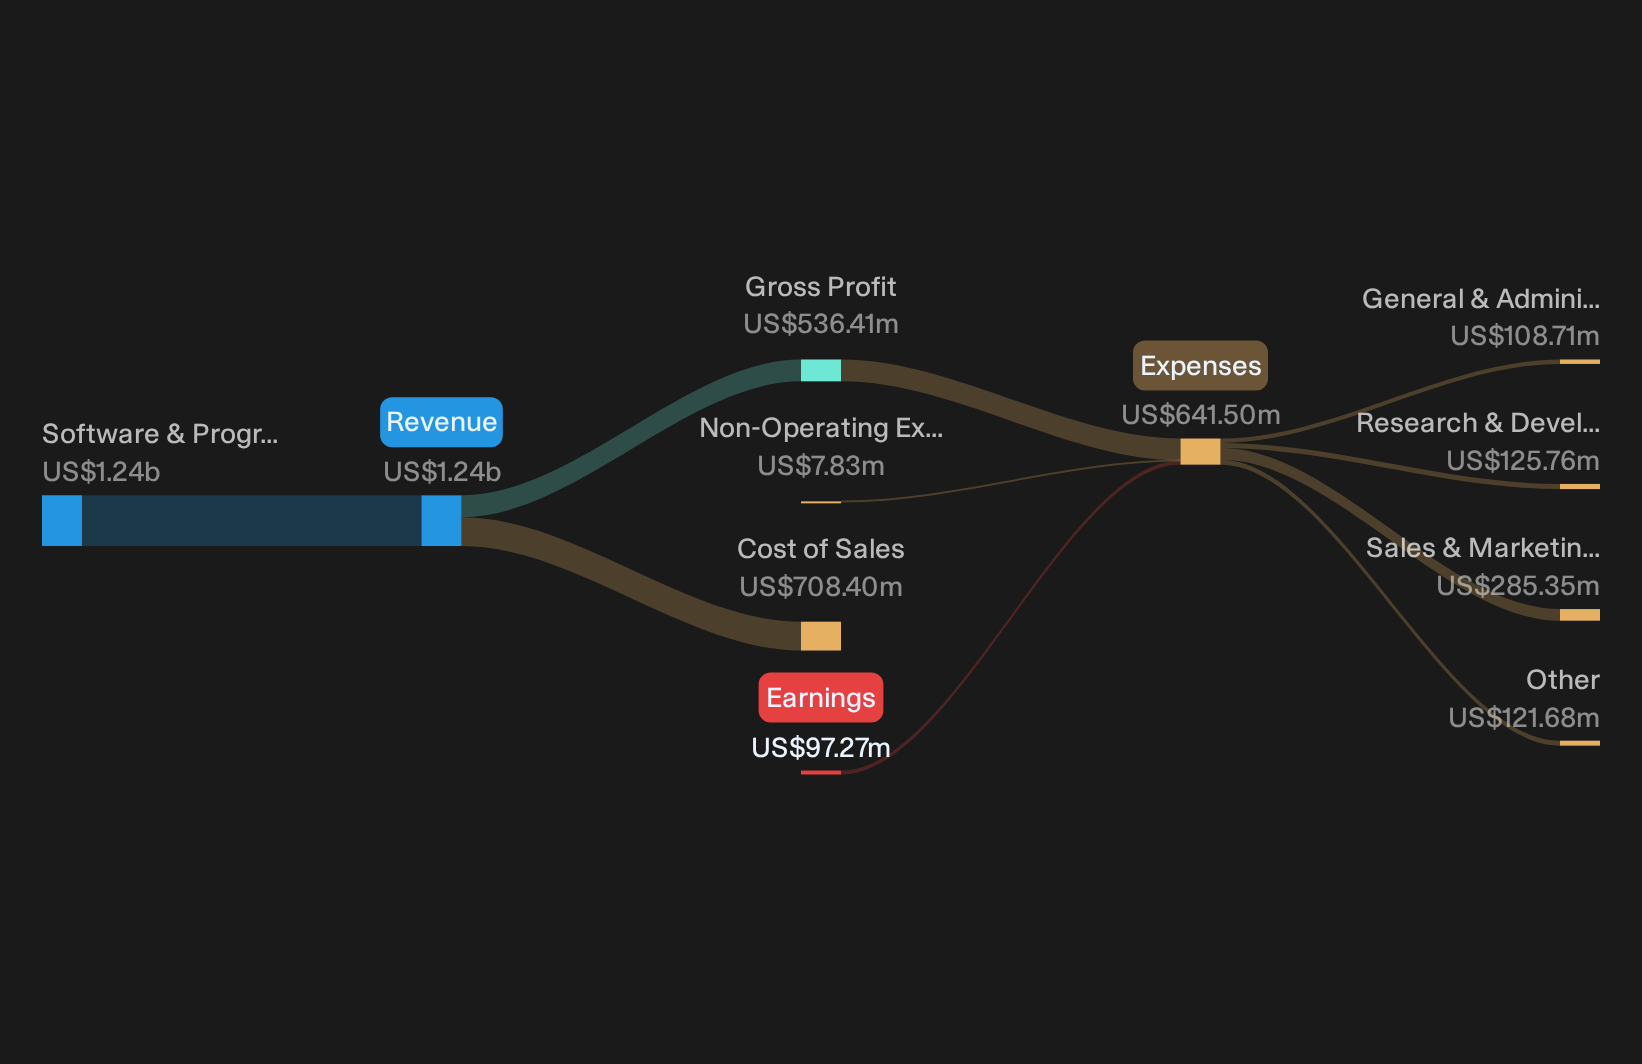
Colliers International Group (TSX:CIGI)
Colliers International Group runs a broad commercial real estate and engineering services platform, but its capital markets and investment management arm is the clearest fit with the screener theme, using property sales, mortgage banking and long-dated funds to grow fee-based assets under management.
Colliers generates about $3.5b from commercial real estate services, $1.9b from engineering work, and $562 million from investment management activities, and the stock carries a market value near CA$6.4b.
Colliers International Group provides exposure to institutional real estate capital, with a sizeable services platform feeding into fee-based assets under management and recurring advisory income that align directly with the screener’s growth plus insider alignment focus.
"The growing interest from institutional and private wealth channels in alternative asset classes such as data centers, student housing, infrastructure, and credit solutions is driving segment diversification and AUM growth in the investment management business, supporting future recurring fee revenue and higher net margins."
The key issue is how pressure on profitability interacts with that expanding fee pool if capital markets activity cools again just as margins are rebuilding.
If that tension between fee growth and margins is the real story, the full narrative for Colliers International Group explains how Colliers International Group could turn that pressure into accelerating operating leverage.
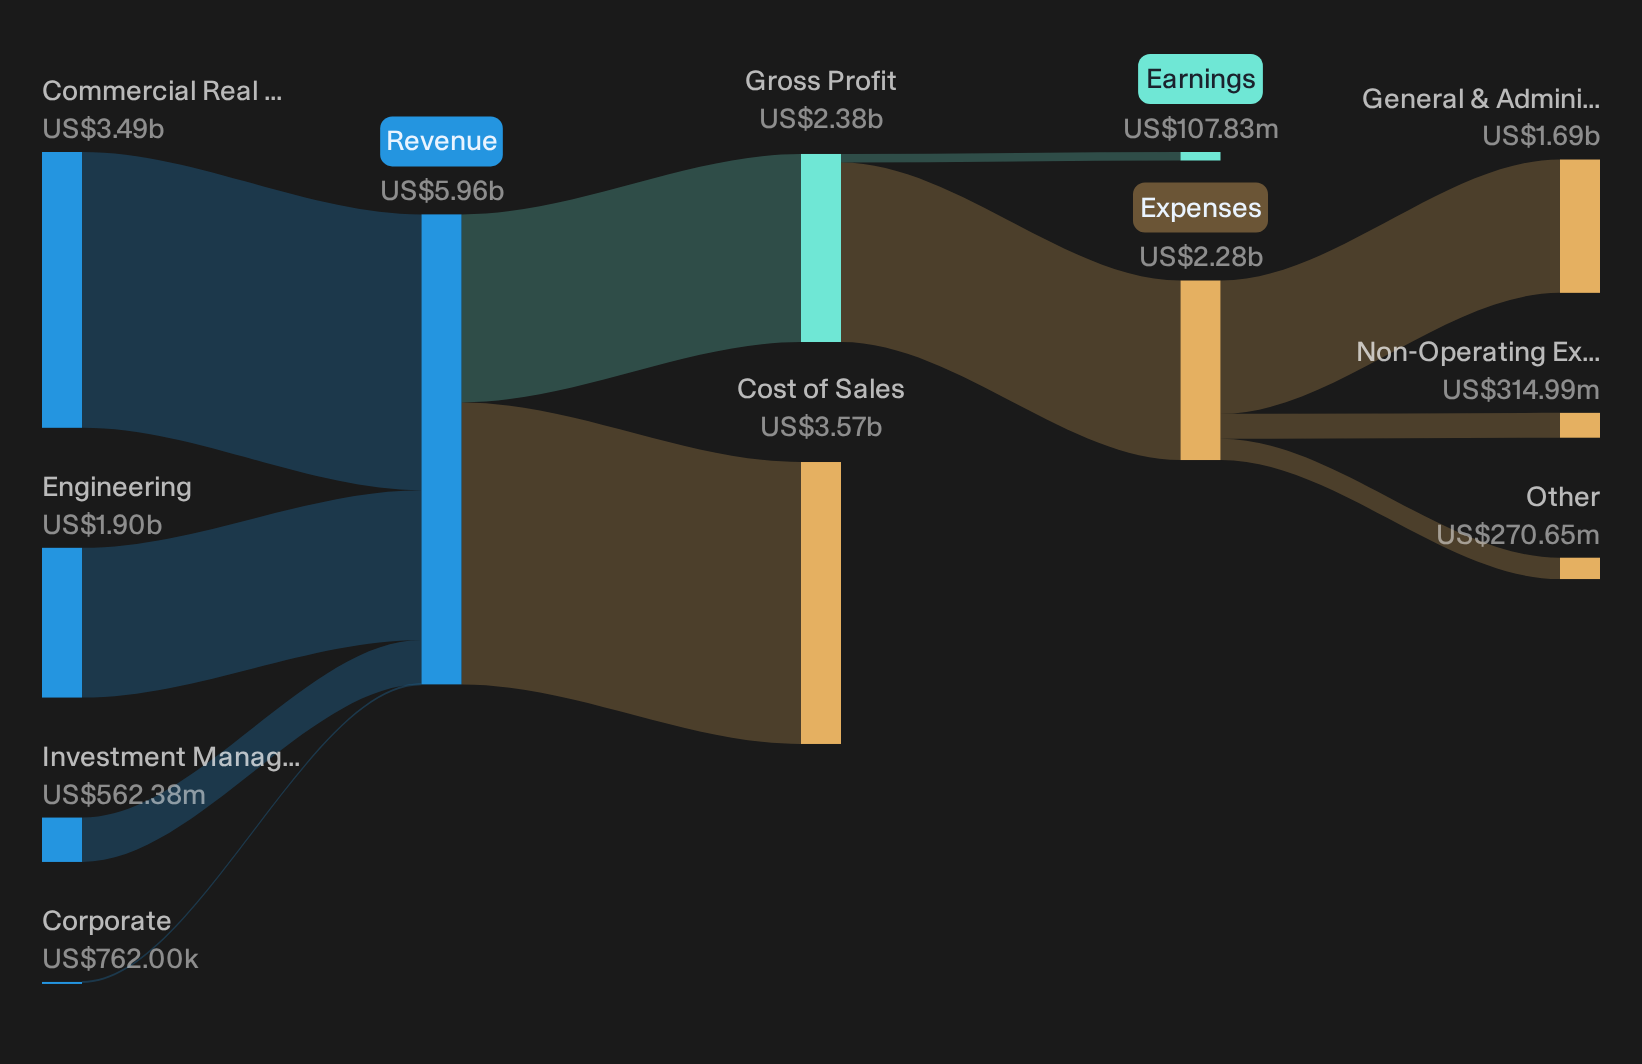
Allied Gold (TSX:AAUC)
Allied Gold is a Toronto based miner focused on gold and silver across Africa, with its Sadiola project in Mali anchoring the high growth, high insider ownership theme as the business generates about $733 million from Sadiola, $418 million from Bonikro, $343 million from Agbaou, and carries a roughly CA$4.2b market value.
Allied Gold fits this screener because Sadiola gives the group a clear production growth runway that management and insiders are heavily tied to, and Kurmuk offers a second leg of potential expansion that could reshape future earnings power.
"The planned Zijin investment of $295m to $417m is viewed by bullish analysts as a key support for Allied Gold's balance sheet, important for completing and ramping up Kurmuk without relying as heavily on other funding sources."
What really matters next is how one unseen operational swing factor filters through to future unit costs and cash generation.
That operational swing factor is exactly what the full narrative for Allied Gold unpacks, showing how Allied Gold’s next phase could turn cost volatility into accelerating long term cash power.

Seeking Alternatives Before The Crowd Moves
Fresh breakouts do not wait. Momentum shifts, stories go from under the radar for now to fully priced, and laggards get caught dropping while it matters. Consider acting early.
- Target dependable income while rates move by scanning 1 dividend fortresses that aim to keep yields flying even when prices wobble.
- Look for high quality mispricing with the 4 high quality undervalued stocks before renewed interest changes pricing for these fundamentals driven stories.
- Prepare for a potential commodity upcycle by reviewing the 36 elite gold producer stocks before institutional money crowds the trade.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com