
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Boeing (BA) Is Back In The Spotlight, So What Is The Market Missing?
Boeing (BA) is back in the cargo spotlight after AerSale agreed to lease a Boeing 757-200PCF freighter to Jupiter Jet, a Kazakhstan based carrier that is expanding regional and international freight routes.
For investors tracking Boeing, that new 757-200PCF lease lands against a softer backdrop, with the share price at about $198.20, a 30 day share price return down 10.8%, and a 1 year total shareholder return down 8.1%, which points to fading momentum despite ongoing cargo, defense and regulatory developments.
Spot under-pressure plays like Boeing and then compare them with other stocks that screen well on cash flows and balance sheets using our curated 33 high quality undervalued stocks.Boeing keeps signing cargo deals and reporting revenue of about US$94b, yet the share price has slipped over the past year. Is this a strong business temporarily out of favor, or already fairly priced?
Most Popular Narrative: 24% Overvalued
The current Boeing share price of about $198 sits above the fair value estimate of $160.01 in the most followed narrative, which frames the stock as already pricing in much of the recovery story.
The operating recovery is real but incomplete. Commercial Airplanes narrowed its operating margin from negative 5.1% to negative 2.7% on 171 deliveries against 150. The 737 is transitioning to 47 per month from 38 a year ago, with a fourth Everett line activated in July, and management targets 52 next year.
See why 4 investors see Boeing as 24% overvalued.
According to rcb9, that framework rests on a few key levers. The narrative assumes revenue growth of 8%, a long run net margin of 8%, and a future P/E of 23x, all discounted at 10%. It also bakes in ongoing share dilution to roughly 939 million shares by 2031, which pulls the per share fair value down to about $160 instead of roughly $190 on a flat share count.
That same narrative outlines what would need to go right for a higher anchor price around $230.63. In that scenario, the author suggests the market would effectively be paying for about 9.3% annual revenue growth, a 10% net margin that matches Boeing's best year on record, and a 25x exit multiple, all with less balance sheet pressure than exists today.
Critically, the write up also lists several risks that could break the thesis. Large new program charges above $1b in a single quarter through 2027, weaker than guided free cash flow in 2026, slippage on key certifications like the MAX 10 or 777X, or slower debt reduction than targeted would all push actual outcomes away from the narrative path.
Result: Fair Value of $160.01 (OVERVALUED)
Still, the narrative can break quickly if Boeing records another large program charge or misses its 2026 free cash flow floor after a weak first half.
Find out about the key risks to this Boeing narrative.
Another View: Boeing Through The Cash Flow Lens
While the rcb9 narrative pegs Boeing at a fair value of $160.01 and therefore overvalued at about $198, the SWS DCF model lands in a very different place. On that framework, Boeing at $198.20 trades well below an estimated future cash flow value of $391.35, which frames the stock as undervalued. Which story feels more credible to you, earnings-based fair value or cash flow potential?
Look into how the SWS DCF model arrives at its fair value.
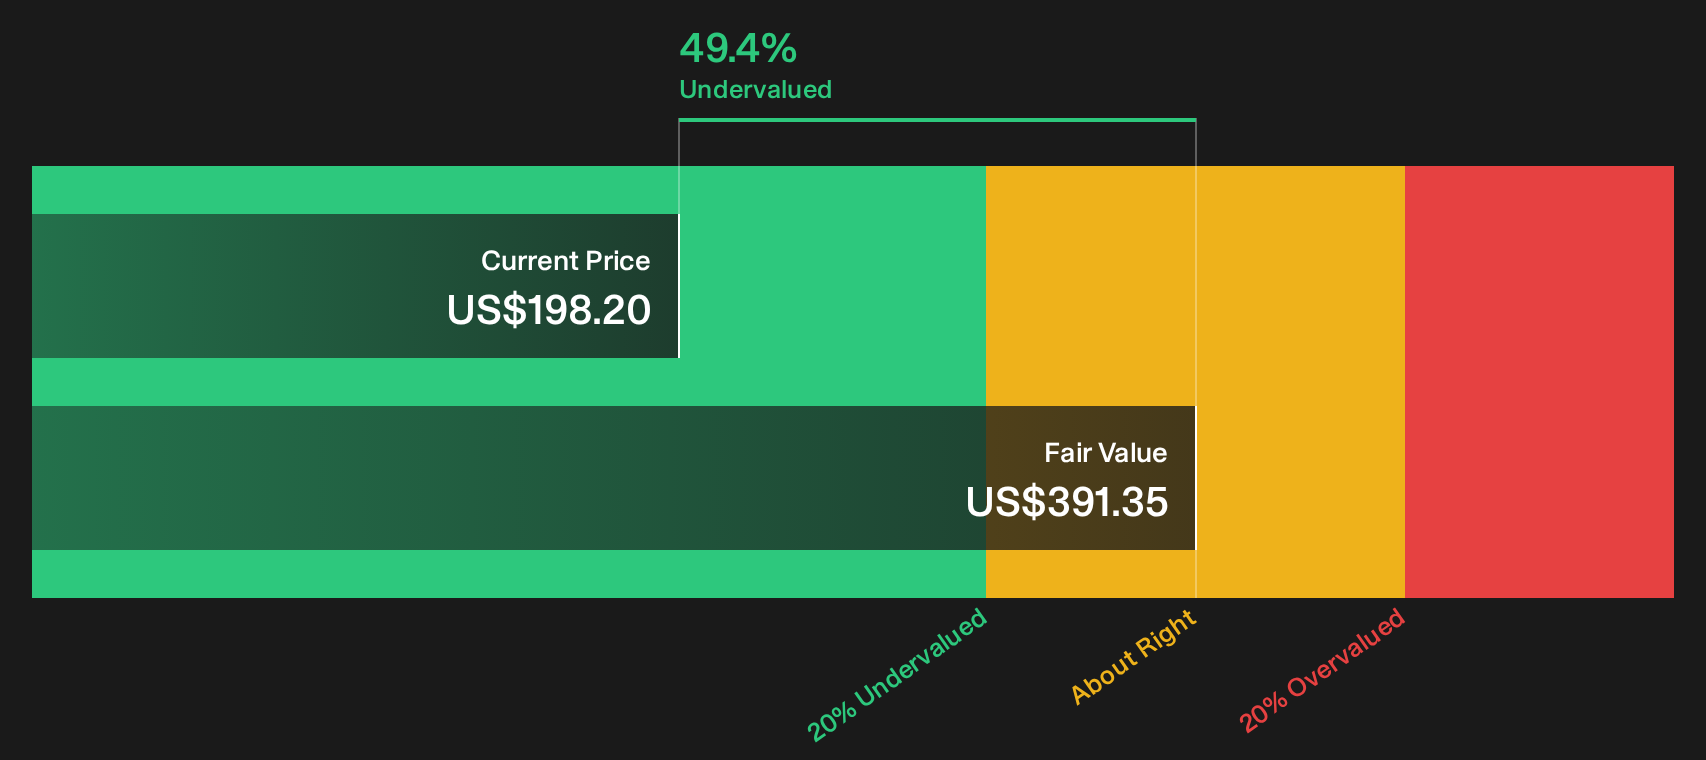
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Boeing for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed sentiment around Boeing feels unresolved, use that tension as your prompt to act quickly and test the thesis against the 4 key rewards and 2 important warning signs.
Looking for more Boeing investment ideas beyond this story?
Do not stop your research with Boeing alone. Use fresh screeners to surface other opportunities that fit your style before the market prices them more fully.
- Target higher yield potential by focusing on companies that look more dependable on payouts using our 6 dividend fortresses.
- Channel your caution into companies with steadier financial footing by scanning the 30 resilient stocks with low risk scores.
- Hunt for under followed opportunities with strong fundamentals by reviewing the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com