
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Southern (SO) Stock May Be Below Fair Value After Georgia Battery News
Southern has delivered solid long term gains for shareholders, yet the recent pullback in the stock price puts fresh focus on whether its current valuation is still supported by its earnings power. With the share price now around US$85.52, investors are asking how much of the business story is already reflected in that figure.
- Southern has returned 62.6% over the past 5 years, which raises the question of how much future earnings strength the market is already pricing in.
- New projects at Georgia Power and PowerSecure, including large scale solar and battery storage along with data center resiliency work, can influence expectations for future profit growth and the timing of cash flows that support the earnings base.
- There is a second opinion on Southern worth weighing. See what analysts think Southern's shares could be worth.
The issue now is whether Southern's current share price is justified by its earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings question across other power and infrastructure stocks, a good next step is to scan the 38 power grid technology and infrastructure stocks.
Is Southern Still Cheap on Earnings?
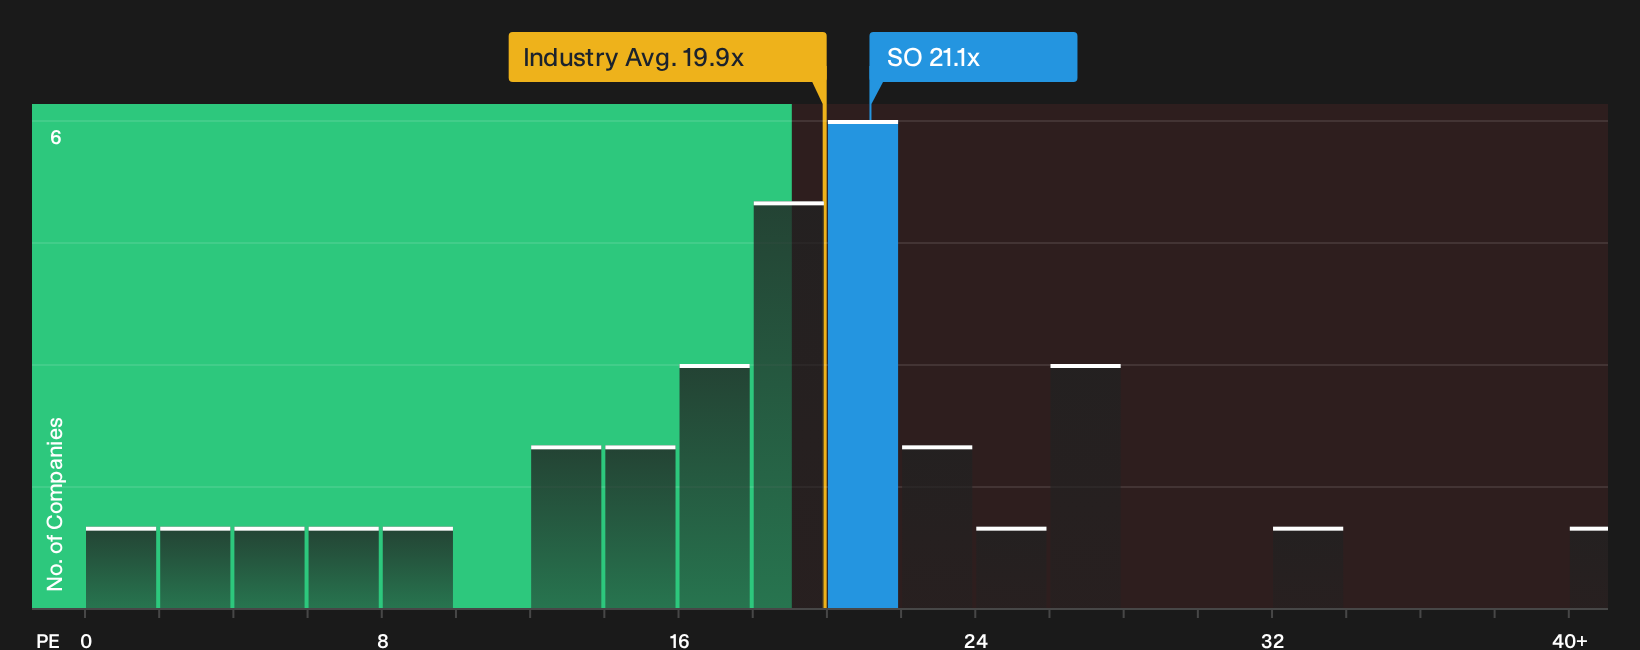
The P/E ratio fits Southern because earnings are a key anchor for regulated utilities and their long asset lives. On this measure, Southern trades on a P/E of 21.1x, which is slightly above the Electric Utilities sector average of 19.9x and also a touch higher than the 20.7x peer group level. That indicates the market is willing to pay a modest premium for each dollar of the group’s earnings.
Because the Fair Ratio blends factors like growth profile, profitability, size and risk, it suggests Southern’s current P/E sits below what that tailored yardstick would imply. This screens as undervalued on this specific model. Recent moves such as Georgia Power’s large battery storage and solar projects show the business committing capital to assets that can shape earnings over a long period. Yet the multiple still prices the stock at a discount to what the Fair Ratio framework would indicate. Explore the numbers behind Southern's P/E valuation.
The Southern Narrative: What Would Justify Today's Price?
Narratives pick up where Southern's valuation puzzle leaves off by spelling out which future paths for growth, margins and earnings would need to hold for the stock to be worth materially more or less than today. They sit on Simply Wall St's Community page. Each scenario lays out the assumptions behind its estimated value in plain terms so you can later compare those expectations with the company’s reported results as they come through.
One of the top community narratives on Southern: 16% undervalued
"The successful operation and integration of the new Vogtle nuclear units, coupled with ongoing grid enhancements and the potential for further nuclear and renewable capacity..."
Discover why this Narrative puts Southern at 16% undervalued.
Southern's price is only one piece of the puzzle
Valuation frames what you pay today, but the projections that analysts put on Southern's earnings and cash flows over the next few years give you another lens on what that price might be weighing. Explore where analysts expect Southern to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com