
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Driven Growth Might Change The Case For Investing In Frontdoor (FTDR)
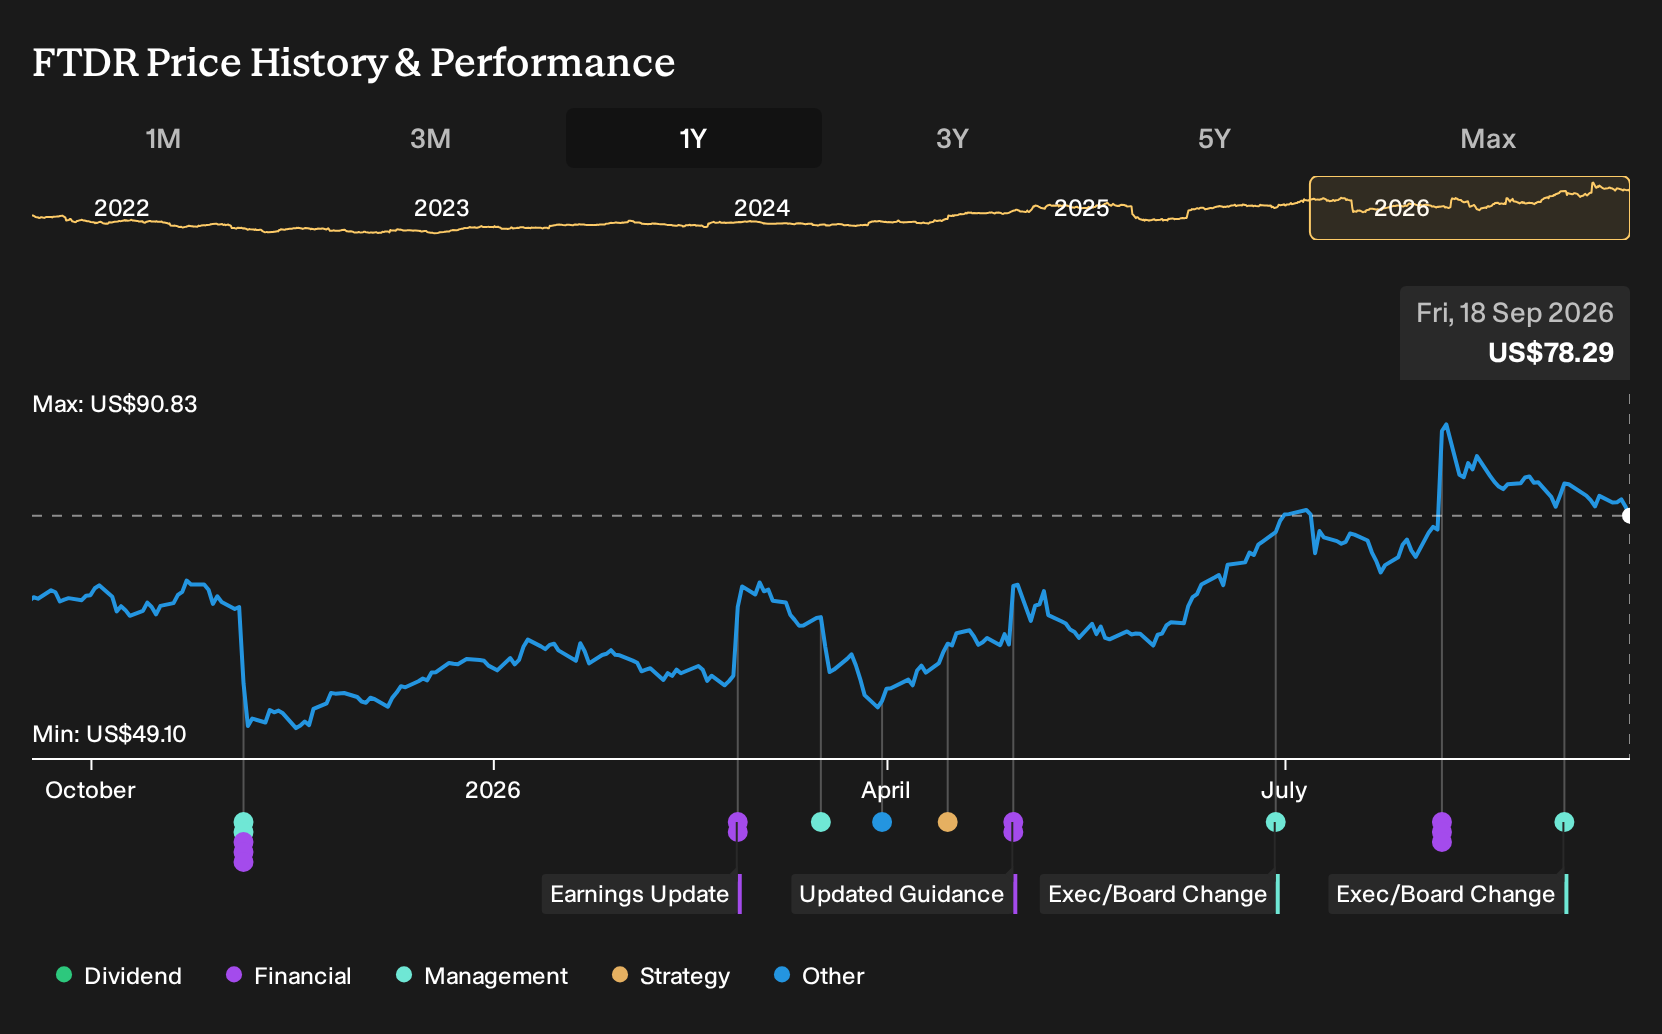
- Frontdoor recently reported progress in direct-to-consumer acquisition, using AI-driven search, content and sales tools, alongside tighter marketing efficiency and deeper local engagement with real estate agents to support home warranty attachment.
- The more tailored member experience, supported by technology-enabled service, autopay adoption and targeted retention programs, points to a business model increasingly focused on lifetime value rather than just upfront sign-ups.
- The focus now turns to how Frontdoor's AI-supported customer acquisition and retention efforts could influence the broader investment narrative for the business.
Scan a curated set of home-services and housing-adjacent companies applying AI to customer acquisition and retention by reviewing the 16 high quality undiscovered gems that share some of Frontdoor's playbook.
Frontdoor Investment Narrative Recap
For an investor to stay interested in Frontdoor, there needs to be confidence that AI supported direct to consumer efforts and real estate channel partnerships can offset a soft housing backdrop and a projected 1 to 3% decline in home warranty member count. The recent update on marketing efficiency and higher conversion helps that case but does not fully resolve it.
In the short term, the key swing factor is whether AI driven acquisition can scale without relying heavily on discounting that pressures price realization and margins. The biggest immediate risk remains rising customer acquisition costs and higher SG&A, especially if housing transactions stay sluggish and discount led offers become harder to pull back.
The most relevant development here is Frontdoor's commentary that AI powered search, content and sales tools are lifting direct to consumer conversion while tighter marketing execution is improving efficiency. That directly targets the concern that growth is coming at the expense of profitability through heavy discounting.
If AI led targeting and better onboarding can support renewals, autopay adoption and the HVAC upgrade program, the result could be more stable recurring revenue and less dependence on the next promotion cycle. The flip side is execution risk. If integration of the 2 10 acquisition or technology rollouts stall, the expected member quality and margin benefits could prove harder to realize.
Frontdoor's current analyst narrative points to revenue reaching $2.6b and earnings of $405.2m by 2029. This projection is based on a 6.0% yearly revenue growth assumption and an earnings increase of about $131m from current earnings of $274.0m.
Uncover how Frontdoor's fair value indicates a 25% potential upside to its current price before increased attention on Frontdoor tightens that gap.
Exploring Other Perspectives
One alternate view on Frontdoor leans hard into AI as a catalyst. The most optimistic analysts were already modeling about 7.8% annual revenue growth and roughly $409.4 million of earnings by 2029, compared with $2.7 billion of projected sales. That was before this latest AI focused update, so expectations could easily shift again.
Explore 3 other Frontdoor fair value estimates, including one that suggests as much as 116% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider forming your own view.
- A great starting point for your Frontdoor research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Frontdoor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Frontdoor's overall financial health at a glance.
Looking for more Frontdoor style investment ideas?
If the Frontdoor story has you thinking about where else AI, recurring revenue and disciplined customer acquisition might matter, the Simply Wall St Screener can help you broaden your watchlist without shooting in the dark.
- For investors hunting for quality at a reasonable entry point, scan a curated 33 high quality undervalued stocks that combine fundamentals with pricing that may still leave room for upside.
- If resilience and balance sheet strength are your priority, focus on a list of solid balance sheet and fundamentals (23 results) to see which businesses carry less financial strain.
- For those willing to look off the beaten path, review a 16 high quality undiscovered gems that could offer differentiated exposure beyond widely followed tickers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com