
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did AI Identity Push Just Shift Okta's (OKTA) Investment Narrative?
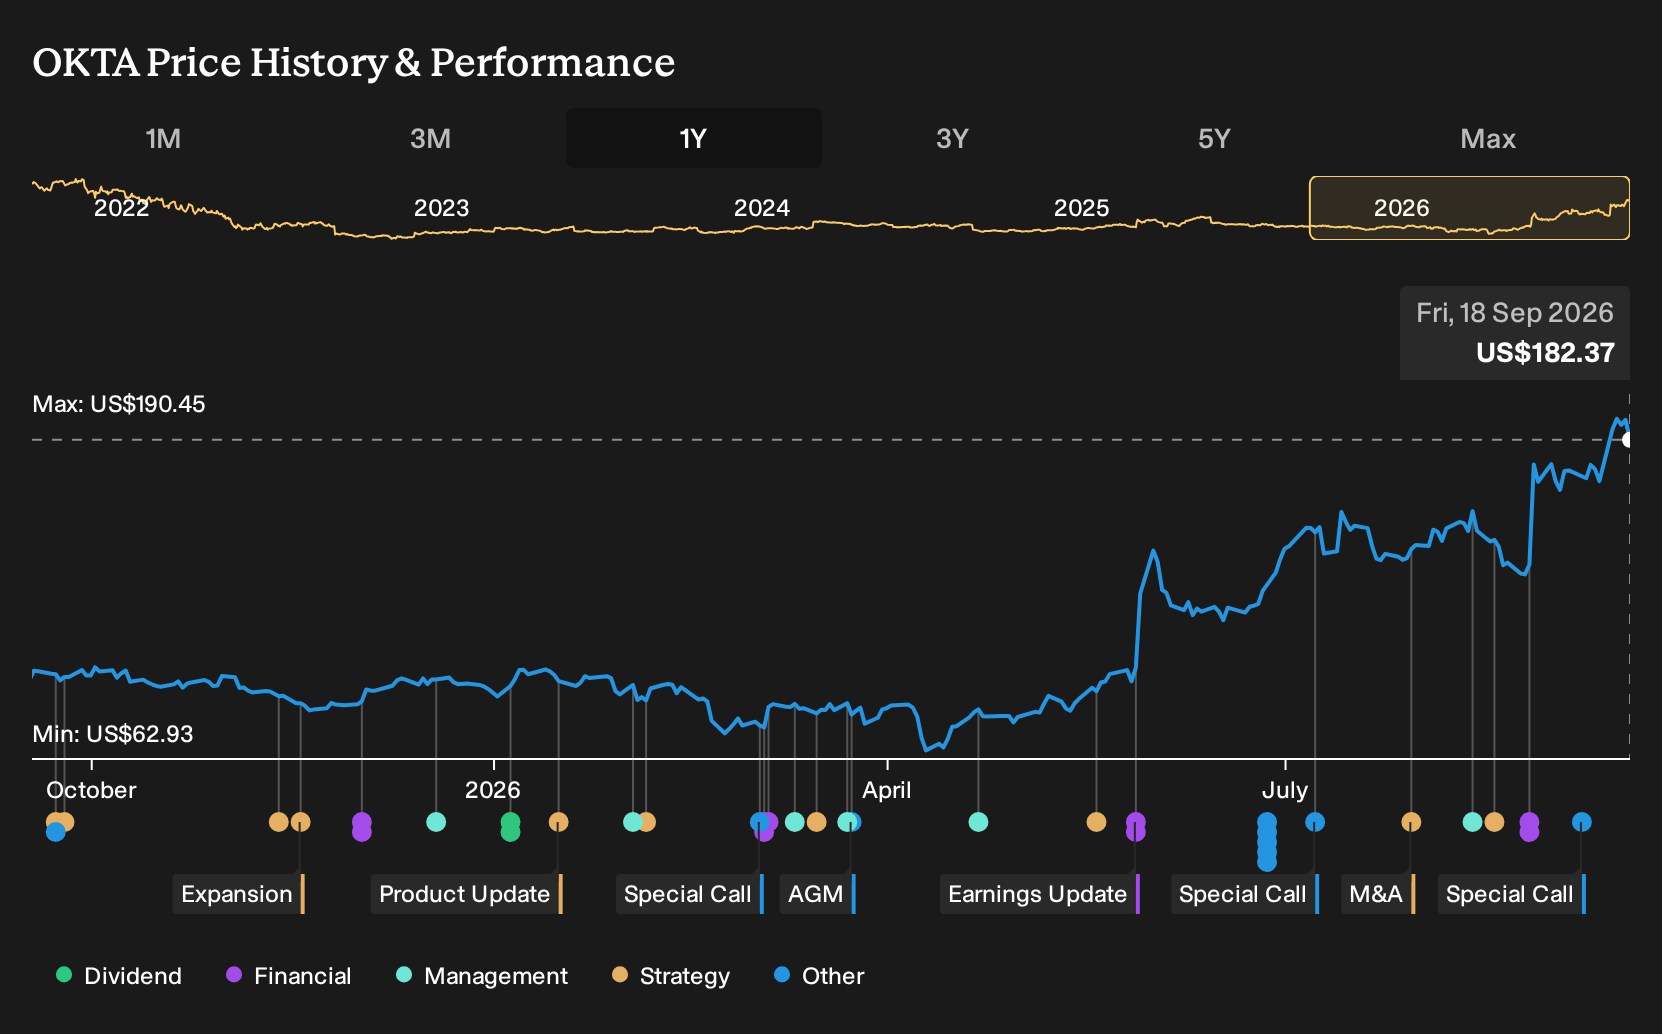
- Okta added Helen Riley, CFO and COO at X (The Moonshot Factory) and long-time Alphabet finance executive, to its board on 18 September 2026, while Emilie Choi stepped down on 14 September 2026.
- Riley’s track record in global finance, AI-focused R&D and board service at Eventbrite and Marqeta provides Okta with additional oversight on scaling identity platforms and capital allocation.
- This development may influence how investors view Okta’s strategy, particularly in relation to Riley’s board appointment and the CEO’s focus on AI driven identity.
Scan how Okta’s AI driven identity story compares with other potential breakout plays in security and automation by reviewing the hand picked 89 AI infrastructure stocks.
Okta Investment Narrative Recap
To own Okta, you need to believe identity security can support a broad platform tied to cloud adoption, AI agents and stricter security rules. The short term focus remains on execution around its suite, from workforce identity to customer access and AI related products, while keeping earnings growth and profitability moving in the right direction.
The biggest near term swing factor is how well Okta defends share as larger security platforms push deeper into identity. Integration missteps or slower new customer wins would quickly matter more than this board change. Helen Riley’s appointment looks helpful for oversight but not a material catalyst on its own.
The most connected recent development is CEO Todd McKinnon’s CNBC comments about AI agents as a new identity type and Okta’s push into secure cloud access and adaptive multi factor authentication. That public focus puts Okta’s AI offerings, like Okta for AI Agents and related governance tools, at the center of the execution story investors are watching.
What you are really tracking is whether these AI driven identity products deepen wallet share with large enterprises and public sector buyers or whether platform competitors crowd them out. If customers lean into Okta’s broader suite, the potential outcome is stronger cross sell and stickier contracts, while any stumble on integration, security or product quality would quickly sharpen the existing competitive risks.
Okta's current analyst narrative points to US$3.9b in revenue and US$536.4m in earnings by 2029, based on a projected 9.6% yearly lift in revenue and an earnings increase of about US$289.4m from US$247.0m today.
Uncover why Okta's fair value indicates a 33% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate view puts Okta’s AI focused product set, not competition, at the center of the story. The most optimistic analysts were penciling in about US$4.4b of revenue and US$927.6m of earnings by 2029 before this board news. You should expect those forecasts could shift in either direction as Helen Riley’s influence becomes clearer.
Explore 3 other Okta fair value estimates, including one that suggests it could be worth as much as $176.46.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Okta research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Okta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Okta's overall financial health at a glance.
Looking For More Ideas Beyond Okta?
If you want to put Okta in context, it helps to scan a wider field of opportunities. Use the Simply Wall St Screener to line up other companies against the same quality, value and risk filters and see where your capital might work hardest.
- For investors hunting for mispriced quality, review a curated 33 high quality undervalued stocks that combine strong fundamentals with more modest expectations baked into their share prices.
- If resilience matters most to you, filter for businesses with sturdier finances using the list of solid balance sheet and fundamentals (23 results) and compare their profiles with what you see at Okta.
- When income is a priority, scan a group of higher yielding payers through the 6 dividend fortresses and judge whether their cash returns fit better with your portfolio goals than Okta does.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com