
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Hirata India Partnership Require Action From ATS (TSX:ATS) Investors?
- Japanese semiconductor supplier Hirata Corp. has already entered India through a partnership with ATS India, making advanced backend automation and packaging equipment locally available for chip manufacturing customers.
- This tie-up gives ATS a foothold in India’s early semiconductor build out, linking its automation capabilities to rising electronic manufacturing complexity and demand for reliable backend tooling.
- We will now assess how this Hirata partnership in Indian semiconductor automation could reshape ATS's investment narrative and long-term positioning.
ATS Investment Narrative Recap
To own ATS, you need to be comfortable with an automation specialist that leans heavily on complex projects, a growing services layer and acquisitions, while carrying meaningful debt and uneven near term order trends. The Hirata partnership in India plugs ATS equipment into an emerging semiconductor ecosystem, but it does not change the main near term swing factor, which is order momentum across core segments.
The bigger immediate risk still sits around elevated leverage, weaker transportation bookings and reliance on large, sometimes lumpy projects in areas like GLP 1 auto injectors. The India move slightly broadens optionality in electronics and semiconductor exposure, yet on its own it does not materially alter the balance between growth opportunities and balance sheet pressure.
With no other fresh announcements tied directly to semiconductors, the Hirata agreement itself is the key event to focus on here. It links ATS to backend automation demand in India, which fits the broader thesis that customers facing labor constraints and complex manufacturing requirements turn to higher value automation systems and lifecycle services.
For catalysts, investors are likely to watch whether this relationship helps ATS win more recurring work around servicing, upgrades and digital tools for installed equipment, not just one off projects. On the risk side, the same concerns still apply. Order volatility, acquisition dependence and interest coverage all need close monitoring to see if new opportunities like India translate into more stable earnings over time.
ATS' current analyst narrative points to revenues of CA$3.1b and earnings of CA$227.0m by 2029. That path assumes 1.8% yearly revenue growth and an earnings increase of about CA$179.8m from CA$47.2m today.
Discover why ATS' fair value indicates a 39% potential upside to its current price, which could narrow quickly as sentiment catches up.
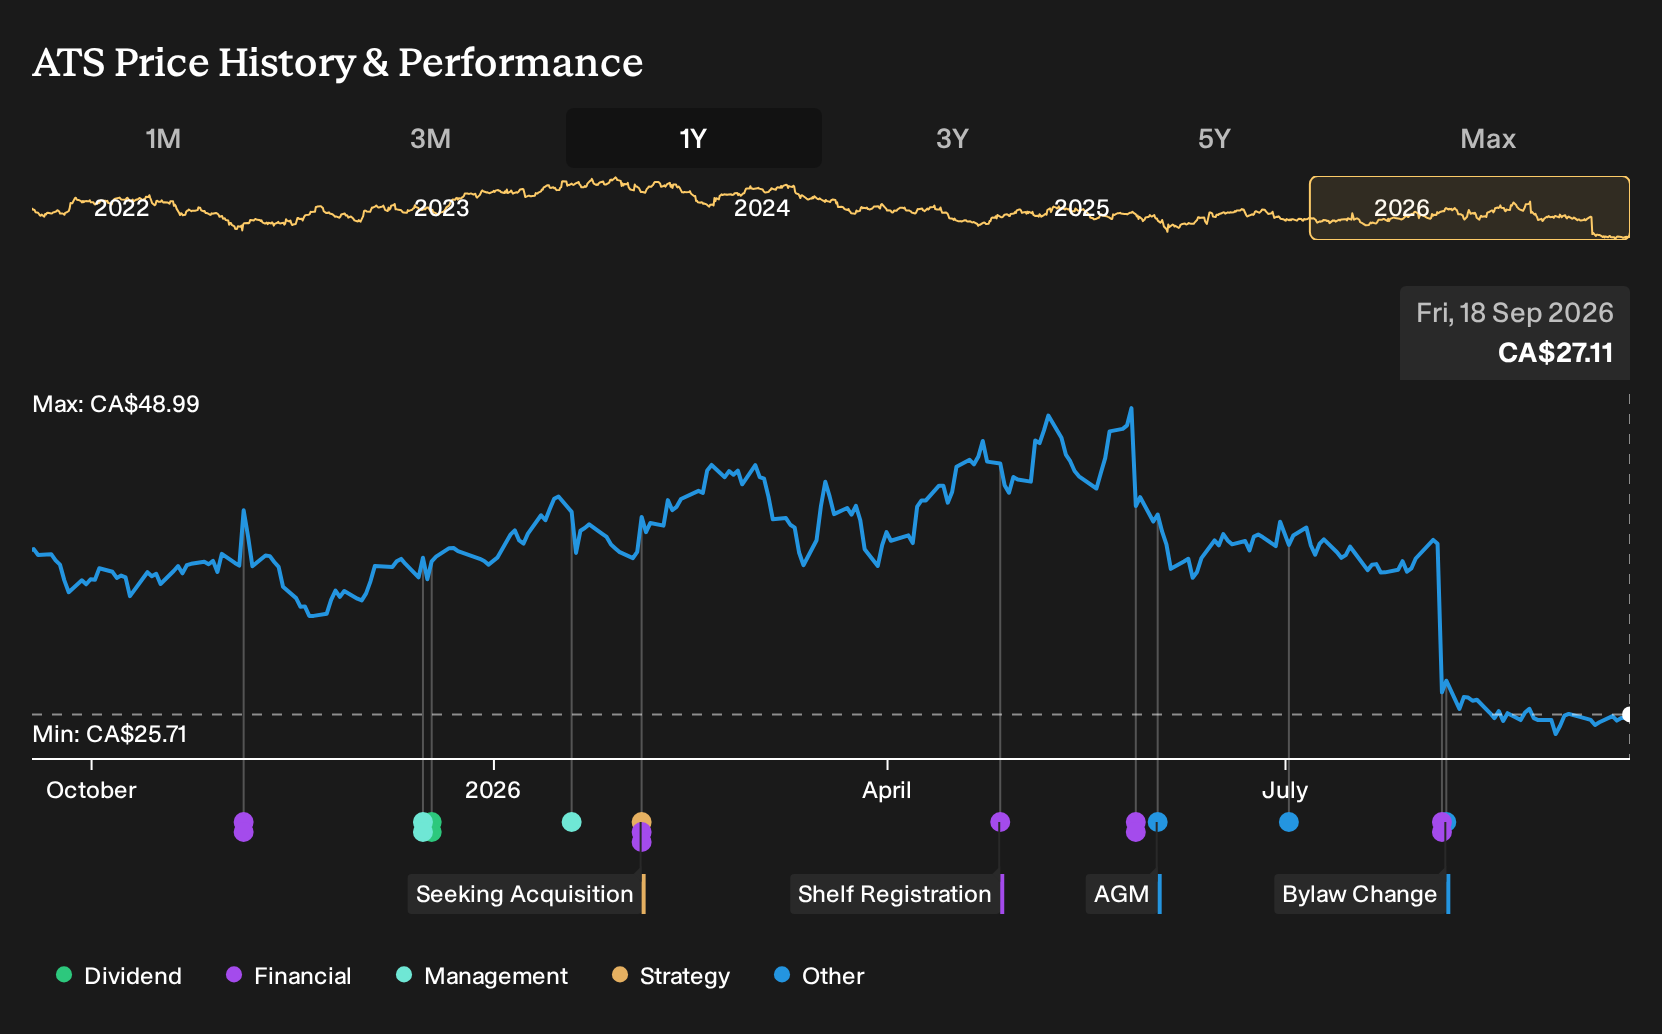
Exploring Other Perspectives
One alternative view on ATS leans hard into the potential of higher margin services. Bullish analysts were already modelling revenue of about CA$3.2b and earnings of CA$219.0m by 2029, before this India semiconductor news. You might see this deal and wonder whether those optimistic service heavy assumptions now look more achievable or too stretched.
Explore 2 other ATS fair value estimates, including one that suggests up to 46% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ATS research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ATS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATS' overall financial health at a glance.
Looking For More Ideas Beyond ATS?
If the ATS story has you thinking about where automation, cash flows and balance sheets intersect, it can help to widen the net and look at other businesses with different risk and return profiles using the Simply Wall St Screener.
- For investors who want quality at a discount, scan a curated set of 4 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them yet.
- If capital preservation and steadier profiles matter most to you, filter for 8 resilient stocks with low risk scores that score well on resilience and financial stability.
- When you want to move beyond the usual tickers, sort through 9 high quality undiscovered gems that combine solid financials with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com