
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elite Australian Undervalued Stocks To Own In September 2026
The Bank of Japan just lifted interest rates to a 31 year high, reminding investors that borrowing costs can reset quickly and reprice assets almost overnight. When money becomes more expensive, reliable cash generation and sensible entry prices matter more. This piece looks at Australian stocks where projected cash flows point to higher worth than current quotes, and highlights three candidates from this undervaluation list.
The three examples below are only a starting sample from this idea, and the full screen surfaced 1 more company with equally cash-rich potential that does not feature in the article. To assess that wider set, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, compare, and analyze the highest conviction opportunities grounded in discounted cash flow work.
Regis Resources (ASX:RRL)
Overview: Regis Resources is an Australian gold producer, with the Duketon project anchoring the operating cash flows underpinning its DCF valuation.
Operations: The business generates A$1.45b of revenue from Duketon and A$897 million from Tropicana, all sourced within Australia.
Market Cap: A$5.9b
Regis Resources matters for this cash-flow focused screen because its producing gold assets, especially Duketon, already generate measurable cash that feeds directly into discounted cash flow work rather than relying purely on early-stage project potential.
"Regulatory and environmental barriers are stifling new mine supply globally, increasing the strategic value of established, expandable operations like those of Regis."
What really moves the needle for Regis Resources is how one unresolved cost and investment swing shapes future margins against that cash-flow backdrop.
That unresolved swing is exactly what the full narrative for Regis Resources unpacks, showing where margins could accelerate, where risks bite and where the market might be mispricing Regis Resources.
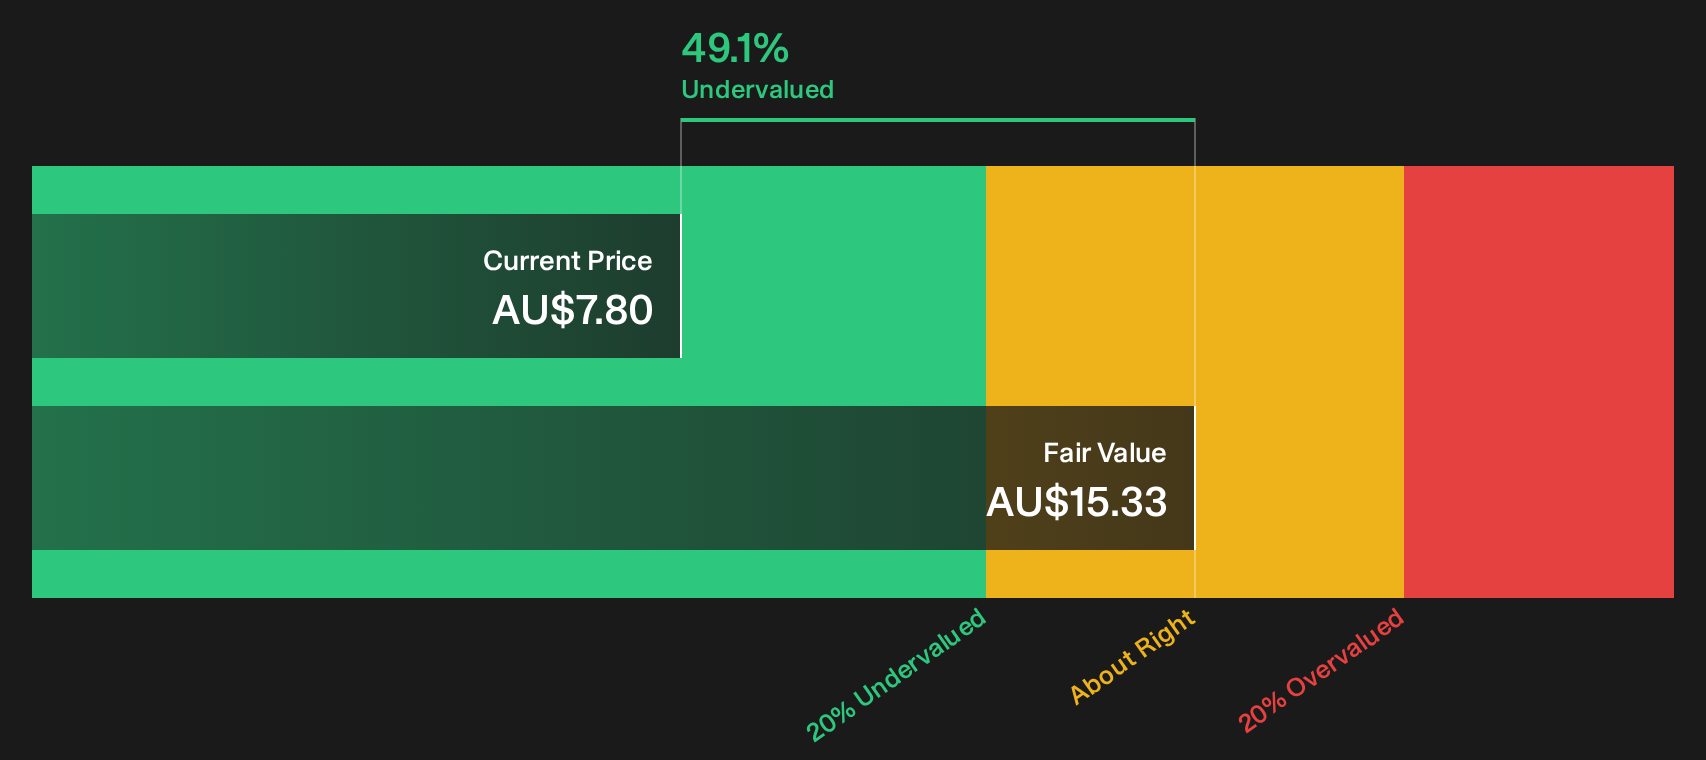
NobleOak Life (ASX:NOL)
Overview: NobleOak Life is an Australian life insurer providing recurring premium products like life, income protection and TPD cover directly and through partners.
Operations: NobleOak Life generates about A$399 million from Strategic Partnerships, A$106 million from Direct, and A$15 million from Genus, almost entirely in Australia.
Market Cap: A$122 million
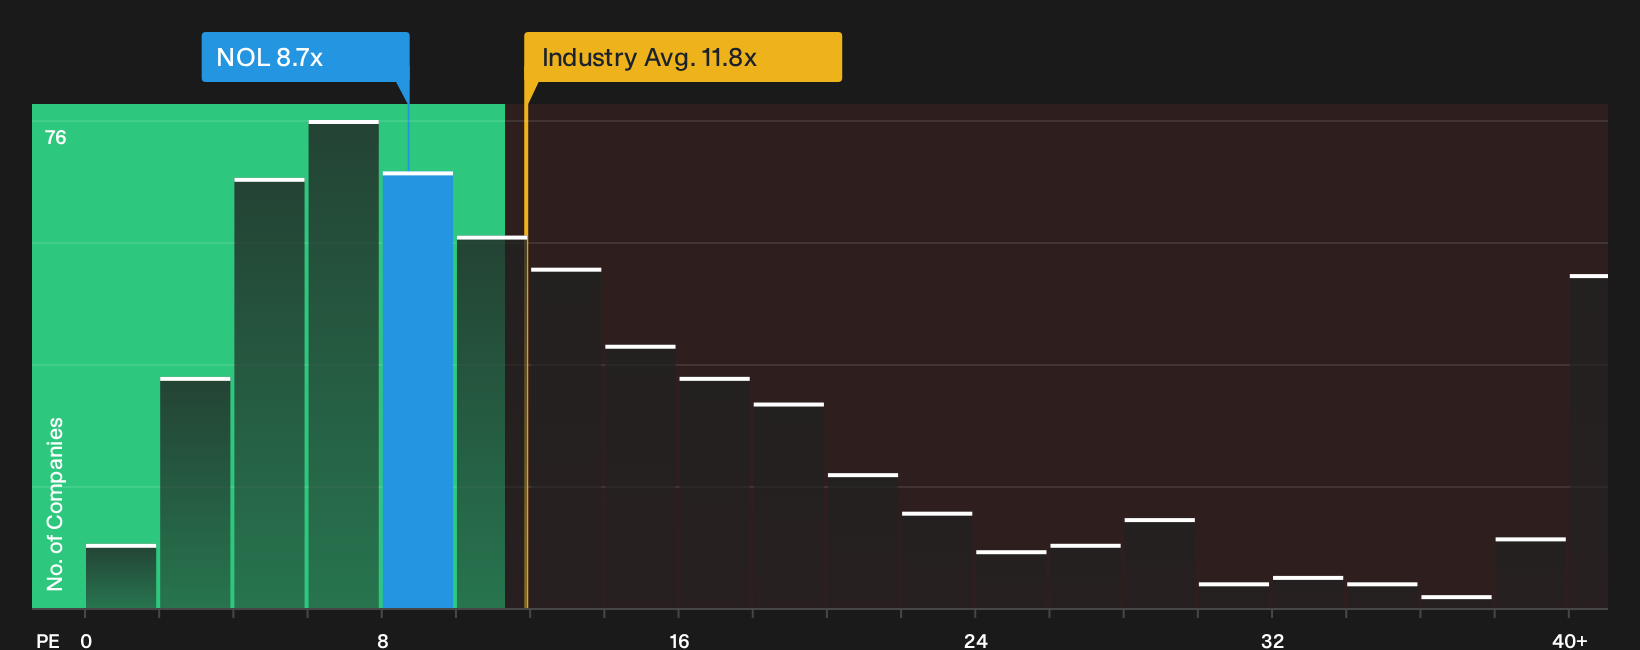
NobleOak Life lines up with this cash-flow screen because recurring life insurance premiums support DCF forecasts. The shares trade at a P/E of 8.7x versus an 11.8x industry average, and investors focused on that gap will be watching what happens if one funding-side pressure reshapes how confidently those future premiums convert into long-run cash flows.
If that pressure is on your radar, go straight to the analysis report for NobleOak Life to see how NobleOak Life’s cash engine and funding needs could be decoupling.
JB Hi-Fi (ASX:JBH)
Overview: JB Hi-Fi is a retailer of consumer electronics and home appliances across JB Hi-Fi, The Good Guys, and e&s, generating steady cash-focused retail cash flows.
Operations: JB Hi-Fi Australia contributes A$7.4b of revenue, The Good Guys A$2.9b, JB Hi-Fi New Zealand A$431 million, and e&s A$273 million.
Market Cap: A$7.1b
JB Hi-Fi matters for this cash-flow screen because its big-ticket electronics and appliance stores translate customer demand into relatively steady takings that can be modelled in a DCF, while add-on services keep those receipts coming in between upgrade cycles.
"The acquisition of e&s is expected to enhance JB Hi Fi's access to premium home appliances and expand the customer base to include builders and commercial clients, potentially boosting revenue growth."
What really shapes how that cash story plays out is whether one quiet squeeze on profitability eases or tightens over the next few years.
If you want to see whether that squeeze is masking something bigger, go straight to the full narrative for JB Hi-Fi and see how the JB Hi-Fi story could be accelerating.

Curious About What You Might Be Missing?
Fresh ideas can move first. Some will break out while others get caught dropping before the crowd reacts. Scan the next wave of opportunities while it matters and act now.
- Track income-focused plays holding firm while yields move and compare payouts across the 3 dividend fortresses before these high cash return profiles get fully priced in.
- Spot emerging AI infrastructure momentum early by scanning the curated 89 AI infrastructure stocks and see which enablers of data centers and chips are still under the radar for now.
- Follow potential upside in precious metals producers and review the hand-picked 36 elite gold producer stocks before renewed interest sends the better quality operators higher.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com