
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To National Fuel Gas (NFG) Split Review
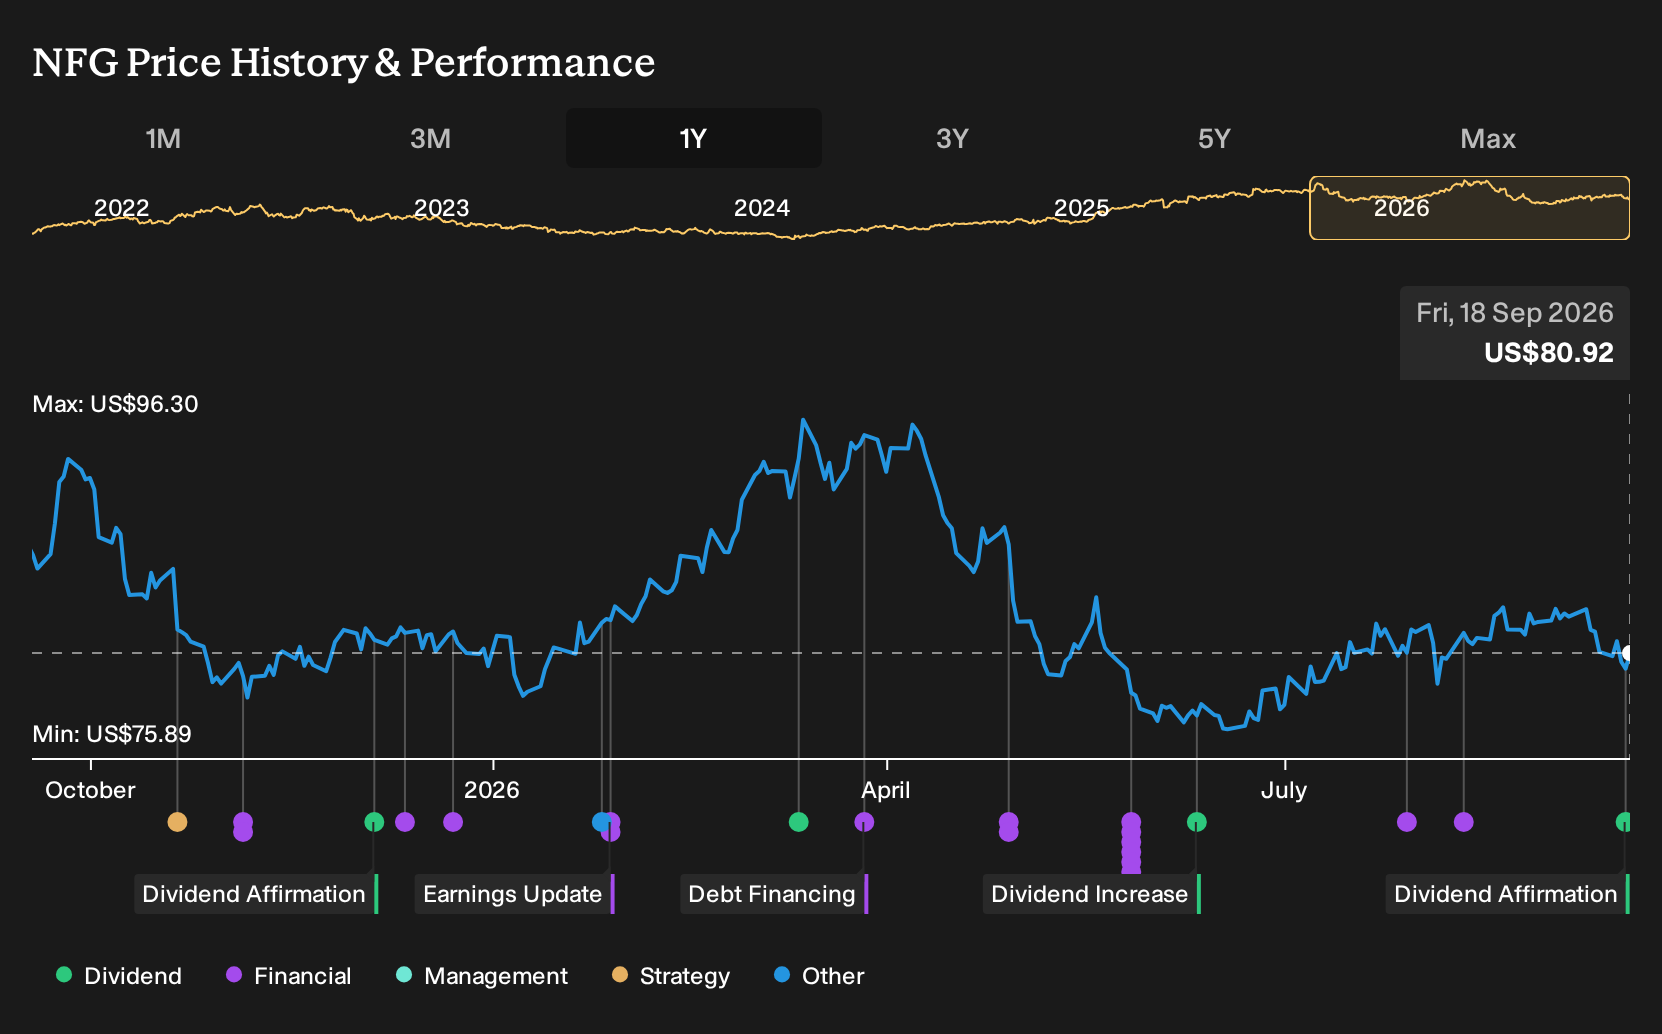
- National Fuel Gas Company confirmed a regular quarterly dividend of US$0.555 per share, payable on 15 October 2026 to roughly 95.0 million common shares on record as of 30 September 2026.
- The review of a potential split between the integrated upstream and gathering operations and the regulated utility and pipeline assets highlights how different capital needs and regulatory pressures may be pushing National Fuel Gas toward a more focused structure.
- We will now look at how National Fuel Gas's potential tax free separation could reshape its long term investment narrative.
Scan beyond National Fuel Gas and compare this potential breakup story to other regulated and infrastructure focused utilities by reviewing our hand picked list of 38 power grid technology and infrastructure stocks.
National Fuel Gas Investment Narrative Recap
To own National Fuel Gas, you need to be comfortable with a regulated utility and pipeline story that is gradually being separated from a more commodity exposed upstream engine. The potential tax free split is the key near term catalyst. It could clarify how cash flows, capital spending, and regulatory oversight line up across the two future entities.
The biggest near term risk still sits around policy pressure on gas usage in New York and Pennsylvania, alongside heavy system modernization and environmental compliance spend. The separation review itself does not change those external risks in a material way. It mainly reframes how investors might track them by business line.
The evaluation of a tax free separation into a pure rate regulated utility and pipeline company, alongside a standalone Appalachian upstream and gathering player, is the announcement that matters most here. It goes straight to how investors think about earnings stability, capital allocation, and the role of the dividend for National Fuel Gas.
Execution on that potential split will intersect with every major catalyst. Pipeline and storage projects such as Shippingport Lateral and Tioga Pathway, Marcellus driven volumes, and ongoing modernization trackers would likely be evaluated inside a more focused regulated entity. The upstream vehicle would be more directly exposed to regional regulation, well performance, and infrastructure access.
National Fuel Gas' current analyst narrative points to revenues of US$3.3b and earnings of US$764.2 million by 2029, based on a 9.1% yearly revenue growth assumption and an earnings increase of about US$88.9 million from earnings today of US$675.3 million.
Uncover why National Fuel Gas' fair value indicates a 14% potential upside to its current price before the market closes and narrows that discount gap.
Exploring Other Perspectives
The three Simply Wall St Community fair value estimates for National Fuel Gas span roughly US$92 to about US$132 per share, a wide gap for a single ticker. Those opinions pre date the proposed tax free split and recent dividend affirmation, so use them alongside current policy risks and separation catalysts to explore sharply different scenarios for future performance.
Explore 2 other National Fuel Gas fair value estimates, including one that suggests as much as 64% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your National Fuel Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for National Fuel Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate National Fuel Gas' overall financial health at a glance.
Looking For More Ideas Beyond National Fuel Gas?
If the National Fuel Gas story has sharpened your thinking, use that same lens across the wider market by running a few focused screens on the Simply Wall St Screener.
- For income that aims to balance yield with resilience, review a curated set of high payout candidates through 6 dividend fortresses.
- If capital preservation comes first for you, start with a carefully filtered universe of businesses that score well on stability and financial strength using the 30 resilient stocks with low risk scores.
- To broaden your watchlist with under-followed opportunities that still show solid fundamentals, scan our hand picked 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com