
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Earnings Beat At Abercrombie & Fitch (ANF) Has Changed Its Investment Story
- Abercrombie & Fitch recently reported Q2 revenue and earnings that exceeded analyst expectations, with guidance for the next quarter also above forecasts, supported by brand momentum, merchandise execution, disciplined inventory management, and expanding growth avenues.
- Management raised its fiscal 2026 outlook after delivering record second quarter sales and 15 consecutive quarters of top line growth. This signals confidence in the durability of Abercrombie & Fitch's current operating playbook.
- We will look at how Abercrombie & Fitch's investment narrative is shaped by the stronger than expected earnings and raised guidance.
Scan beyond Abercrombie & Fitch's momentum and line up other retailers and consumer names showing strong quality and value traits using our curated 33 high quality undervalued stocks as a comparison set.
Abercrombie & Fitch Investment Narrative Recap
A shareholder in Abercrombie & Fitch needs to believe the current omnichannel and brand refresh work can translate into steady demand without eroding margins. The recent Q2 beat and raised outlook support that idea in the near term, with disciplined inventory and full price selling helping to offset tariff pressure and mixed regional performance.
The key short term catalyst is execution on merchandise and digital engagement, while maintaining that margin discipline as new stores open and fixed costs rise. The biggest risk remains any renewed softness in the Abercrombie label or Europe, which could quickly pressure earnings if tariff costs continue to build.
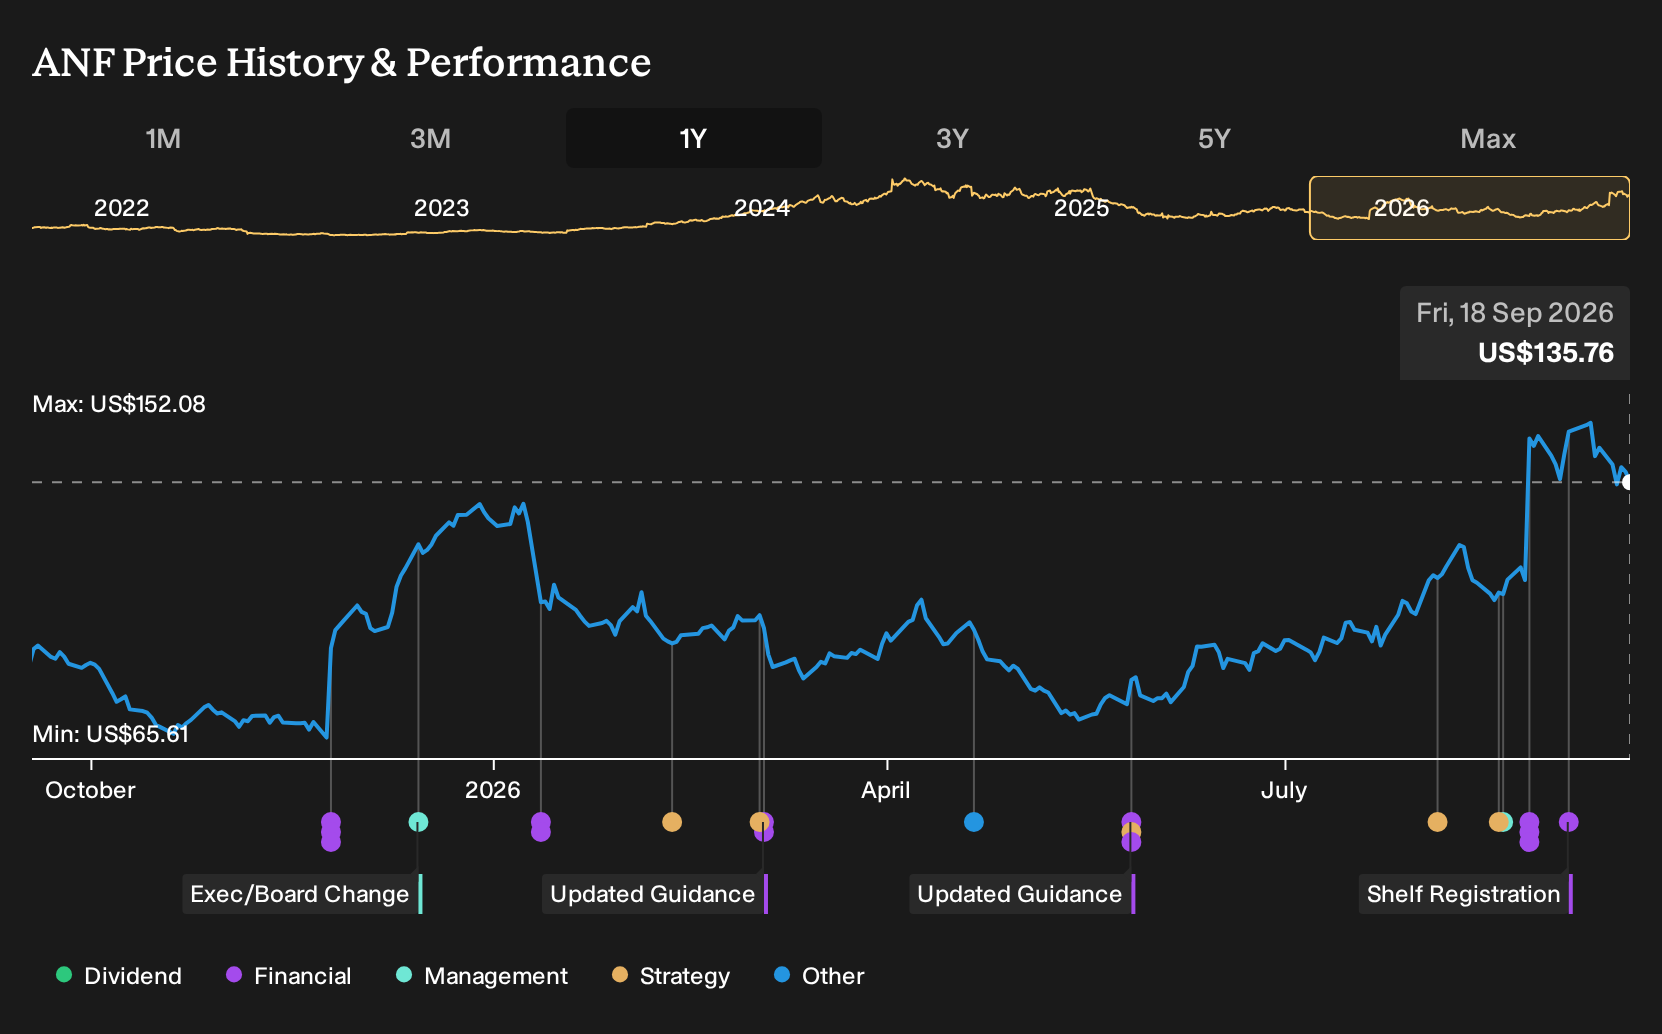
The most relevant recent announcement for this story is Abercrombie & Fitch filing a shelf registration for about US$98.65 million of Class A stock tied to its employee stock ownership plan. That move links more of the workforce to long term performance at a time when execution on merchandising, marketing and supply chain choices matters for sustaining current momentum.
For you as an investor, this ESOP related filing sits alongside other capital decisions such as prior buybacks and supports a narrative where capital allocation and employee incentives are important parts of the thesis. It does not materially change the near term catalyst or risk, but it reinforces attention on how effectively management converts current strength into durable operating performance.
Abercrombie & Fitch's current analyst framework points to revenues of US$5.9b and earnings of US$504.8m by 2029, based on assumed yearly revenue growth of 3.7% and an earnings increase of about US$11.2m from US$493.6m today.
Uncover why Abercrombie & Fitch's fair value indicates a 10% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternative view fixates on heavy reliance on physical stores. Before this news, the most pessimistic analysts were penciling in about US$6.1b of revenue and US$577.0m of earnings by 2029, yet still saw limited upside at a lower P/E ratio. That contrast shows how sharply opinions on Abercrombie & Fitch can diverge. You can explore both narratives and decide which assumptions feel more realistic to you, especially as fresh results and ESOP news may eventually reshape these forecasts.
Explore 4 other Abercrombie & Fitch fair value estimates, including one that suggests there may be as much as 10% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Abercrombie & Fitch research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Abercrombie & Fitch. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Abercrombie & Fitch's overall financial health at a glance.
Looking for more Abercrombie & Fitch style investment ideas?
If Abercrombie & Fitch has sharpened your focus on quality, price and durability of the business model, it can help to compare it with other stocks that share similar traits. The Simply Wall St Screener lets you scan the market quickly so you can build a watchlist that fits your own risk tolerance and return goals.
Here are a few curated starting points you can use right away:
- If you care most about paying a sensible price for strong fundamentals, line up potential ideas using our curated 33 high quality undervalued stocks as a reference set.
- If defence matters more than offence in your portfolio, filter for companies with robust finances by running the list of solid balance sheet and fundamentals (23 results).
- If you want to focus on resilience and smoother return profiles, narrow your search with the 30 resilient stocks with low risk scores and see which businesses fit your comfort zone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com