
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Resonac Holdings (TSE:4004)'s AI Research Platform Means For Shareholders
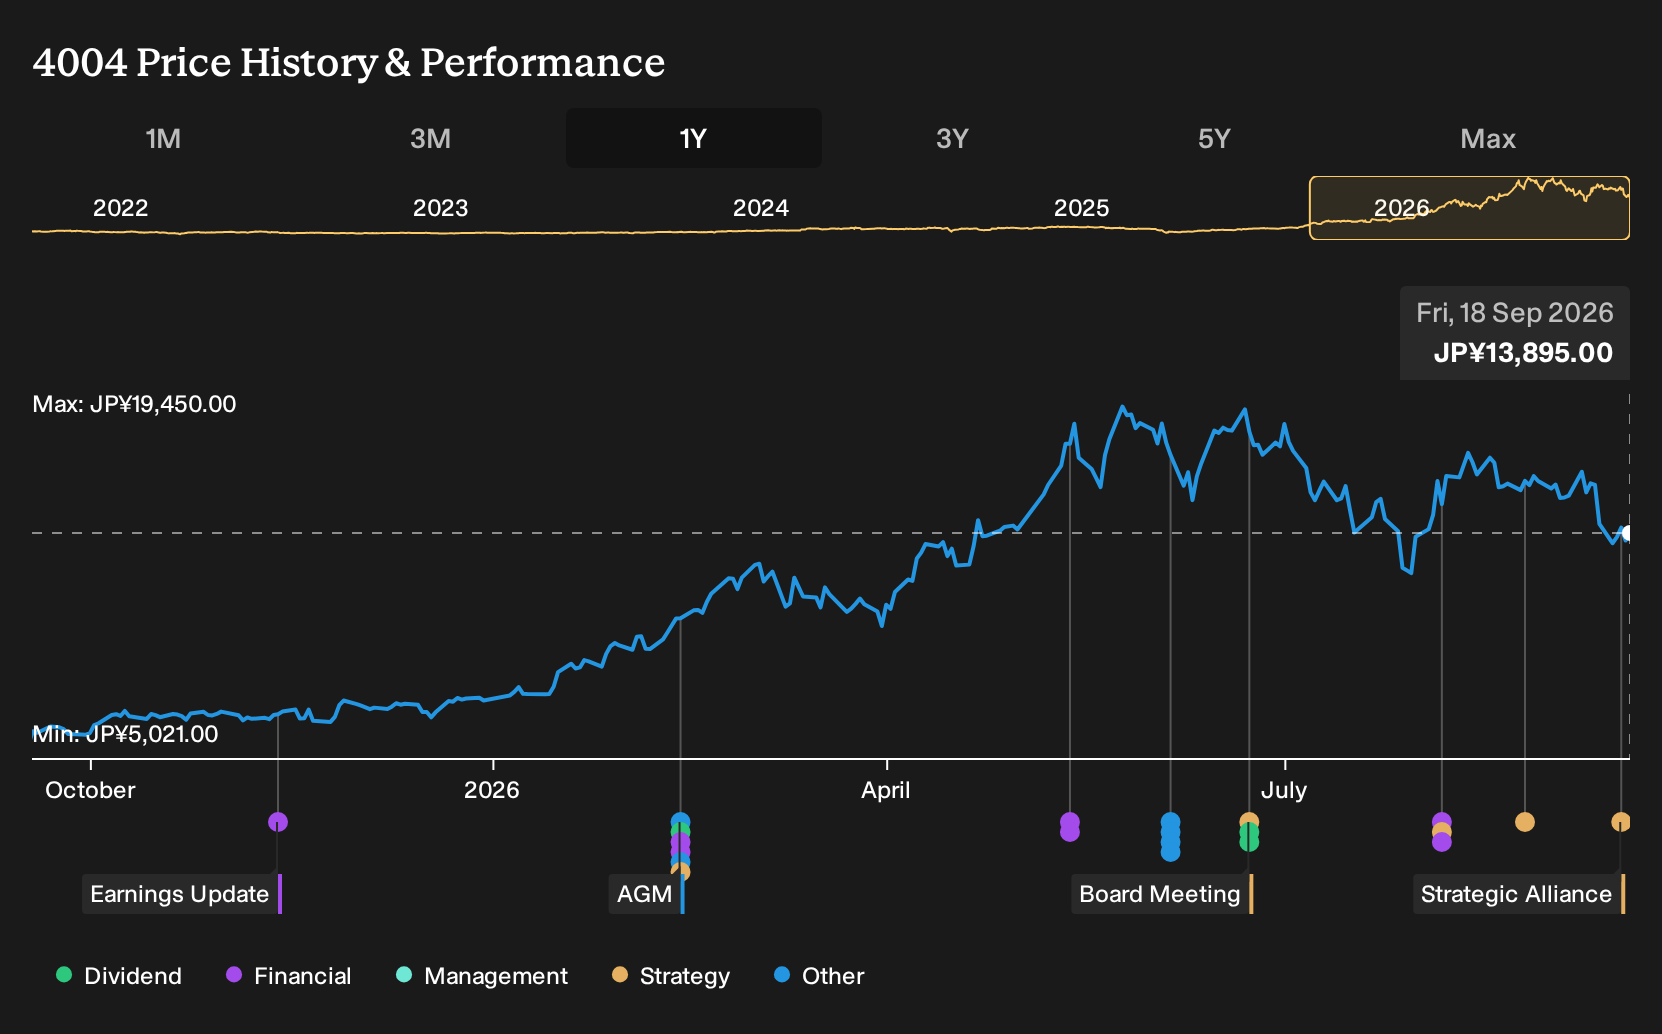
- Matlantis Inc. reported that since October 2025 it has worked with Resonac Corporation and Preferred Networks on Matlantis Case Studio, an AI supported feature that lets experimental chemists at Resonac run atomistic simulations without programming, with an alpha version now planned for cooperating user companies.
- The co creation process, tied directly to Resonac research sites where chemists and computational scientists repeatedly tested prototypes, points to a push to embed digital tools into day to day R&D workflows rather than keeping computational science confined to specialists.
- The next area of focus is how Resonac Holdings' investment narrative could be reshaped by making AI guided simulations accessible to experimental chemists.
Resonac Holdings Investment Narrative Recap
For a shareholder in Resonac Holdings, the central belief is that management can turn heavy R&D and semiconductor material focus into durable earnings while carrying meaningful debt. The short term catalyst is execution on higher value applications such as AI related materials and digital R&D tools. The Matlantis Case Studio news fits that story, but its direct financial impact looks limited in the near term.
The more pressing risk is still balance sheet pressure if cash generation lags investment and restructuring. Exposure to semiconductor cycles and weaker auto or chemicals demand can quickly feed into volatile earnings and share price moves. The Case Studio collaboration helps operationally, but it does not change those core sensitivities at this stage.
Among recent developments, the push to integrate computational science and informatics into Resonac Holdings’ R&D engine is closest to this Matlantis partnership. Management has described this as a way to tighten the link between research sites and product pipelines, which matters for shareholders watching how the R&D base is used.
Matlantis Case Studio gives that ambition a specific tool. Making atomistic simulation available to experimental chemists could support semiconductor and advanced materials projects that underpin the current investment focus. The execution test is whether these digital workflows translate into commercially relevant products quickly enough to support cash flow while the group carries debt and reshapes lower margin segments.
Resonac Holdings' current analyst storyline points to revenues of ¥1.453b and earnings of ¥198.8b by 2029, based on an assumed 1.7% yearly rise in sales and a move from ¥57.8b in earnings today to that forecast level, an increase of about ¥141b over the period.
Uncover why Resonac Holdings' fair value indicates a 52% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on potential upside from Resonac Holdings extracting more value from its semiconductor materials push. Some of the most optimistic analysts were already modeling revenue of ¥1,743.2b and earnings of ¥273.5b by 2029 before this Matlantis Case Studio update. That is a far brighter story. Use that contrast to consider how your own view might shift as this AI driven R&D rollout evolves.
Explore 2 other Resonac Holdings fair value estimates, including one that suggests as much as 102% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Resonac Holdings research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Resonac Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Resonac Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Resonac Holdings?
If this Resonac Holdings story has you thinking more broadly about where to put fresh capital to work, the Simply Wall St screener can help you cast a wider net in a structured way.
- If resilience matters most to you, filter for companies with steadier profiles using our 21 resilient stocks with low risk scores that meet strict risk criteria.
- If you prefer to focus on quality that the market may be overlooking, scan a 74 high quality undiscovered gems with robust fundamentals that are still off most investors' radar.
- If balance sheet strength is your starting point, narrow your list to a list of solid balance sheet and fundamentals (20 results) so you are only comparing businesses with stronger financial foundations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com