
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Federated Hermes Stock Earnings Estimate Upgrades
- Federated Hermes has attracted renewed attention after analysts raised earnings estimates and highlighted the firm's strong return on equity and relatively low forward P/E of 9.9x, alongside support from ongoing share buybacks.
- The mix of heavy recent selling, an oversold RSI reading, and a Zacks Rank #2 rating has put Federated Hermes at the center of a debate about whether its current valuation still matches its underlying business strength.
- We will now look at how the investment narrative for Federated Hermes may evolve as earnings expectations change and analyst views converge.
Compare Federated Hermes with a curated group of quality-focused opportunities by scanning the 33 high quality undervalued stocks that share a mix of solid fundamentals and potentially mispriced valuations.
Federated Hermes Investment Narrative Recap
Owning Federated Hermes means believing its active management, money market franchise, and growing ESG and alternatives platform can keep attracting assets in a world where fees are under pressure and passive products remain popular. The key near term swing factor is client flows across money market and fixed income products, given their outsized role in revenue.The recent selling and oversold RSI highlight sentiment more than operations. The more relevant question is whether earnings hold up as markets move and fee pressure persists. The main risk is that softer organic growth or fee compression erodes margins faster than new products like digital assets and private markets can support them.
The most relevant development here is the combination of strong recent return on equity and a forward P/E of 9.9x being highlighted again. That pairing pushes investors to focus on whether Federated Hermes can keep converting its AUM mix into high quality earnings without relying solely on market moves or buybacks.
If profitability remains solid while the business continues to broaden into ESG, private markets, and tokenized money market products, that earnings profile could act as a support for sentiment after periods of selling pressure. If fee pressure, regulatory costs, or weaker fixed income flows bite harder, the same metrics investors are watching today could become a headwind instead of a support.
What The Federated Hermes Forecasts Really Assume
Federated Hermes' story over the next few years is being sketched out with relatively steady top line expectations and only modest shifts in profitability, which keeps the focus squarely on how efficiently the firm turns its asset base into earnings. Analysts are not banking on rapid expansion, so any surprise is more likely to come from changes in mix, pricing, or costs than from dramatic swings in revenue.
Under the current consensus, analysts expect revenue to stay broadly flat over the next three years while profit margins edge up from 20.3% today to 20.5% by 2029. Earnings today are pegged at US$393.2 million and are projected to reach US$402.6 million by the 2029 financial year, which implies an earnings increase of about US$9.4 million on current figures. Those forecasts sit alongside an assumed decline of roughly 3.71% per year in the share count, which means any earnings per share outcome also depends on how aggressively Federated Hermes continues its buyback program.
Federated Hermes' narrative projects US$2.0b revenue and US$402.6 million earnings by 2029. This points to flat yearly revenue growth and an earnings increase of about US$9.4 million from current earnings of US$393.2 million.
The valuation setup that flows from these assumptions is fairly specific. For the analyst price target of US$59.86 to hold, the business would need to generate about US$2.0b of revenue and US$402.6 million of earnings in 2029 and trade on a P/E of 11.9x on those earnings. That multiple sits below the cited 37.9x P/E for the broader US capital markets peer group. This comparison nudges investors to think about whether Federated Hermes should be treated as a lower growth, more cash generative operator or whether the current gap simply reflects more conservative expectations around scale and competitiveness.
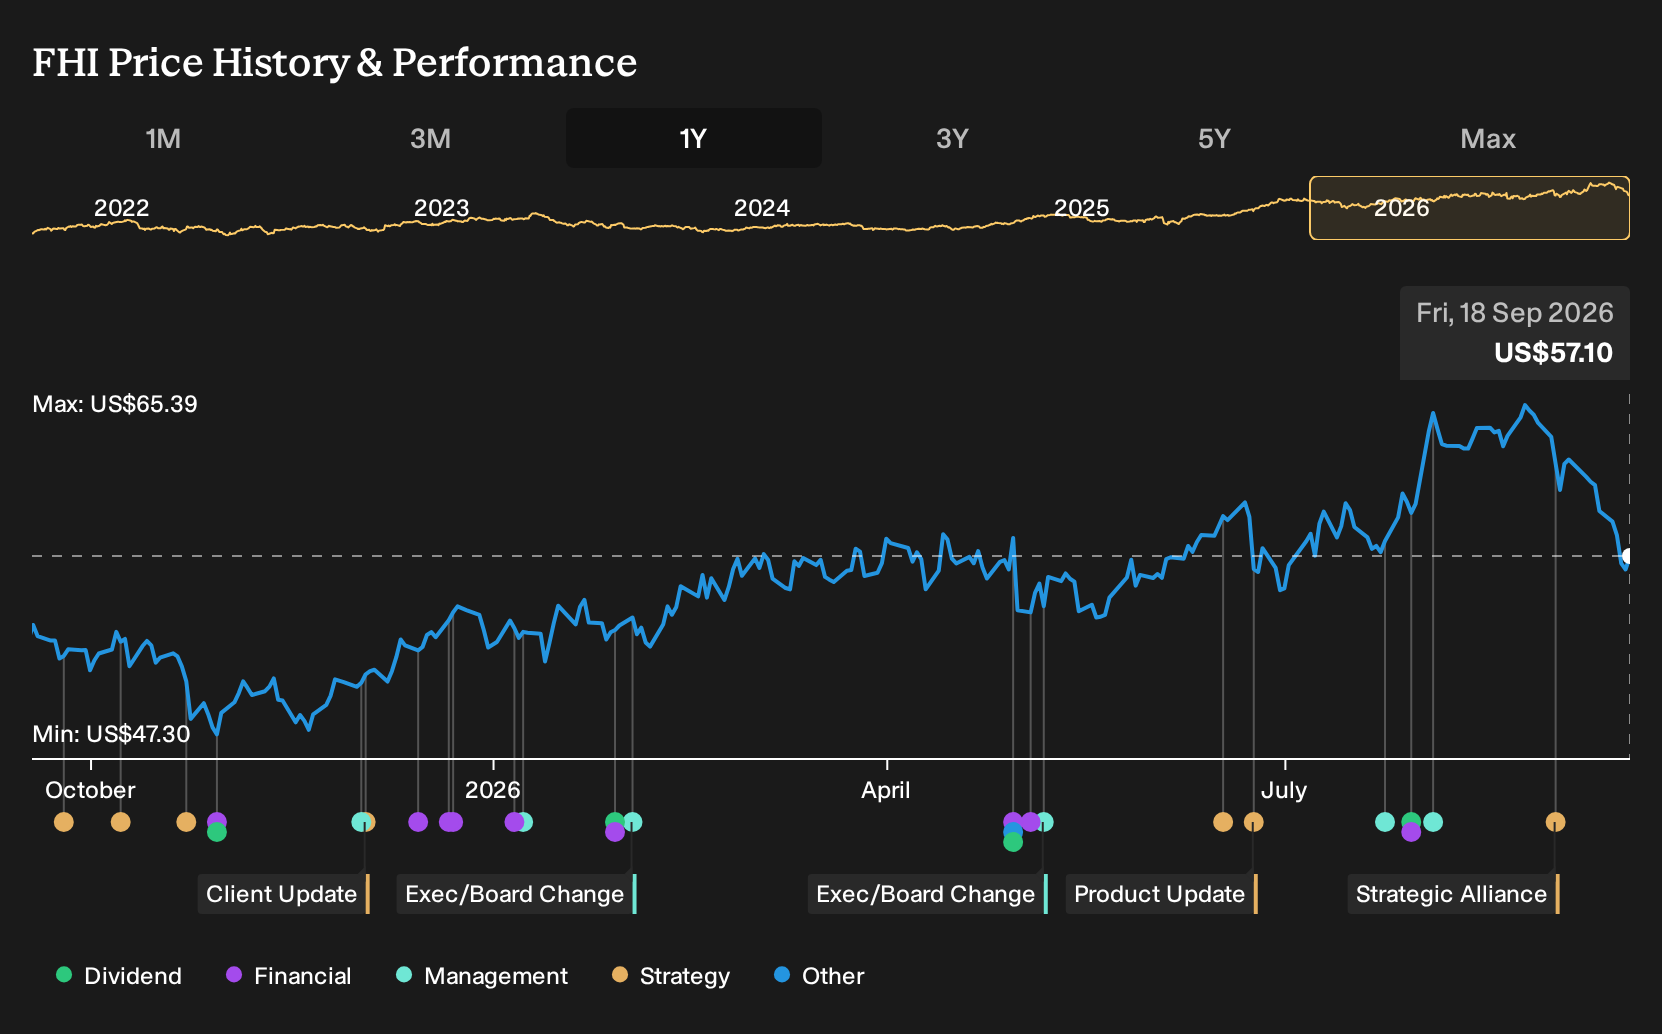
Set against the current share price of US$63.14, the consensus target that is 5.5% lower suggests analysts see the stock as roughly in line with their assumptions rather than clearly mispriced. For readers, the key question is whether flat revenue, a slight margin lift, and a modest earnings step-up to US$402.6 million in 2029 feel realistic given what is known today about product mix, fee trends, and the pace of change in ESG, private markets, and digital asset offerings.
Uncover why Federated Hermes' fair value indicates a 5% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$59.86 to US$71.55, which puts Federated Hermes in a band that ranges from slightly below to meaningfully above current trading levels. Before acting, weigh those retail viewpoints against risks around fee compression and money market reliance, and potential catalysts in digital assets and ESG demand.
Explore another Federated Hermes fair value estimate, including one that suggests it could be worth just $59.86.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Federated Hermes research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Federated Hermes. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Federated Hermes' overall financial health at a glance.
Looking for more investment ideas beyond Federated Hermes?
If the Federated Hermes narrative has sharpened how you think about valuation, income, and balance sheet quality, you can use that same framework to scan a wider field of opportunities on the Simply Wall St Screener.
- For investors who want resilient balance sheets and steady fundamentals, review the list of solid balance sheet and fundamentals (23 results) that might better match your risk tolerance.
- If you are hunting for mispriced quality with room for sentiment to catch up, consider the 16 high quality undiscovered gems that fit your preferred metrics and time horizon.
- Those who prioritize stability and income can filter for companies in the 6 dividend fortresses and see which payouts align with their return goals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com