
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kyushu Electric Power Company (TSE:9508) Deepens ProLogium Ties As Valuation Debate Builds
Kyushu Electric Power Company (TSE:9508) is deepening its relationship with ProLogium Group through a new capital investment. This move expands an existing collaboration in energy, next generation batteries and related industrial applications.
For context, Kyushu Electric Power Company’s share price closed at ¥2,128.5, with the stock easing around 2% over both the past day and week. It has posted a 30 day share price return of 13.61% and a 90 day share price return of 30.02%, which aligns with a 1 year total shareholder return of 45.18% and a 5 year total shareholder return of 173.41%. This suggests momentum has been building, even as the latest ProLogium investment adds a fresh catalyst to an already strong run.
Scan how Kyushu Electric Power Company's battery partnership compares with other grid and electrification players by reviewing our curated 38 power grid technology and infrastructure stocks in the same space.
The fresh ProLogium investment could signal deeper confidence in Kyushu Electric Power Company's core business rather than just a hot theme trade. To sort substance from sentiment, the next step is to test what investors are paying for today.
Price-to-Earnings of 6.2x: Is it justified?
On recent numbers, Kyushu Electric Power Company trades on a P/E of 6.2x against a last close of ¥2,128.5, which points to a lower earnings multiple than both the broader Japan market and its own electric utilities peers.
The P/E ratio compares the current share price to earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a regulated utility with established operations in Japan and overseas, that earnings yardstick often matters more to investors than headline revenue growth alone.
Here, the market is valuing Kyushu Electric Power Company at 6.2x earnings while the JP market trades at 14.1x, and the Asian electric utilities industry sits around 13.8x. That is a steep gap, and the fair P/E estimate of 10.5x suggests pricing could move closer to a mid range level if current profit quality, return profile and past growth rates are maintained in investors’ models.
Explore the SWS fair ratio for Kyushu Electric Power Company.
Result: Price-to-Earnings of 6.2x (UNDERVALUED).
Still, the narrative around Kyushu Electric Power Company can be knocked off course if regulated returns tighten or if annual net income, which recently declined slightly, loses further support.
Find out about the key risks to this Kyushu Electric Power Company narrative.
Another view on Kyushu Electric Power Company’s value
Those P/E comparisons paint Kyushu Electric Power Company as cheap, yet the SWS DCF model points the other way. On that framework, the current price of ¥2,128.5 sits far above an estimated future cash flow value of ¥273.83, which frames the stock as heavily overvalued on a cash generation basis.
That kind of gap signals real valuation risk if future cash flows track the DCF inputs more closely than today’s earnings snapshot. Look into how the SWS DCF model arrives at its fair value.
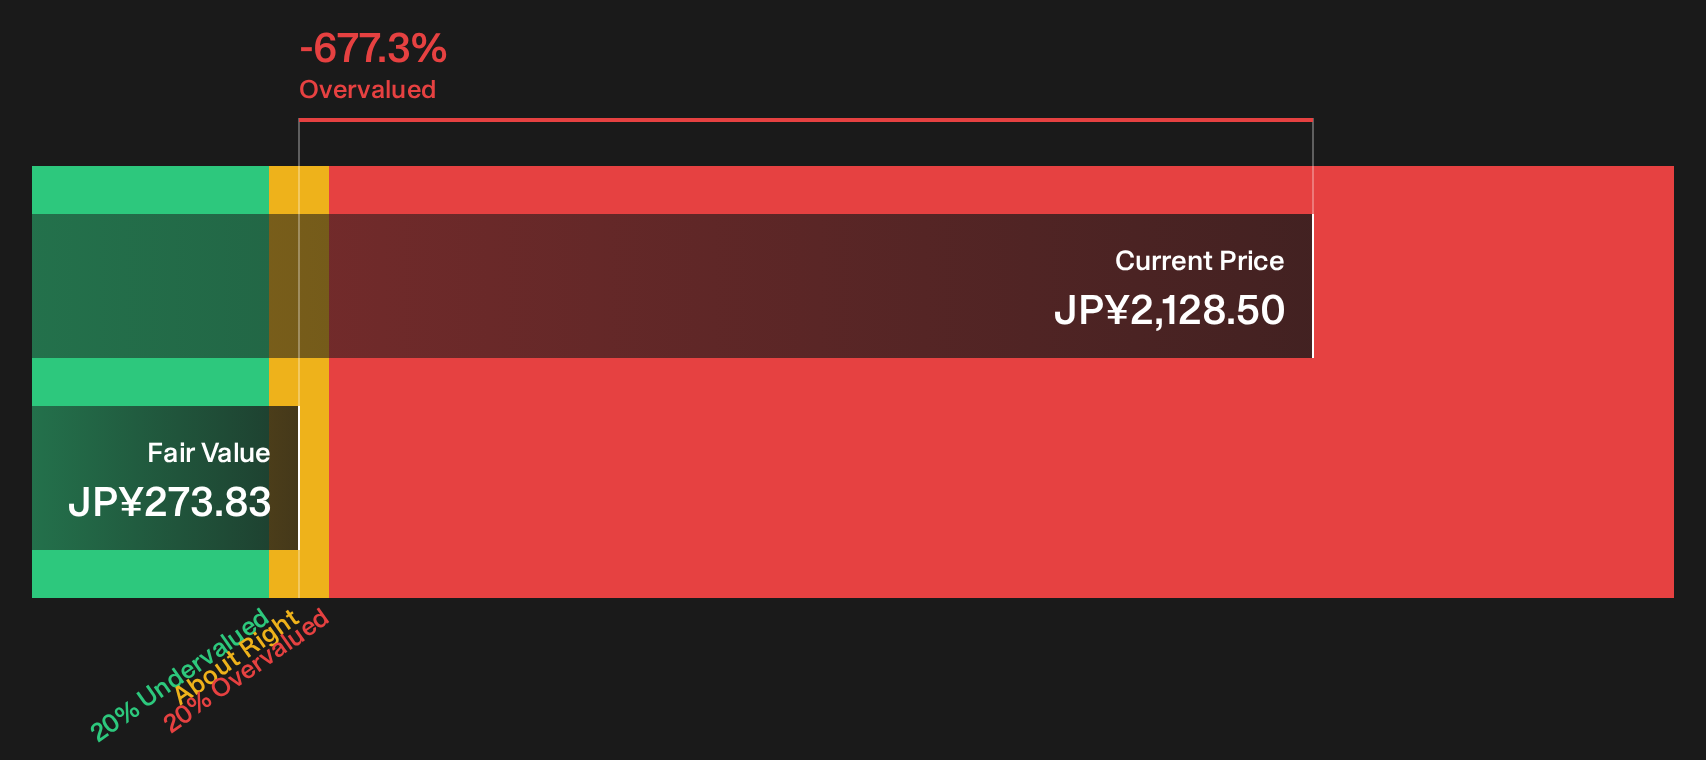
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kyushu Electric Power Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Kyushu Electric Power Company so far. If you want to move quickly and judge the balance of risk and upside yourself, go straight to the 3 key rewards and 3 important warning signs.
Looking for more Kyushu Electric Power Company sized ideas?
Do not stop your research at Kyushu Electric Power Company. Broaden your watchlist with fresh ideas that match your risk, income and quality preferences.
- Target potential mispricing in established businesses by scanning our 17 high quality undervalued stocks which blends fundamental strength with attractive valuation signals.
- Strengthen the income side of your portfolio by reviewing the 14 dividend fortresses which can help support more reliable cash returns.
- Dial down portfolio stress by focusing on resilience through the 21 resilient stocks with low risk scores which screens for steadier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com