
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Half Year Earnings Growth Require Action From EL.En (BIT:ELN) Investors?
- EL.En. reported half year 2026 results, with sales of €246.45 million, revenue of €254.38 million and net income of €26.1 million, all above the prior period.
- The wider gap between revenue and net income compared with last year points to changing cost dynamics and operating efficiency inside EL.En.
- Next, the focus turns to how EL.En's stronger half year net income reshapes the existing investment narrative that investors have been using.
EL.En Investment Narrative Recap
To own EL.En, you need to believe the medical and industrial laser franchises can keep converting technical know how into steady orders, even while parts of the industrial cutting business stay soft. The half year revenue of €254.38 million and net income of €26.1 million suggest the group is currently executing on that thesis.
In the near term, the key catalyst is whether management can keep margins resilient while working through the divestiture of laser metal cutting units and any weakness in Italy and China. The biggest risk remains disruption or dilution of earnings from those sales, alongside legal disputes that could hit net margins.
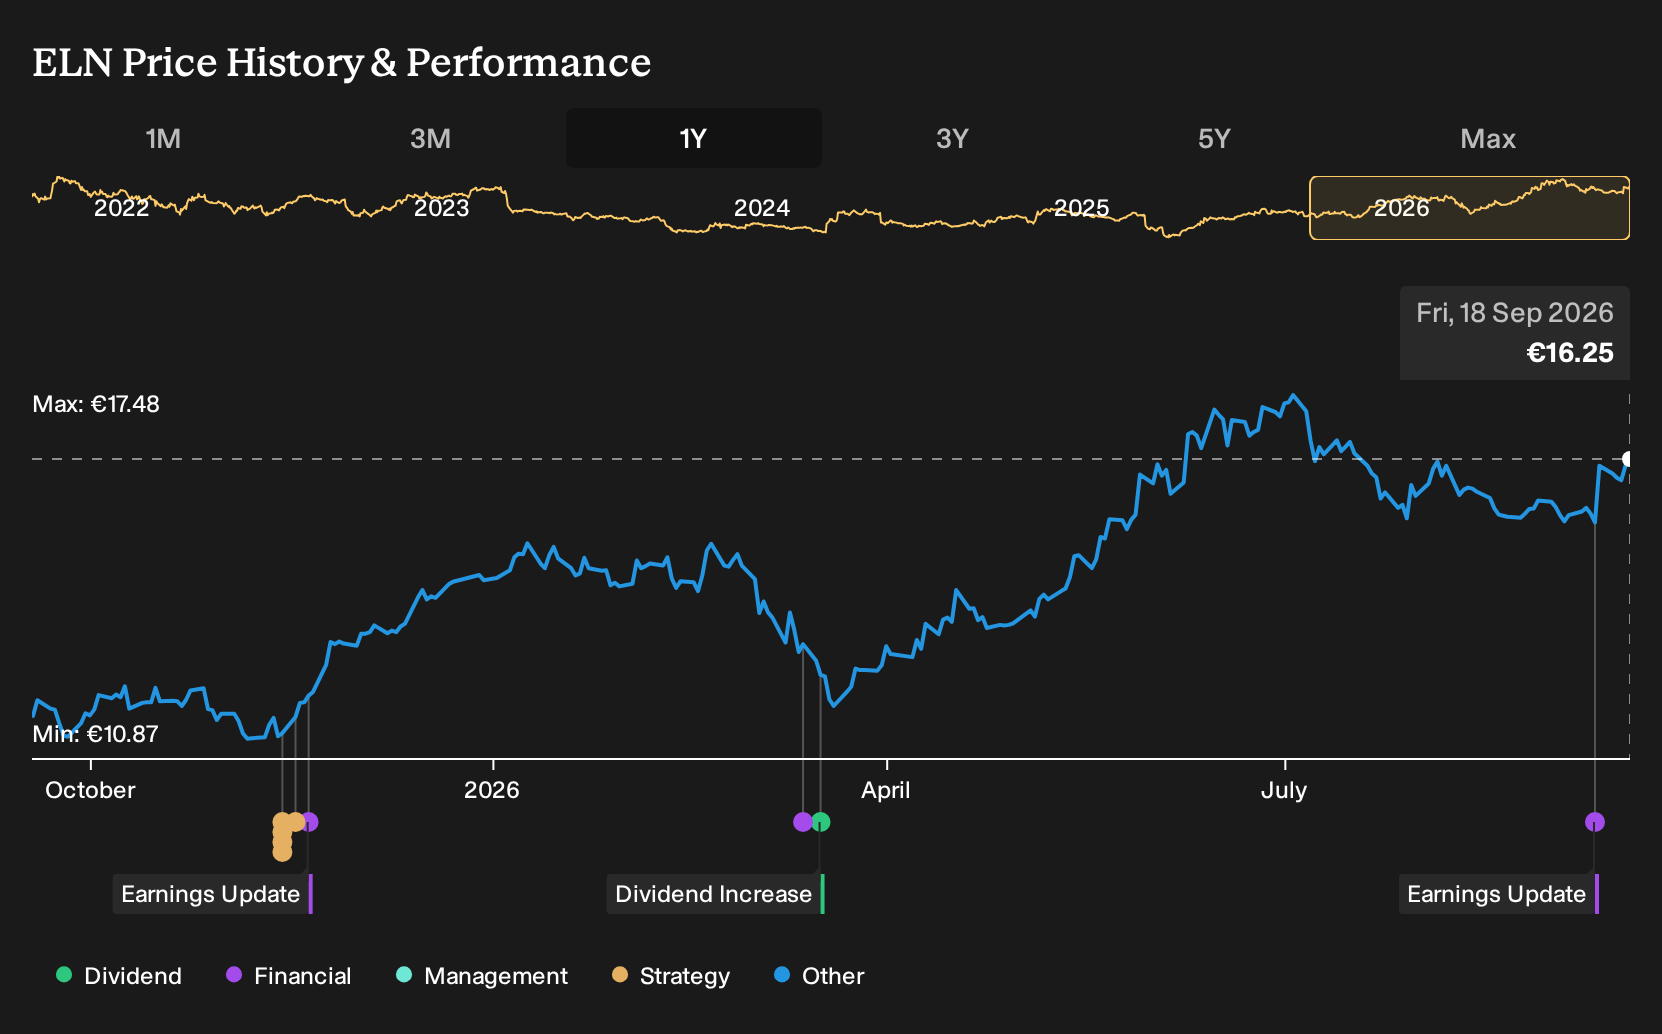
The latest half year earnings announcement is central here because it lands while EL.En is still working through divestments and Chinese exposure. Higher net income of €26.1 million, against €17.93 million a year earlier, offers fresh evidence on how the business holds up while the cutting segment faces pressure.
For catalysts, investors are watching whether future reports show cleaner profitability once non core cutting assets are sold and focus shifts further toward medical lasers and customized systems. Execution around legal provisions and any progress on Chinese operations will also influence how durable this higher earnings base really is.
What EL.En's Forecasts Assume
EL.En's narrative projects forecast revenue of €675.9 million and earnings of €66.1 million by 2028. Analysts are building this on 5.4% yearly revenue growth and an earnings increase of about €3.8 million from current earnings of €62.3 million.
Uncover how EL.En's fair value indicates a 20% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
For EL.En, the alternate story puts regulatory risk in the spotlight. The most cautious analysts worried that tighter medical approvals could slow product launches, even as they pencilled in around €708.7 million of revenue and €70.7 million of earnings by 2029. Those forecasts came before this half year update, so views may evolve. You do not need to pick a side. Use these contrasting narratives as a map to explore different scenarios and decide which assumptions feel closest to your own.
Explore another EL.En fair value estimate, including one that suggests as much as 37% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider going with your instincts.
- A great starting point for your EL.En research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for EL.En. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate EL.En's overall financial health at a glance.
Looking for more EL.En sized investment ideas?
Once you have a view on EL.En, it helps to compare that thesis against a watchlist of other businesses with different risk and income profiles. The Simply Wall St Screener can surface a wide mix of potential candidates, so you can pressure test your assumptions rather than anchor on a single stock.
- For readers hunting for upside with less obvious crowd attention, scan a curated set of 612 high quality undiscovered gems that combine strong fundamentals with lower visibility in the market.
- If capital protection and smoother portfolio swings matter more to you than chasing every hot story, focus on a 227 resilient stocks with low risk scores that filters for resilient balance sheets and lower risk scores.
- Income orientated investors who want cash hitting their account on a regular basis can head straight to a 155 dividend fortresses that highlights stocks with yields of 5% or more.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com