
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Graphic Packaging Stock Gets Top ESG Ranking On 3BL Best Corporate Citizens List
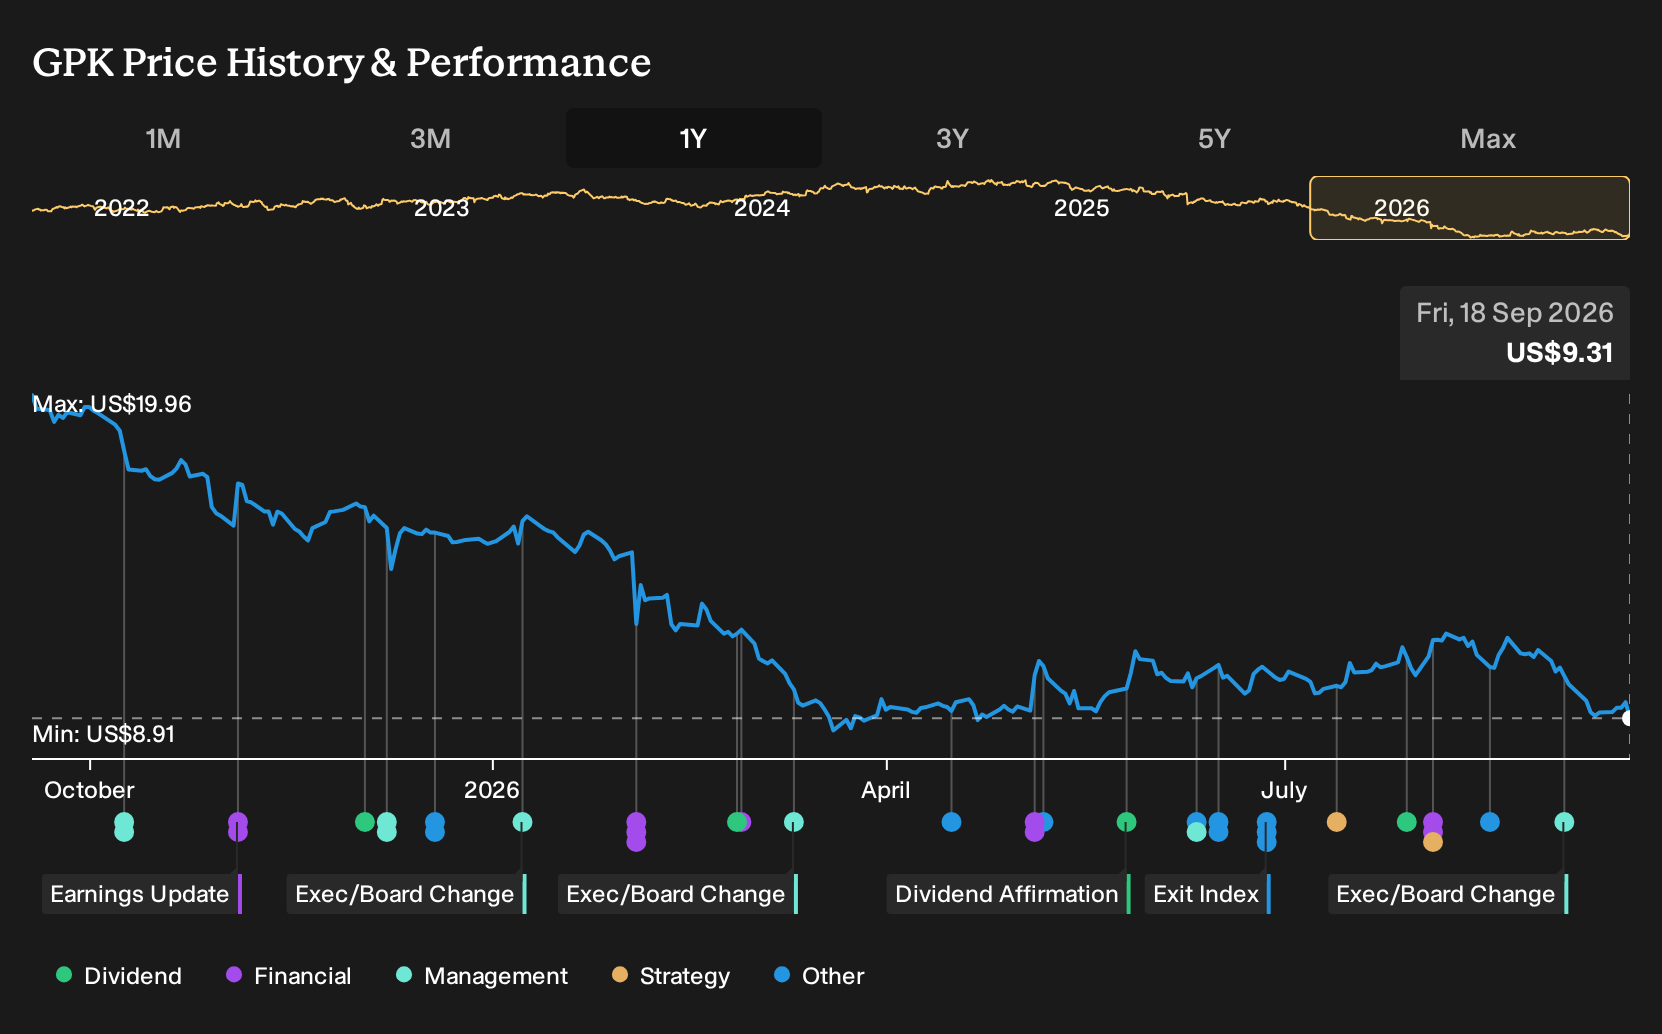
- Graphic Packaging Holding was recently ranked No. 5 overall and No. 1 in the materials sector on 3BL's 2026 100 Best Corporate Citizens list, recognizing its approach to environmental, social, and governance practices.
- This ESG recognition aligns directly with Graphic Packaging Holding's focus on sustainable fiber-based packaging and operational excellence, which sit at the center of its cost structure, customer relationships, and long-term capital allocation decisions.
- We will now assess how Graphic Packaging Holding's corporate citizenship leadership could reshape the investment narrative built around sustainable packaging economics.
Scan how Graphic Packaging Holding fits into a broader sustainability theme by comparing it with other companies on our curated list of list of solid balance sheet and fundamentals (23 results).
Graphic Packaging Holding Investment Narrative Recap
An investor in Graphic Packaging Holding needs to believe that demand for fiber based, recyclable packaging supports steady use of its large paperboard footprint and that cost efficiency projects translate into healthier margins and cash generation. The 3BL corporate citizenship ranking reinforces that sustainability messaging. On its own, this recognition does not materially change the key near term swing factors.
The biggest short term swing factor remains execution on high spend projects such as Waco and converting that capacity into low cost volume. The most immediate risk is pressure on profitability, given current 2.2% net margin, interest coverage concerns, and customer consolidation that can weigh on pricing and volumes.
With no new operational announcements tied directly to the 3BL ranking, the most relevant context is still Graphic Packaging Holding’s recycled paperboard build out at Waco. That project is intended to shift mix away from higher cost bleached board and support a lower unit cost base for fiber packaging over time.
This kind of asset footprint matters for catalysts. Efficient mills and more recycled content can support the sustainable packaging thesis that 3BL highlighted, while also giving management more room to defend margins if food and foodservice volumes stay soft or if contract renegotiations with large CPG and QSR customers introduce further pricing pressure.
Graphic Packaging Holding ESG Story Meets The Numbers
Graphic Packaging Holding's narrative projects US$9.0b revenue and US$397.9m earnings by 2029. This assumes 1.5% yearly revenue growth and an earnings increase of about US$204m from US$194.0m today.
Uncover why Graphic Packaging Holding's fair value indicates a 35% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Graphic Packaging Holding, the bearish analysts focus on consumer pullback risk. They were modeling flat revenue near US$8.9b and earnings of about US$293.8m by 2029, far below the most optimistic forecasts. Those lower figures reflect a view that cost inflation and weaker volumes could bite harder, which the new 3BL recognition may eventually challenge or reinforce.
Explore 2 other Graphic Packaging Holding fair value estimates, including one that suggests it could be worth just $12.49!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Graphic Packaging Holding research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Graphic Packaging Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Graphic Packaging Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Graphic Packaging Holding?
Once you have a handle on Graphic Packaging Holding, it can help to widen the lens and compare it with other listed businesses that share some of the qualities you care about most.
- If you are hunting for value with quality fundamentals, scan our curated set of 33 high quality undervalued stocks that pair robust balance sheets with attractive pricing.
- For readers who care about income as much as price appreciation, assess which companies on our 6 dividend fortresses might suit a yield focused approach.
- When capital preservation sits high on your checklist, review the 30 resilient stocks with low risk scores to see which stocks line up with a more defensive profile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com