
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 AI Infrastructure Stocks Riding Data Center Demand
OpenAI’s huge funding ambitions, heavy projected cash burn and plans for hundreds of billions in AI compute have sharpened the focus on who really gets paid in this arms race. The prize is not just hype; it is potential demand for chips, cloud capacity and physical data centers that might reshape balance sheets across global markets. This article walks through 3 stocks from our Global AI Infrastructure Enablers screener that screen as positively exposed to this evolving story.
The three stocks below are a small sample of what rises to the top of this theme. The full screen surfaced 37 more large caps with equally compelling AI infrastructure stories that are not covered in this article.
If you want to identify, compare and analyze potential high-conviction ideas across semiconductors, cloud platforms and data center REITs in one place, head straight to the Global AI Infrastructure Enablers (Semiconductors, Cloud, and Data Center REITs) screener.
ASE Technology Holding (TWSE:3711)
Overview: ASE Technology Holding provides semiconductor packaging, testing and electronic manufacturing services that help power AI chips, servers and other advanced electronics worldwide.
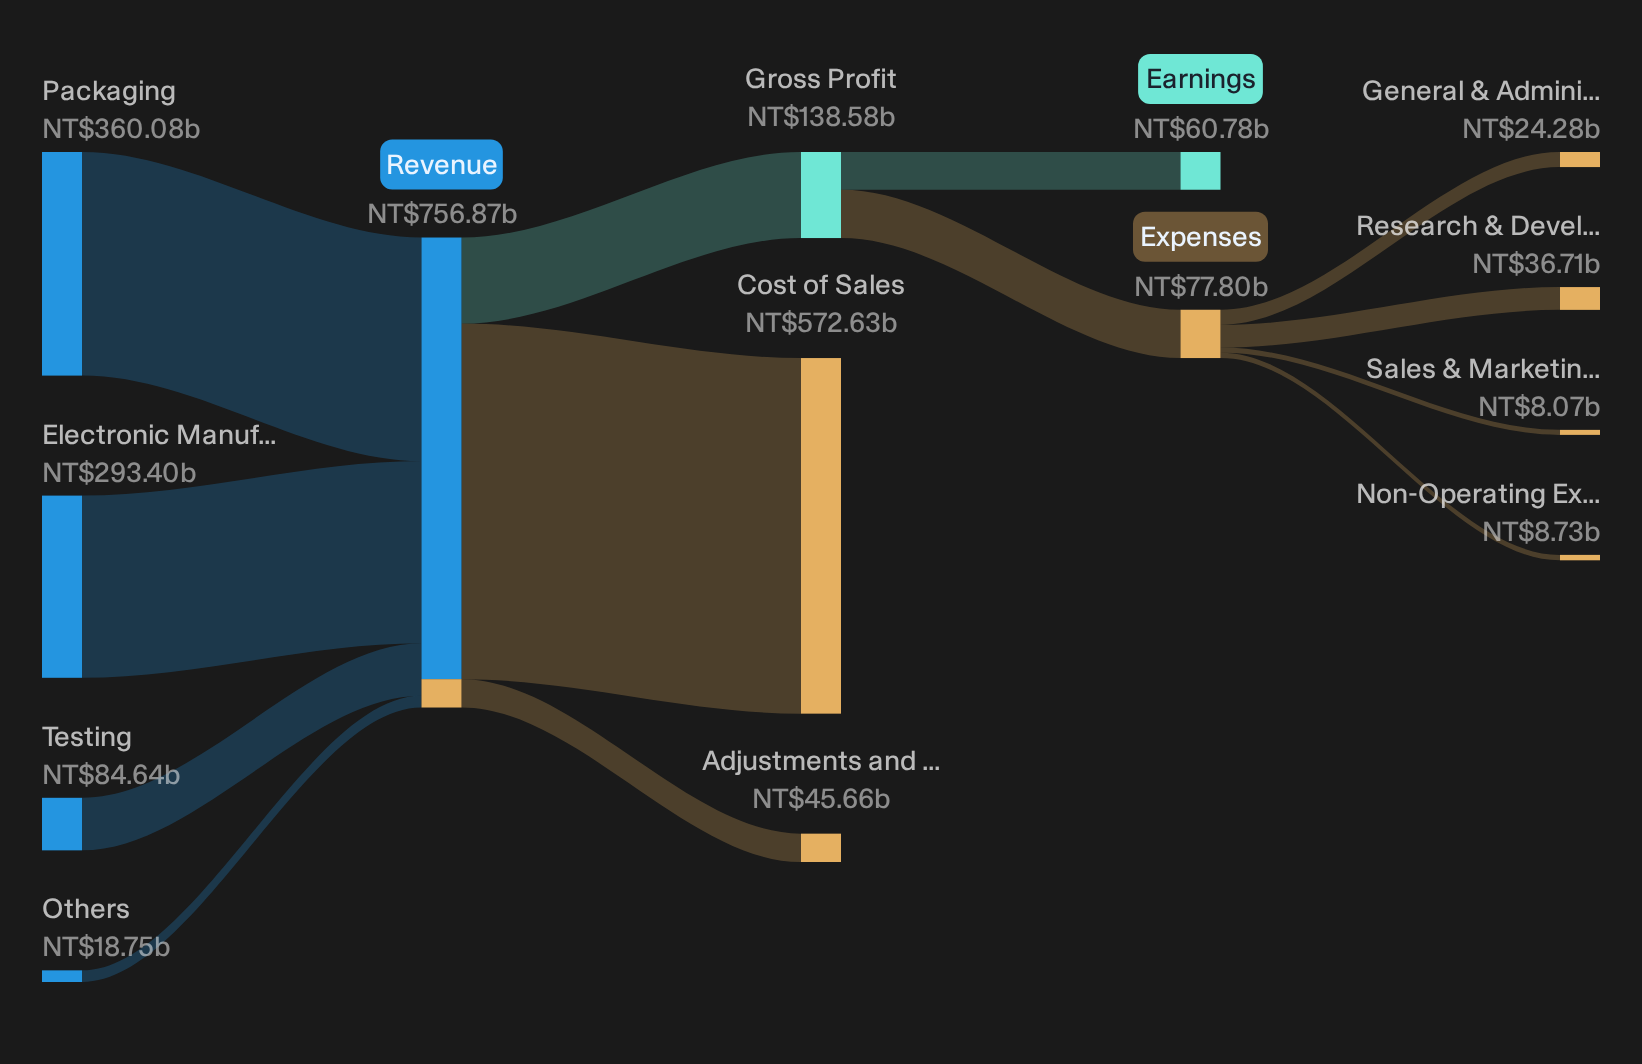
Operations: ASE Technology Holding generates most of its NT$688.1b revenue from packaging at about NT$360.1b and EMS at roughly NT$293.4b, with testing contributing around NT$84.6b.
Market Cap: NT$2.8 trillion
ASE Technology Holding matters in this AI infrastructure theme because its packaging and testing lines help move high performance chips from design slides into working data center hardware.
"Investments in leading-edge technologies (3D IC, chiplet, system-in-package, silicon photonics) and aggressive capacity expansion, especially in advanced packaging/test and fully automated lines, position ASE as a key player to meet next-generation requirements, enabling higher-margin mix and long-term operating margin expansion.
What happens to those margin ambitions depends heavily on how one unseen pressure on AI-related manufacturing costs and pricing ultimately settles.
That pressure is exactly where the story gets interesting, and the full narrative for ASE Technology Holding unpacks how ASE Technology Holding’s capacity bets intersect with pricing power and AI demand cycles.
Wiwynn (TWSE:6669)
Overview: Wiwynn designs and manufactures servers, storage systems and rack solutions that power hyperscale cloud and data center infrastructure for AI workloads.
Operations: Wiwynn generates roughly NT$1.11t in sales from computer hardware, with demand largely tied to America and Asia based data center customers.
Market Cap: NT$1.19t
Wiwynn is directly involved in AI infrastructure, building the server and rack hardware that hyperscale cloud providers use as AI compute expands. Strong recent sales and earnings, a P/E of about 20.5x and a high ROE are balanced against leverage and margin pressure, and the outcome depends in part on how an unresolved cost squeeze develops.
That cost squeeze is exactly where things get interesting for Wiwynn, and the analysis report for Wiwynn shows whether current pricing is masking risk or upside.

Quanta Computer (TWSE:2382)
Overview: Quanta Computer builds laptop PCs and cloud-computing server hardware that anchor hyperscale and AI data center infrastructure worldwide.
Operations: Quanta Computer generates about NT$6.20t from its electronics segment, with reported group revenue shaped by significant internal adjustments and eliminations.
Market Cap: NT$1.32t
Quanta Computer plugs straight into the screener’s theme because its cloud server platforms sit behind the data center capacity that AI models depend on, so any sustained push into high density compute can feed directly into its order book.
"Ongoing expansion and ramp-up of next-generation AI server platforms (GB300) is set to accelerate AI server shipments in late 2025 and 2026, matching surging customer demand for higher computing density driven by rapid adoption of AI/ML workloads, positioning Quanta for sustained revenue growth and increased market share among hyperscale clients."
What that means for investors ultimately comes down to how one pressure on profitability and cash generation is resolved over the next few years.
That pressure is exactly where questions turn into opportunity, and the full narrative for Quanta Computer shows how Quanta Computer’s AI server ramp could reshape risk, cash generation, and upside potential.

Seeking Fresh Alternatives Before They Fly
Some of the sharpest breakout stories start moving while most investors are still watching yesterday’s winners. Scan these fresh ideas before the momentum is gone and act now.
- Spot strong balance sheets before the crowd and review the curated list of solid balance sheet and fundamentals (197 results) that highlights businesses built to withstand shocks, even when others are dropping.
- Ride accelerating demand for automation and track the hand picked 95 robotics and automation stocks that could benefit if spending on efficiency picks up while it still matters.
- Position ahead of the next power crunch and assess the focused 38 power grid technology and infrastructure stocks that groups companies tied to grid upgrades while they remain under the radar for now.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com