
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Hang Seng Index Entry Will Impact Weichai Power Stock Investors
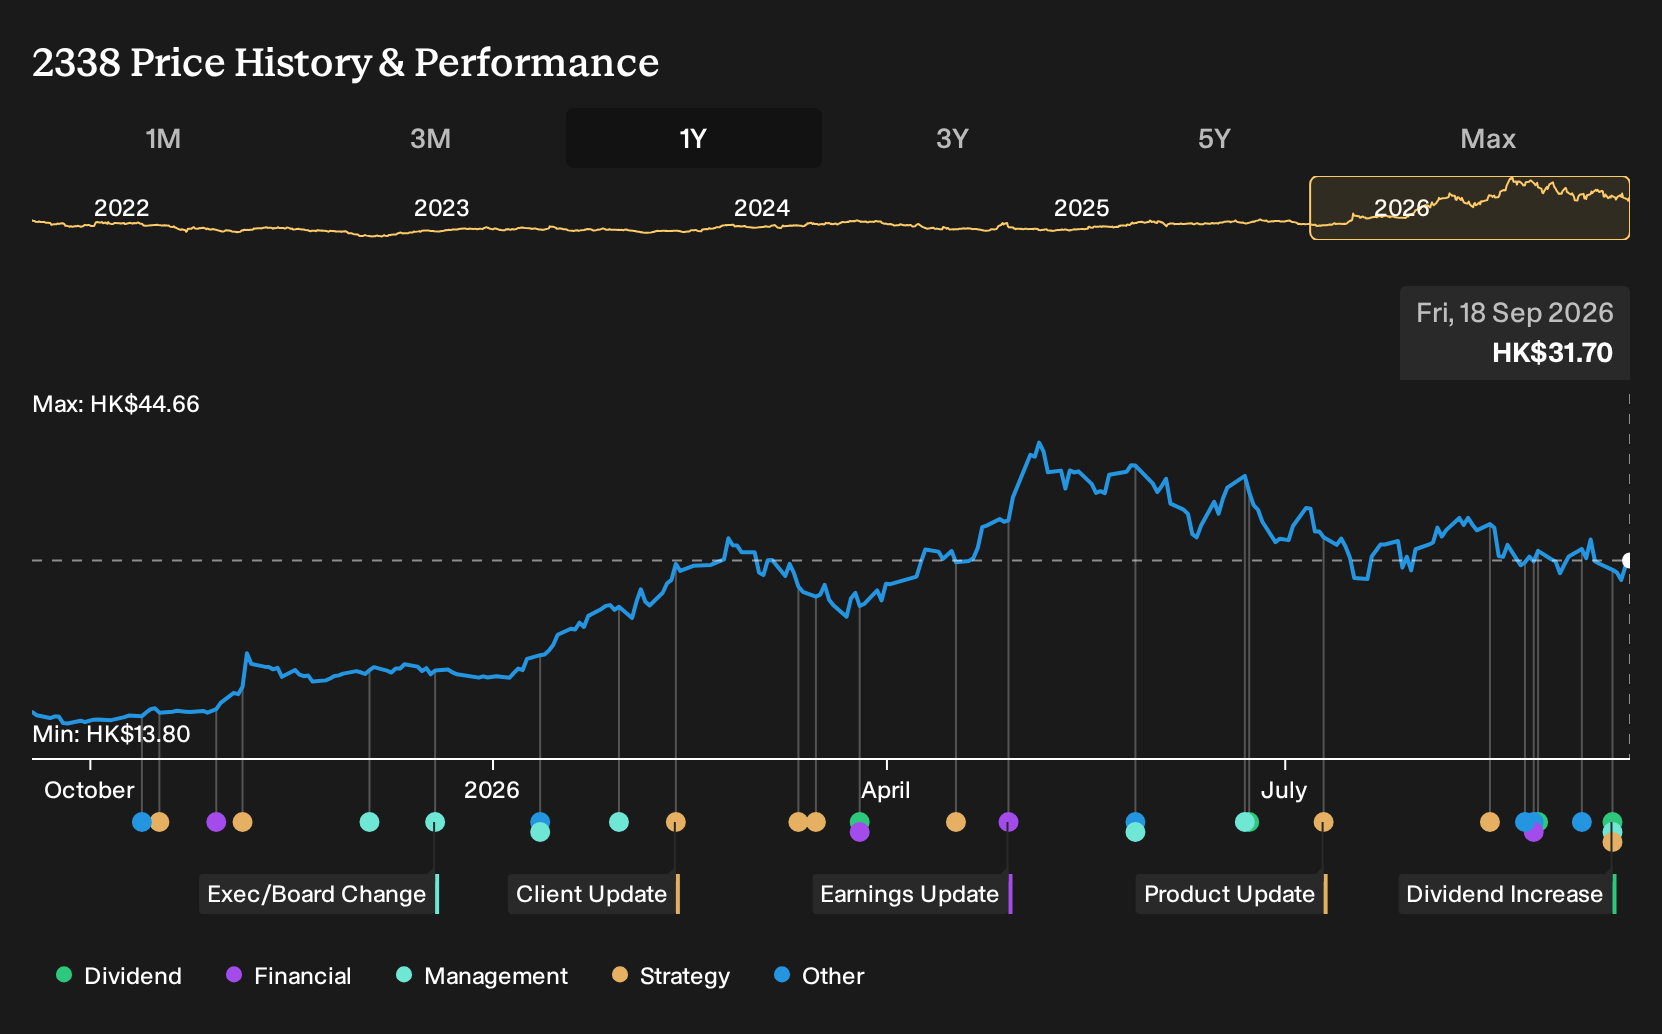
- Weichai Power approved an interim cash dividend of HK$0.5976 per H share for the six months to 30 June 2026. Shareholders also passed resolutions on revised sale caps for transactions with Shaanxi Automotive and confirmed changes to the board at the September extraordinary general meeting.
- Addition to the Hang Seng Index, combined with fresh board representation and updated related party sale arrangements, may reshape how investors view Weichai Power’s capital returns, governance structure and commercial ties with a key customer.
- The focus now turns to how Weichai Power’s Hang Seng Index inclusion might influence the broader investment narrative around earnings quality and governance.
What Is Weichai Power's Investment Narrative?
To own Weichai Power, you have to buy into a heavy machinery group that lives or dies on execution in engines, trucks, ag equipment and logistics, plus disciplined capital allocation. Earnings have been growing and net profit margins are a little higher than a year ago, yet return on equity at 12.3% is still described as low and the business is capital intensive. The fresh interim dividend of HK$0.5976 per H share and Hang Seng Index inclusion put cash returns and liquidity in focus but do not change the basic reality that profitability has to keep doing the heavy lifting.
In the short term, the dividend decision, the updated Shaanxi Automotive sale caps and the addition of Mr. Liu Yi sharpen the conversation around governance, related party exposure and board oversight at Weichai Power. Index entry can attract more institutional flows and the payout can appeal to income holders, yet the stock is flagged as having an unstable dividend record and trades on an 18x P/E against a higher internal fair value estimate. That mix keeps the main swing factors anchored in earnings delivery, capital intensity and how consistently management can convert forecast profit growth into cash.
That said, there is one pressure point in the story that tends to get ignored until you look closely at ...
There's only one way to know the right time to buy, sell or hold Weichai Power. Head to Simply Wall St's company report for the latest analysis of Weichai Power's Fair Value.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community put Weichai Power anywhere between roughly HK$47 and HK$88 per share, which is a wide span for just a pair of estimates. Those retail investors have not yet factored in the fresh interim dividend, index inclusion or new board representation, so you may want to compare several updated opinions before forming your own stance.
Explore another Weichai Power fair value estimate, including one that suggests it could be worth just HK$47.31!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Weichai Power research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weichai Power. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weichai Power's overall financial health at a glance.
Looking For More Ideas Beyond Weichai Power?
If you want to round out your watchlist beyond Weichai Power and stress test your thesis, the Simply Wall St Screener can help you quickly filter the market for different income, quality and risk profiles.
- For investors who care most about resilience and lower downside risk, consider checking out 227 resilient stocks with low risk scores which have historically scored well on stability and financial strength.
- If you want potential mispricing with solid fundamentals, scan through 179 high quality undervalued stocks which combine balance sheet support with healthy cash generation.
- Income focused readers who like the story around Weichai Power's latest payout can benchmark it against 156 dividend fortresses which keep yields and balance sheet quality front and centre.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com