
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Enlarged Notes Sale Require Action From Halozyme Therapeutics (HALO) Investors?
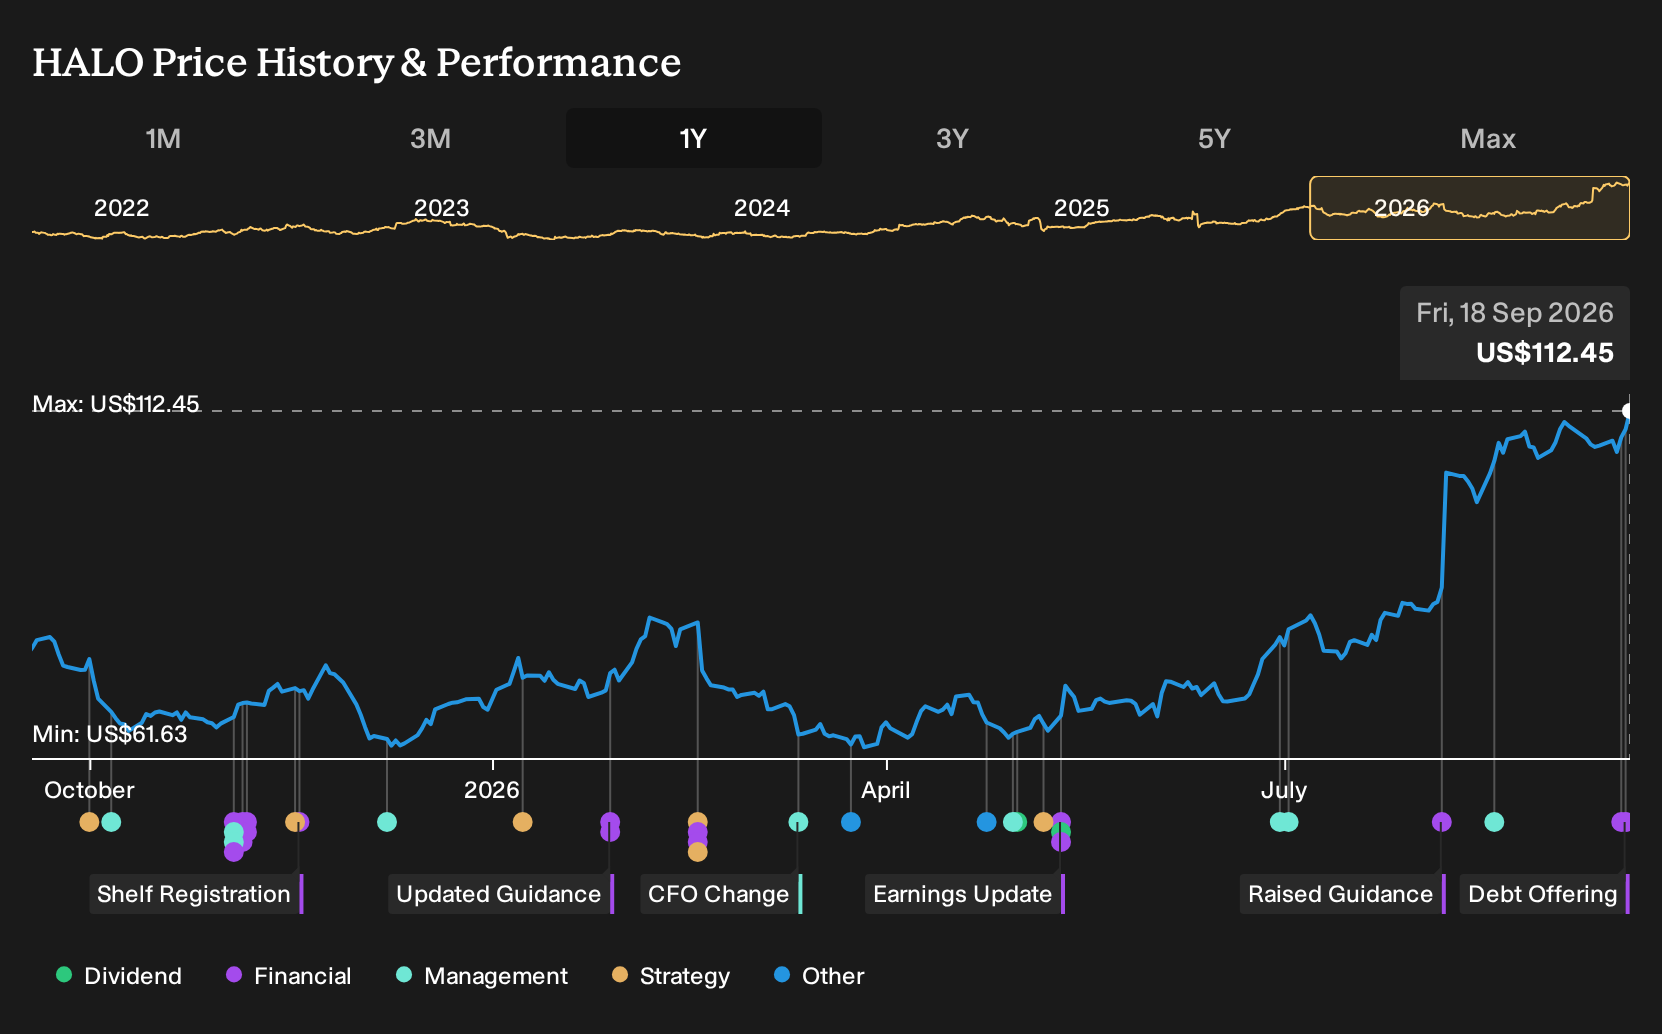
- Halozyme Therapeutics has completed a Rule 144A offering of US$1.3b in 1.50% convertible senior unsecured notes due October 1, 2033, after initially flagging a smaller US$1.05b issue and granting initial purchasers an option for an extra US$200m.
- The upsized convertible deal provides Halozyme with additional balance sheet flexibility to refinance existing convertible notes and to fund potential M&A or other corporate transactions without immediately issuing equity.
- We will now examine how Halozyme Therapeutics' enlarged 2033 convertible notes issue could reshape the broader investment narrative that investors focus on.
Halozyme Therapeutics Investment Narrative Recap
To own Halozyme Therapeutics, you need to believe the ENHANZE platform and partnered biologics can keep generating attractive royalty and product income despite regulatory pressure and payer focus on costs. The recent US$1.3b convertible notes deal does not change that core thesis. It mainly affects how the business funds that story, not the scientific or commercial engine.
In the near term, the key catalyst remains continued adoption of subcutaneous versions of partner drugs and the ramp of newer launches that use Halozyme technology. The biggest risk still sits in concentrated partner exposure and legal or reimbursement setbacks that could affect pricing or volumes. The new debt raises financial flexibility but also keeps leverage in focus.
The pricing of the US$1.3b 1.50% convertible senior notes due 2033 matters most for how Halozyme Therapeutics manages its balance sheet around that operating backdrop. Management expects part of the proceeds to go toward repurchasing existing convertible notes, which can smooth the maturity profile and reduce near term refinancing pressure if executed as outlined.
What remains for you is to judge whether this larger convertible layer supports or complicates the medium term catalyst path. A cleaner debt stack could help Halozyme stay focused on executing with partners, advancing device platforms, and responding to regulatory or IP challenges. At the same time, higher gross debt raises sensitivity to any hit in royalties if key products or geographies underperform.
Halozyme Therapeutics' narrative projects US$2.2b revenue and US$1.1b earnings by 2029. This reflects analysts' assumed 9.9% yearly revenue growth and an earnings increase of about US$686m from current earnings of US$413.6m.
Uncover why Halozyme Therapeutics' fair value indicates an 11% potential downside to its current price that leaves little room for error.
Exploring Other Perspectives
One bullish twist on Halozyme Therapeutics centers on the possibility that partner launches and at home drug delivery move much faster than the consensus view. The most optimistic analysts were already modeling about US$2.5b of revenue and US$1.4b of earnings by 2029 before this larger US$1.3b convertible financing. As this deal is digested, some of those narratives may shift, so it can be useful to compare several viewpoints before deciding how you see the trade off between growth and balance sheet risk.
Explore 3 other Halozyme Therapeutics fair value estimates, including one that suggests as much as 255% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Halozyme Therapeutics research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Halozyme Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Halozyme Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Halozyme Therapeutics?
If Halozyme Therapeutics has sharpened your thinking about risk, reward, and balance sheets, it can be useful to widen the lens and see how other companies stack up on those same dimensions. The Simply Wall St Screener lets you filter for very specific traits so you can build a watchlist that actually fits your own style and risk tolerance.
- If capital preservation sits high on your list, start with companies that score well on financial resilience by scanning a 30 resilient stocks with low risk scores that already screen strongly on stability.
- For investors who want quality but still care about price, focus on companies that mix solid fundamentals with room for the story to play out using our curated 16 high quality undiscovered gems to surface ideas that are not already crowded trades.
- If you prefer balance sheet strength as your anchor, zero in on businesses with robust finances and healthy fundamentals through a targeted list of solid balance sheet and fundamentals (23 results) that can help you build a sturdier core portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com