
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Kulicke And Soffa Industries (KLIC) Cheap As Advanced Packaging Ramps Come Into Focus?
Kulicke and Soffa Industries (KLIC) came onto investor radars after recent trading left the share price at $83.14, with short term returns mixed while longer horizons show stronger total performance.
Short term momentum for Kulicke and Soffa Industries has cooled, with the share price down 31.8% over 90 days. However, the year to date share price return of 71.9% and 1 year total shareholder return of 100.4% still point to a story that has rewarded patient holders despite recent volatility.
Scan how Kulicke and Soffa Industries compares with other semiconductor and automation plays by reviewing the hand picked 95 robotics and automation stocks in the same broader theme.
After a sharp pullback leaves Kulicke and Soffa Industries at $83.14 against analyst targets of about $106 and an implied intrinsic value far lower, which reference point really anchors fair value here?
Most Popular Narrative: 22% Undervalued
Kulicke and Soffa Industries is tracked by a widely followed narrative that pegs fair value at about $106.67, compared with the $83.14 last close. The gap between model and market is now in sharp focus for anyone weighing the recent pullback.
Management is preparing for a production ramp in Fluxless thermocompression and vertical wire into fiscal 2026, yet both are still in early phases with first HBM system shipments and initial vertical wire qualifications. Any delay or slower adoption in high bandwidth memory or on device AI could pressure the anticipated contribution to revenue growth and limit margin expansion.
See why 6 investors see Kulicke and Soffa Industries as 22% undervalued.
The same storyline leans on a discount rate of 10.85% and assumes revenue growing at about 22.8% a year with profit margins near 28.4%. Together these inputs support a fair value estimate of roughly $106.67 against the current $83.14 share price.
Result: Fair Value of $106.67 (UNDERVALUED)
Still, the Kulicke and Soffa Industries story could crack if advanced packaging ramps slip, or if power semiconductor demand in EV and industrial markets softens.
Find out about the key risks to this Kulicke and Soffa Industries narrative.
Another View: Kulicke and Soffa Industries On Earnings Multiples
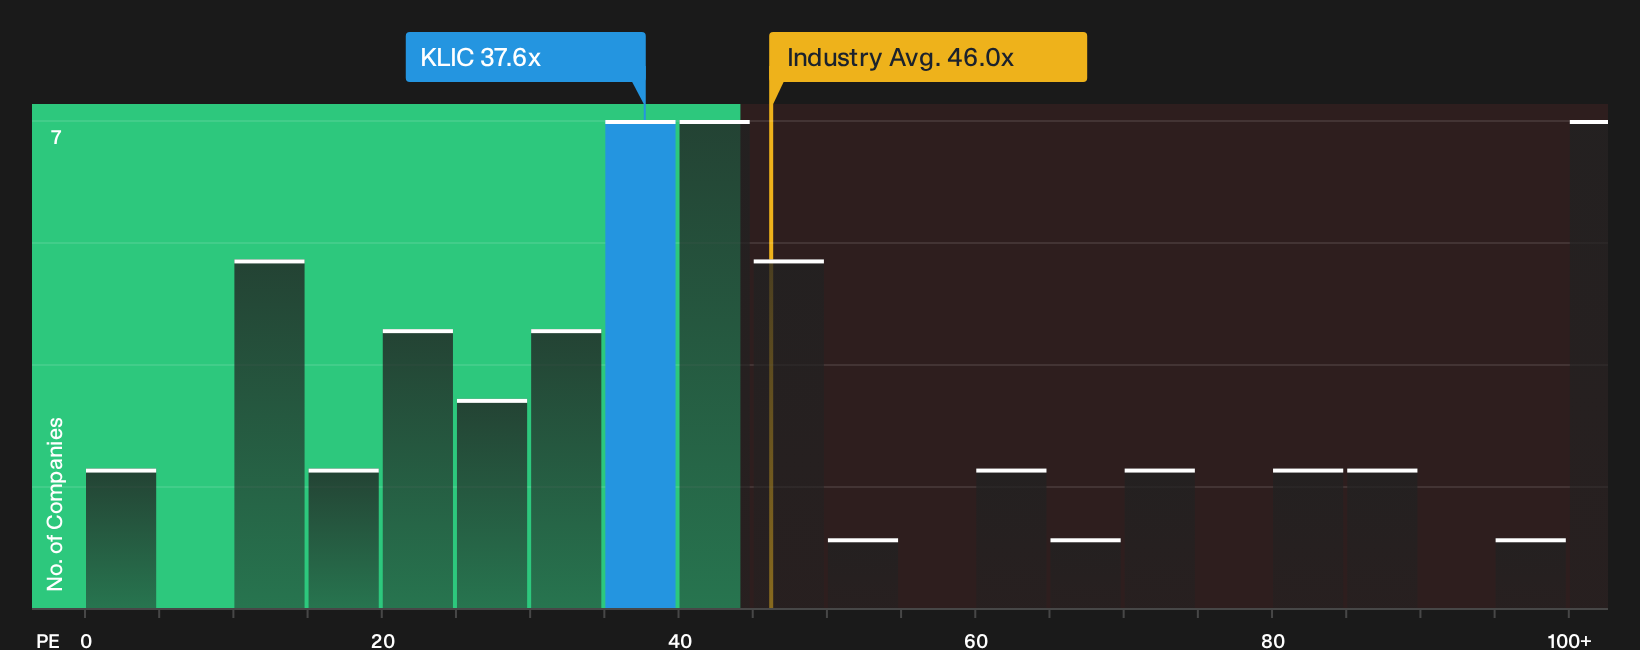
A different lens on Kulicke and Soffa Industries comes from its P/E. At 37.6x, the stock trades below the US Semiconductor average of 46x and a peer average of 53.7x, yet above a fair ratio of 34.9x. That mix hints at quality, but also some valuation risk. Which side matters more to you?
See what the numbers say about this price by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
For a clearer sense of how Kulicke and Soffa Industries stacks up against its sector on earnings, focus on the relative P/E levels shown in
Next Steps
Mixed signals around Kulicke and Soffa Industries can be confusing. Move quickly, compare the data yourself, and pressure test both the positive and negative angles using the 4 key rewards and 1 important warning sign.
Looking for more Kulicke and Soffa Industries investment ideas?
If Kulicke and Soffa Industries has your attention, do not stop here. Fresh ideas often come from comparing it with very different opportunities uncovered in the screener.
- Target reliable income streams by scanning companies that qualify as 6 dividend fortresses and see which payouts align with your return expectations.
- Hunt for potential bargains by reviewing a 33 high quality undervalued stocks that combine solid fundamentals with prices that differ from intrinsic value estimates.
- Stack your watchlist with durable businesses using a 30 resilient stocks with low risk scores so you are not caught off guard when conditions change.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com