
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Apple Cider Recall Could Be A Big Test For Weis Markets Stock
- Weis Markets has initiated a voluntary recall of its Fresh From the Orchard pasteurized apple cider in multiple plastic jug sizes after the FDA reported high patulin levels in products distributed in Pennsylvania, with several pull dates in July, August and September 2026 affected and the action currently classified as an ongoing Class II recall.
- The recall points to potential pressure on Weis Markets from product disposal costs, quality control remediation and short term disruption to cider sales volumes where the affected items were stocked.
- This recall, which is tied to high patulin levels, could influence how investors view Weis Markets' broader investment narrative and risk profile.
What Is Weis Markets' Investment Narrative?
To own Weis Markets, you have to believe in a fairly simple story. A regional grocer with US$5.1b in sales that tries to turn a thin 2% net margin into consistent cash, pay a 1.88% dividend and avoid big capital surprises. The voluntary cider recall fits into that picture as an operational and brand test. The affected product sits in one state and a specific category, so the recall looks more like a quality control bump than a shift in core demand or pricing power across the store base.
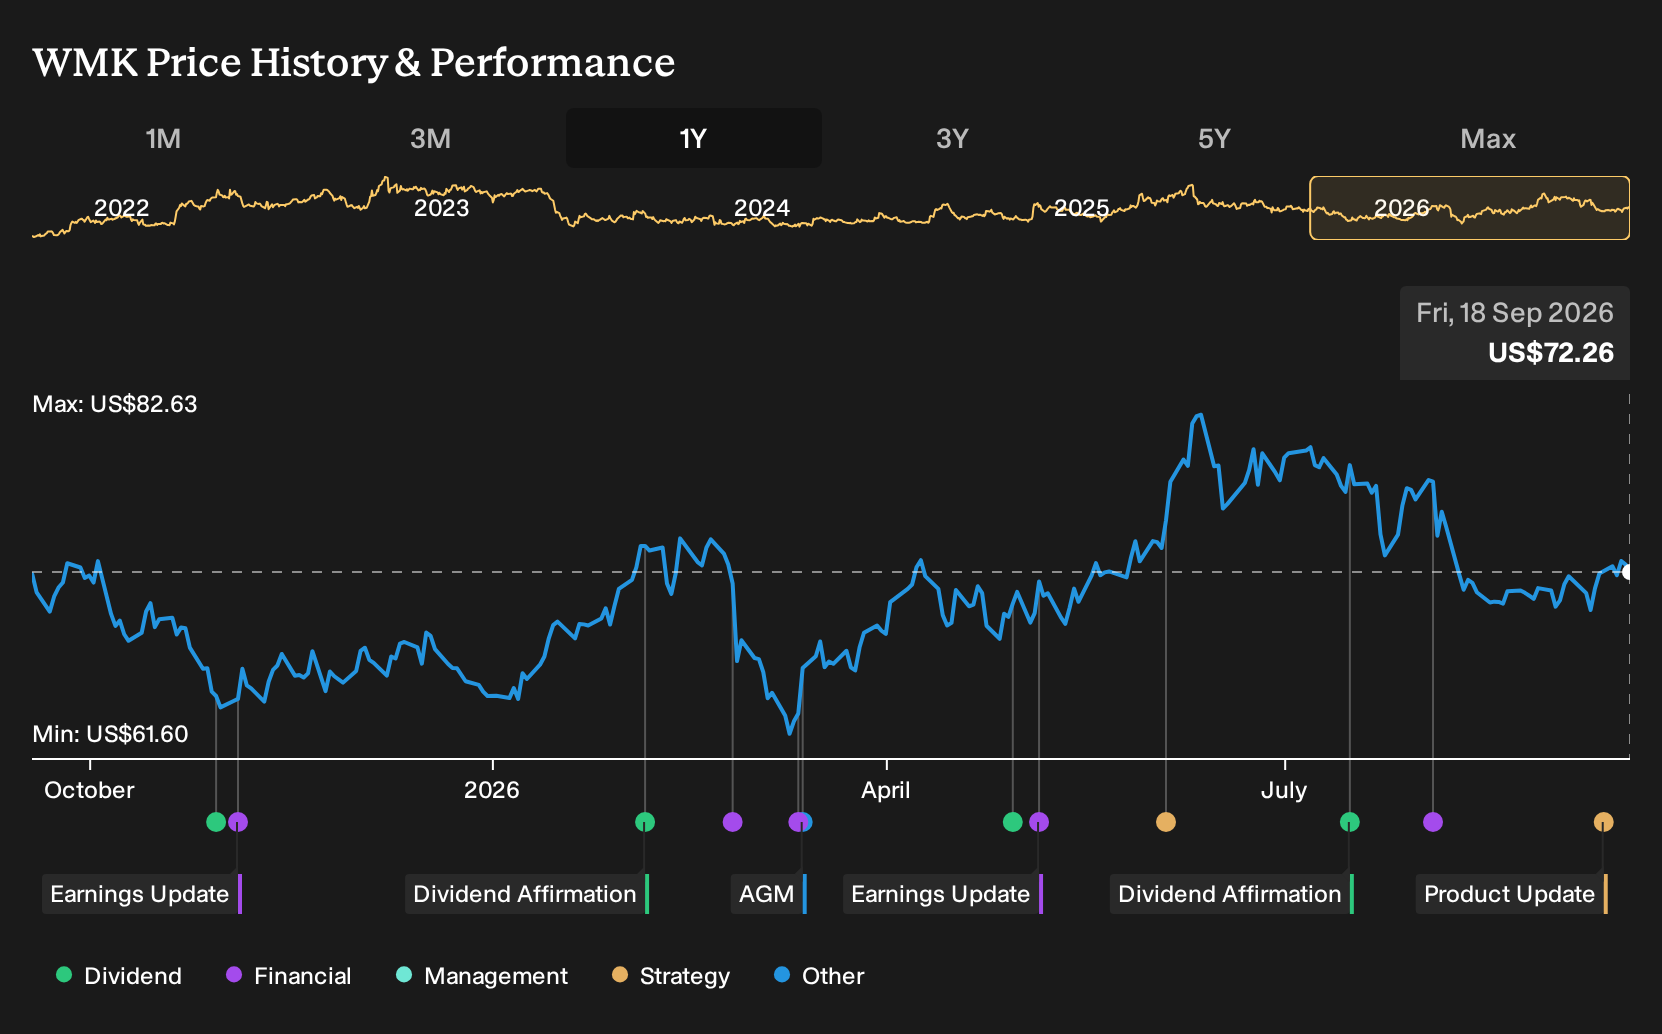
In the near term, the real swing factors still look more basic. Can Weis Markets keep traffic and basket size healthy while earnings have already declined 3.9% per year over five years and net margins slipped from 2.1% to 2%? Recently, WMK shares are up 12.7% year to date but down 5.8% over 3 months, with the stock trading on an 18x P/E and flagged as 61.3% below one DCF estimate. That combination of perceived value and modest return on equity of 7.2% works only if you are comfortable that quality issues like this recall do not point to a deeper execution problem.
That said, the longer you study Weis Markets, the harder it is to ignore...
There's only one way to know the right time to buy, sell or hold Weis Markets. Head to Simply Wall St's company report for the latest analysis of Weis Markets's Fair Value.
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and using your judgement.
- A great starting point for your Weis Markets research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weis Markets. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weis Markets' overall financial health at a glance.
Looking For More Investment Ideas Beyond Weis Markets?
If this recall has you rethinking concentration risk around Weis Markets, it can help to widen the lens and compare it with other businesses that fit different quality, income and valuation profiles.
- For investors who want potential upside with strict risk filters, review a 8 elite penny stocks with strong financials that screens for smaller companies meeting specific financial criteria.
- If capital preservation and balance sheet strength matter most to you, focus on a list of solid balance sheet and fundamentals (23 results) that can surface businesses with stronger financial footing than Weis Markets.
- Those seeking mispriced opportunities can scan a 33 high quality undervalued stocks that highlights stocks where fundamentals and market pricing look out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com