
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
National Vision Holdings (EYE) Slides 11%, Is It Still 52% Undervalued?
National Vision Holdings (EYE) has drawn fresh attention after recent trading left the stock down about 11% over the past month while remaining roughly flat over the past three months.
For context, National Vision Holdings shares are trading at US$16.88, and the stock has slipped about 11% on a 30 day share price return, while the year to date share price return is down roughly 35%. This signals fading near term momentum even though the three year total shareholder return is still positive and the five year total shareholder return has declined sharply.
Compare National Vision Holdings with a curated group of retail healthcare peers by scanning the list of solid balance sheet and fundamentals (23 results) that have been filtered for sturdier fundamentals and financial resilience.
National Vision Holdings just dropped sharply, yet it still trades at roughly the same level as three months ago. Does that set up a reasonable entry today, or argue for patience and a lower price later?
Most Popular Narrative: 52% Undervalued
Against a last close of $16.88, the most followed narrative sees National Vision Holdings trading well below a fair value estimate of $35.00, with that gap hinging on how effectively the business can turn modernization and tele-optometry into durable earnings power using a 9.29% discount rate.
While analysts broadly agree that omnichannel investments and digital personalization will incrementally improve retention and efficiency, the combination of a powerful new CRM platform, data-driven segmentation, and targeted digital campaigns is set to sharply expand market share among higher-income, insurance-backed consumers, potentially driving a step-change in lifetime customer value, store productivity, and gross margin expansion.
See why 0 investors see National Vision Holdings as 52% undervalued.
Result: Fair Value of $35.00 (UNDERVALUED)
Still, the bullish fair value story for National Vision Holdings leans heavily on execution, while rising labor costs and online competition could easily weaken that thesis.
Find out about the key risks to this National Vision Holdings narrative.
Another View: National Vision Holdings Through Earnings Multiples
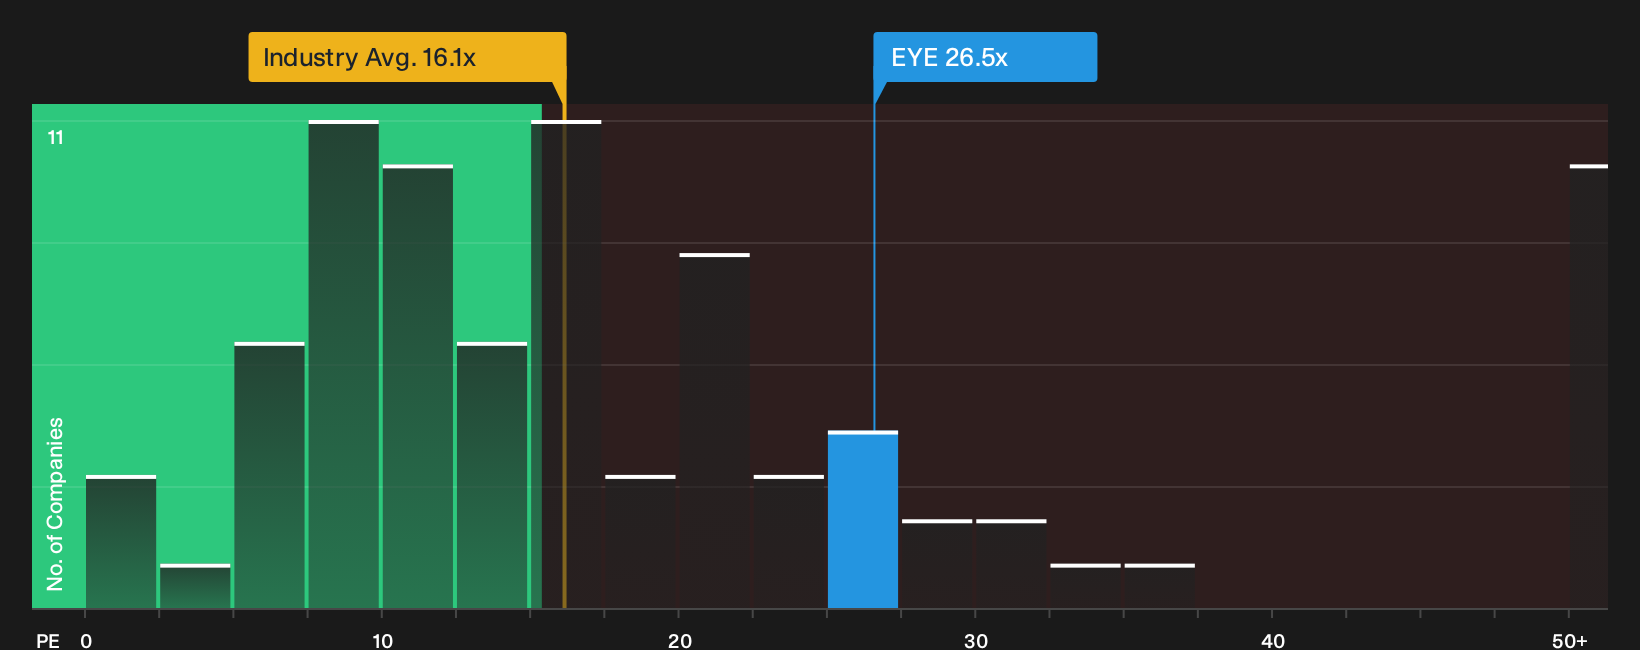
The fair value story for National Vision Holdings changes once earnings multiples enter the frame. The stock trades on a P/E of 26.5x compared with 16.1x for the US Specialty Retail industry and a fair ratio of 19.1x, which points to a richer price tag and less margin for error if bullish forecasts slip.
For investors weighing that richer multiple against the optimistic fair value work, it can help to see how the numbers stack up in detail, including peers and the fair ratio path the market could move toward over time: See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals or quiet opportunity? If the National Vision Holdings story appears divided between risk and potential upside, move quickly and evaluate the upside case for yourself with 3 key rewards.
Looking for more investment ideas beyond National Vision Holdings?
You have a clear picture of National Vision Holdings. Now widen your opportunity set and put a few focused screeners to work for your portfolio.
- Target rock solid balance sheets and steadier fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results).
- Hunt for quality at a potential discount by scanning the 33 high quality undervalued stocks before prices move away from you.
- Spot resilient businesses with gentler risk profiles by checking the 30 resilient stocks with low risk scores while these ideas are still under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com