
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Oriental Land (TSE:4661) Could Be 6% Undervalued On Fantasy Springs Optimism
Oriental Land (TSE:4661) has drawn fresh attention after recent share price moves, with the stock up about 5% over the past month and roughly 30% across the past 3 months.
That recent momentum comes after a mixed stretch for Oriental Land, with a 30-day share price return of 4.75% and a 90-day gain of 29.9% contrasting with a 1-year total shareholder return that declined 14.18%. As a result, short-term enthusiasm sits against weaker longer-run outcomes.
Scan how Oriental Land's recent swings compare with 17 high quality undervalued stocks that the market may not be fully pricing yet.
For Oriental Land, that combination of a sharp recent rebound and weaker long term returns raises a simple puzzle. Are investors now paying for improving fundamentals, or simply reacting to a change in sentiment around the stock?
Most Popular Narrative: 6% Undervalued
On the widely followed narrative, Oriental Land's fair value sits at ¥3,236 per share, compared with a last close of ¥3,035. That gap is modest and it frames the recent share price rebound as investors weighing long term earnings power against a still cautious one year return profile.
The opening of Fantasy Springs and new attractions has increased guest attendance, which is expected to boost net sales and operating profit through higher theme park revenues. Merchandise and food and beverage sales are projected to grow due to new product offerings and the opening of new restaurants in Fantasy Springs, positively impacting net sales per guest and overall revenue.
See why 1 investors see Oriental Land as 6% undervalued.
Result: Fair Value of ¥3,236 (UNDERVALUED)
Still, the narrative around Oriental Land can be knocked off course if higher personnel and raw material costs squeeze profitability, or if guest spending momentum fades faster than expected.
Find out about the key risks to this Oriental Land narrative.
Another View On Oriental Land’s Valuation
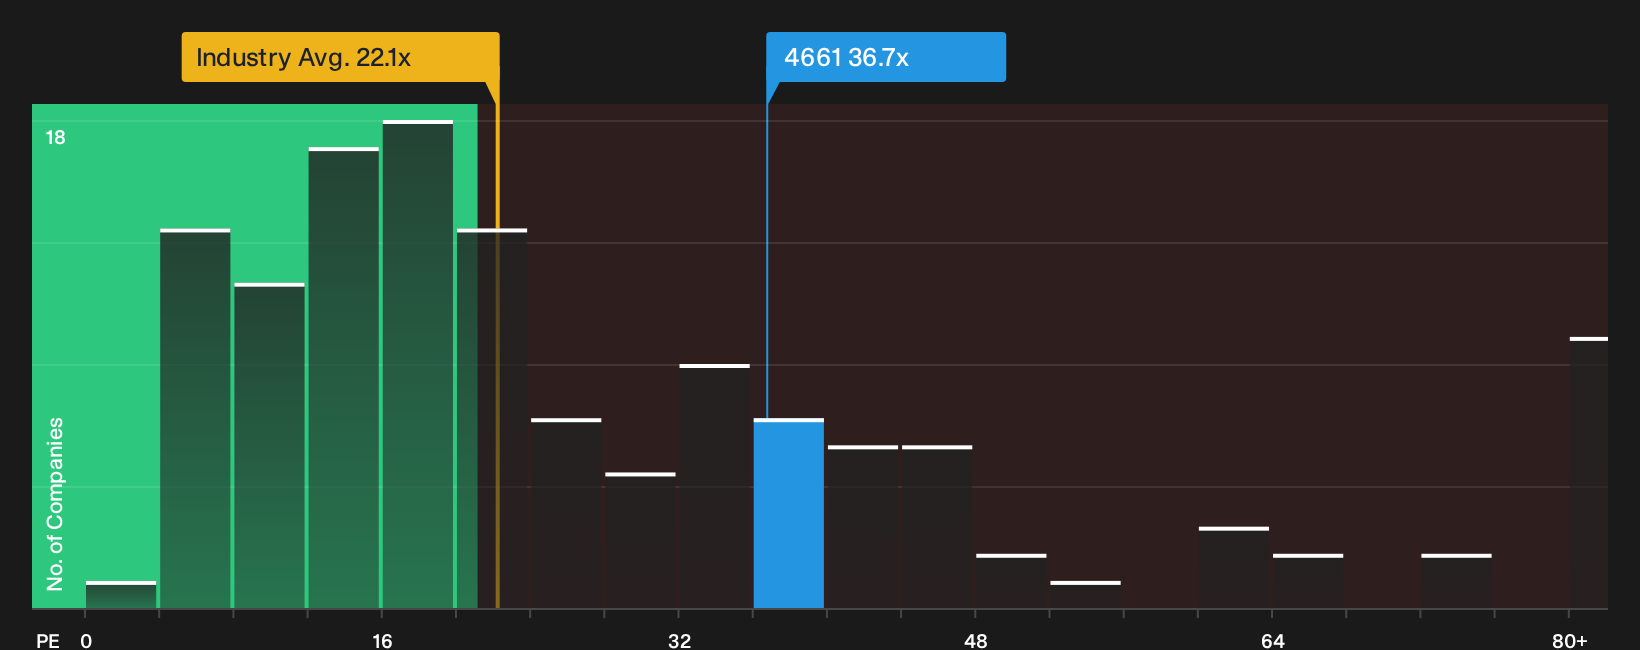
On a simple earnings multiple, Oriental Land looks expensive. The shares trade on a P/E of 36.7x, while the JP Hospitality group averages 22.1x and the fair ratio for this stock is flagged at 28.8x. That gap points to valuation risk if sentiment cools.
Investors weighing this richer earnings multiple against the earlier fair value narrative may want to stress test what would need to go right for the market to keep paying up at this level, and whether a move toward the fair ratio is a risk worth taking on.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the cautious tone or the optimism around Oriental Land feels more convincing to you. Take a few minutes to review the underlying metrics and stress test your own thesis, then deepen that view by looking through the 2 key rewards.
Looking for more investment ideas beyond Oriental Land?
Do not stop your review with a single stock. The same questions you are asking of Oriental Land can reveal other opportunities that fit your style and risk tolerance.
- Target income first and scan for businesses that could help support a cash flow focused approach through the 14 dividend fortresses.
- Hunt for resilient balance sheets and reduce the chance of unpleasant financial surprises by reviewing the list of solid balance sheet and fundamentals (20 results).
- Pursue potential mispriced opportunities early by running through the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com