
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To KLA (KLAC) AI Chip Demand Outlook
- KLA is seeing rising demand for its AI-focused process control tools as chipmakers invest in 2 nm, EUV, HBM and advanced packaging, supported by a backlog that management expects at about $12.5b, providing improved visibility into late 2026 and 2027.
- Fresh research comparing KLA with Daktronics highlights that, despite both carrying similar earnings-focused rankings, investors are weighing KLA's larger exposure to tariffs and weaker China demand against momentum in AI-driven process control and sector-wide semiconductor ETF strength.
- We will now look at how KLA's investment narrative is influenced by stronger AI process-control demand and broad semiconductor sector strength.
Compare how other AI infrastructure plays stack up against KLA by reviewing the hand-picked 89 AI infrastructure stocks, which is now moving in line with this chip and process-control momentum.
KLA Investment Narrative Recap
To own KLA, you need to believe process control remains critical for every step up in AI, 2 nm, EUV and advanced packaging. The business currently leans on a large backlog that management expects at about US$12.5b, which helps visibility into late 2026 and 2027 but does not completely insulate it from order swings.
The key near term swing factor is how quickly AI focused investments in logic, foundry, HBM and packaging keep translating into tool demand. The biggest risk remains pressure from tariffs and softer China demand, which could weigh on margins and growth, although today’s AI driven sector strength does not materially change that risk profile yet.
The most relevant piece of recent context is the Zacks work comparing KLA with Daktronics. Both sit in a similar earnings focused ranking, yet Daktronics screens as the cheaper value play, while KLA is framed as about 27% undervalued on a fair value view with tariff and China exposure still hanging over the story.
For you, that frames KLA as an AI infrastructure and process control pure play. The market already prices it at a premium P/E, with analysts still seeing upside and earnings growth forecasts around 19% a year. The operational question is whether KLA converts its backlog, AI tailwinds and sector ETF strength into durable orders fast enough to offset those external cost and demand pressures.
KLA's narrative projects US$21.3b revenue and US$8.8b earnings by 2029. That path assumes 17.6% yearly revenue growth and an earnings increase of about US$4.1b from US$4.7b today.
Uncover why KLA's fair value indicates a 31% potential upside to its current price, a discount that could close faster than many investors expect.
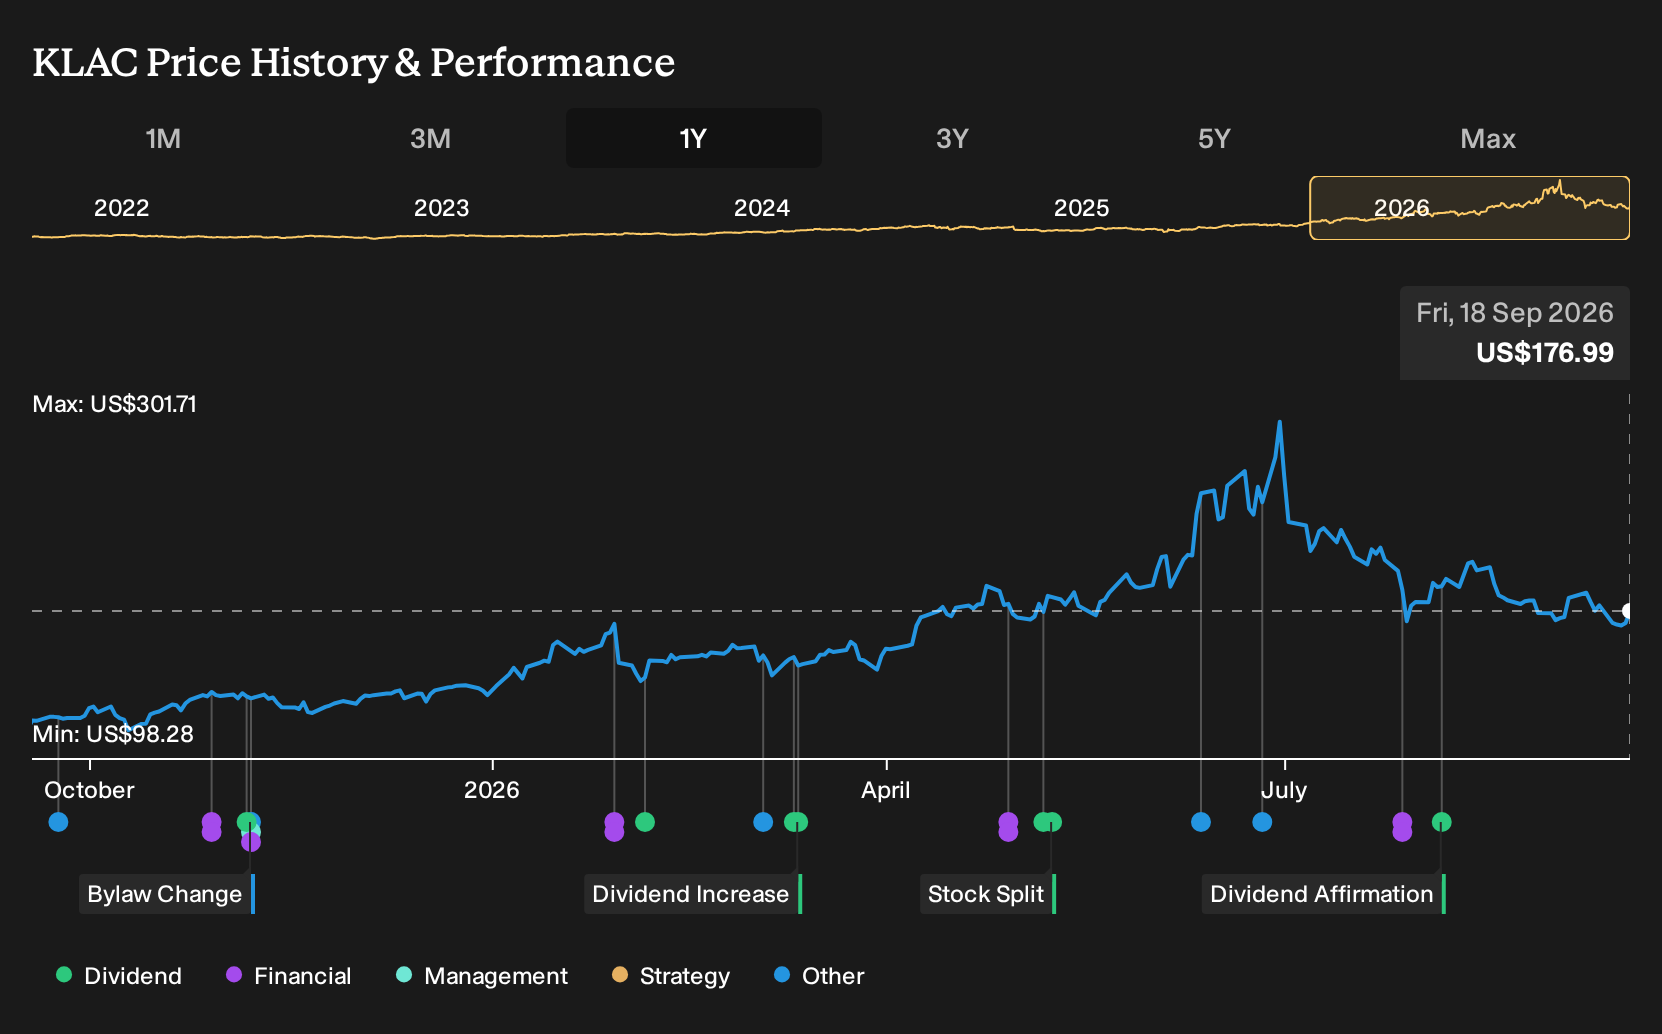
Exploring Other Perspectives
One alternative view on KLA leans hard into advanced packaging as the real swing factor. The most bullish analysts were penciling in revenue reaching about US$26.1b and earnings near US$11.1b by 2029, before this latest AI driven move in chip stocks. Those forecasts could shift, up or down, as today’s news gets absorbed.
Explore 5 other KLA fair value estimates, including one that suggests as much as 71% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your KLA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for KLA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate KLA's overall financial health at a glance.
Looking for more investment ideas beyond KLA?
If KLA has sharpened your thinking about AI infrastructure and process control, it can be useful to line that thesis up against other companies that share similar financial traits or risk profiles. The Simply Wall St Screener lets you move from a single stock story to a wider watchlist that matches your own criteria on quality, balance sheet strength and income potential.
- For investors who want potential mispricings with quality fundamentals, start by reviewing a focused set of 16 high quality undiscovered gems that might not yet be widely followed.
- If resilience and capital preservation sit at the top of your checklist, narrow your search to a 30 resilient stocks with low risk scores that prioritizes stronger financial health and lower risk scores.
- Income focused investors can filter for payouts that matter by scanning a curated pool of 6 dividend fortresses that meet a yield hurdle of more than 5%.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com