
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How KDDX Destroyer Contract Will Impact Leonardo DRS (DRS) Stock
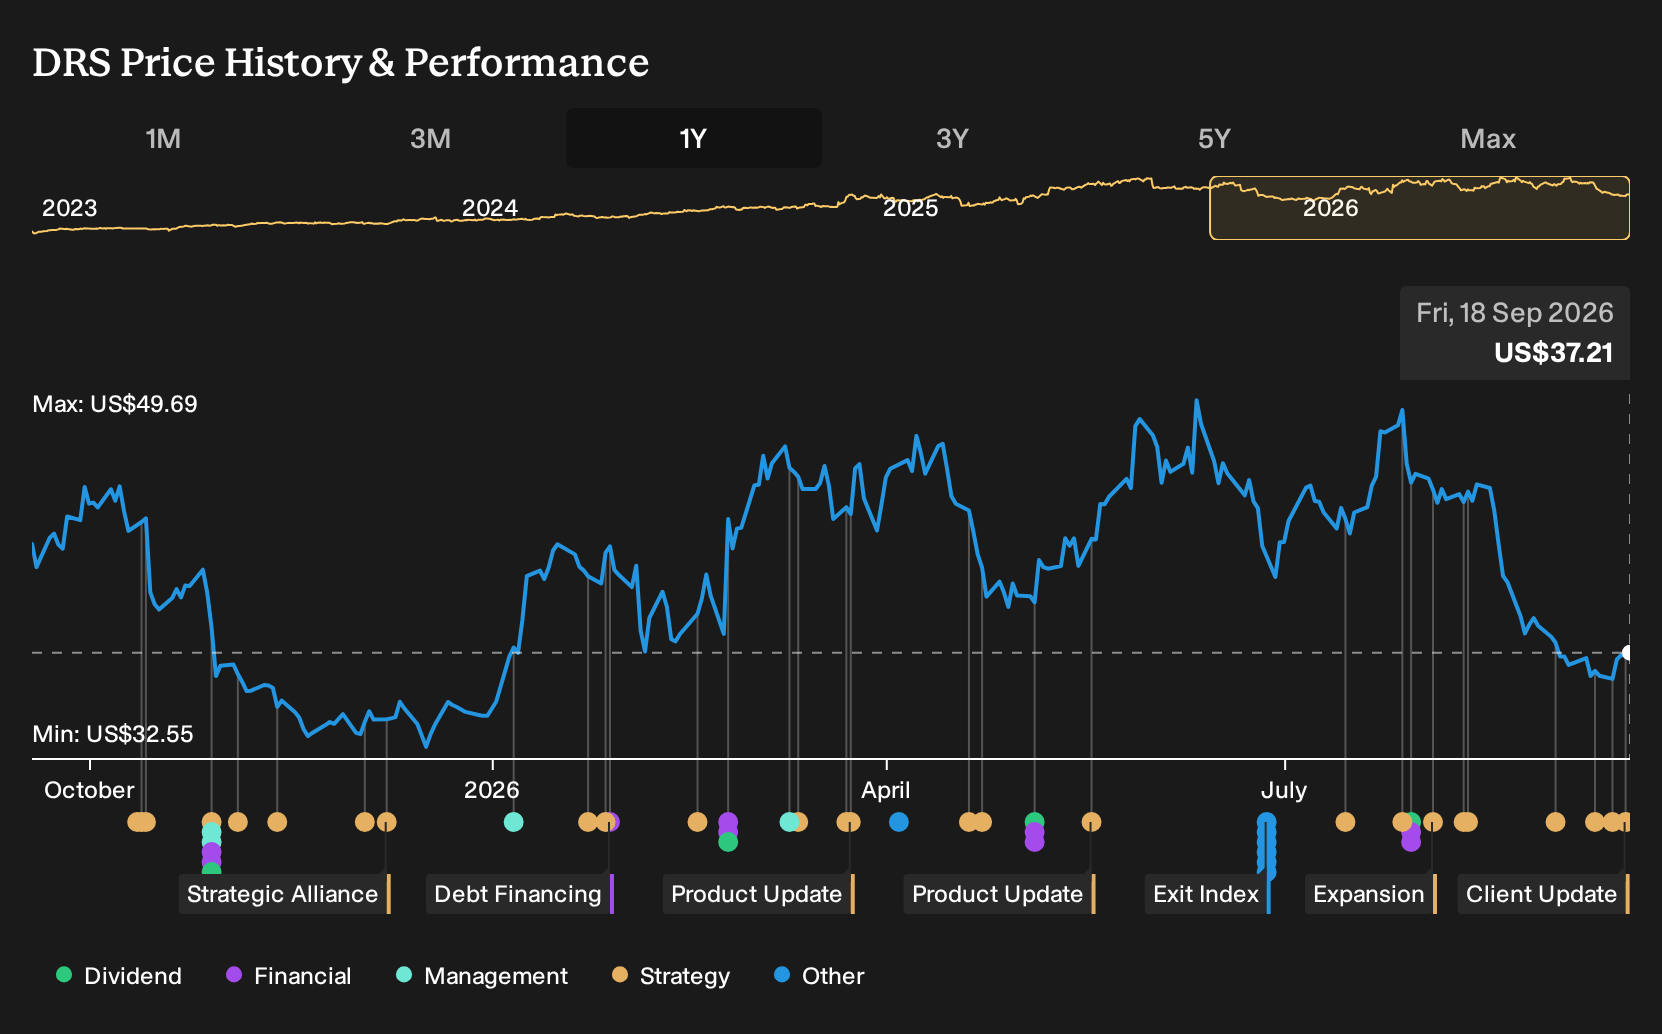
- Leonardo DRS reported in mid September 2026 that it will supply integrated electric power and propulsion systems for the Republic of Korea Navy's KDDX destroyer class through a contract with Doosan Enerbility, using its 100 Series permanent magnet motors and compact variable frequency drives.
- The KDDX award adds another complex naval program to Leonardo DRS's backlog, reinforcing its role in electric propulsion where size, weight, and efficiency constraints directly shape platform design choices for allied fleets.
- We will now look at how Leonardo DRS's investment narrative is affected by this KDDX electric propulsion win with Doosan Enerbility.
Scan the defense sector for other contractors building momentum around electric propulsion and advanced naval systems by reviewing the 38 power grid technology and infrastructure stocks alongside Leonardo DRS' KDDX win.
Leonardo DRS Investment Narrative Recap
To own Leonardo DRS, you need to believe in a defense electronics supplier that leans into long duration programs in naval power, sensing, computing, and electric propulsion. The KDDX propulsion award fits that story by adding an international, next generation surface combatant to the Integrated Mission Systems backlog, but it does not fundamentally change the short term picture.
The near term swing factor still looks tied to execution on existing U.S. and allied contracts while managing raw material costs and higher R&D spending. The biggest risk remains margin pressure from input costs, including germanium, and from R&D intensity that might not convert into follow on wins or higher margin programs.
The September contract for Joint Tactical Terminal Transceiver units on EA 18G aircraft links tightly to the KDDX narrative. Both point to Leonardo DRS supplying core electronics where customers want modular, upgradeable hardware that can plug into evolving communications, sensing, or power architectures without redesigning the entire platform.
For you as a shareholder, that pairing reinforces the operational theme of content per platform across air, sea, and computing rather than a single program bet. It also concentrates execution risk around delivering complex gear on time and on spec, since delays or cost overruns on tightly defined firm fixed price contracts can affect margins more quickly than volume growth helps.
Leonardo DRS' analyst narrative points to revenues of US$4.6b and earnings of US$463.4m by 2029, based on a 7.0% yearly revenue growth rate and a move in profit margins from 8.5% today to 10.0%. That path implies earnings rising by about US$141.4m from current earnings of US$322.0m to the forecast consensus level, with the forecast estimate year again anchored in 2029.
Uncover why Leonardo DRS' fair value indicates a 45% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on ESG risk rather than contract wins. Under that lens, even before this KDDX news, the most cautious analysts were working off revenue expectations of about US$4.4b and earnings around US$531.6m by 2029. That group also anchored on a much lower P/E, which shows how far opinions on Leonardo DRS can spread. You can use this KDDX contract as a fresh data point and decide which story feels closer to your own assessment.
Explore 4 other Leonardo DRS fair value estimates, including one that suggests as much as 15% downside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Leonardo DRS research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Leonardo DRS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Leonardo DRS' overall financial health at a glance.
Looking For More Investment Ideas Beyond Leonardo DRS?
Once you have formed a view on Leonardo DRS, it can help to compare that thesis with other businesses that share similar quality, income, or risk characteristics. The Simply Wall St Screener lets you filter for exactly what you care about and then track those opportunities as new information lands.
- If you want income to do more of the heavy lifting in your returns, review a curated set of higher yielding stocks through the 6 dividend fortresses.
- For investors who care most about resilience and balance sheet strength, start with the list of solid balance sheet and fundamentals (23 results) to see which companies clear those hurdles.
- If you are hunting for ideas that the market may not be fully focused on yet, scan the 16 high quality undiscovered gems and see which stories deserve a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com