
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Missed Billings Require Action From BlackLine (BL) Investors?
- BlackLine reported year-on-year revenue growth of 9.2% in its latest results but missed billings estimates and confirmed the loss of a customer, contributing to a mixed operational picture for its finance automation platform.
- The contrast between rising sales and softer billings, alongside customer churn, highlights execution pressure on BlackLine's shift toward larger, more complex enterprise relationships.
- We will now explore how this softer billings performance reshapes BlackLine's investment narrative and what it may mean for investors.
Scan beyond BlackLine and compare how other finance and back-office software players are executing by reviewing the hand-picked list of solid balance sheet and fundamentals (23 results) in this space.
BlackLine Investment Narrative Recap
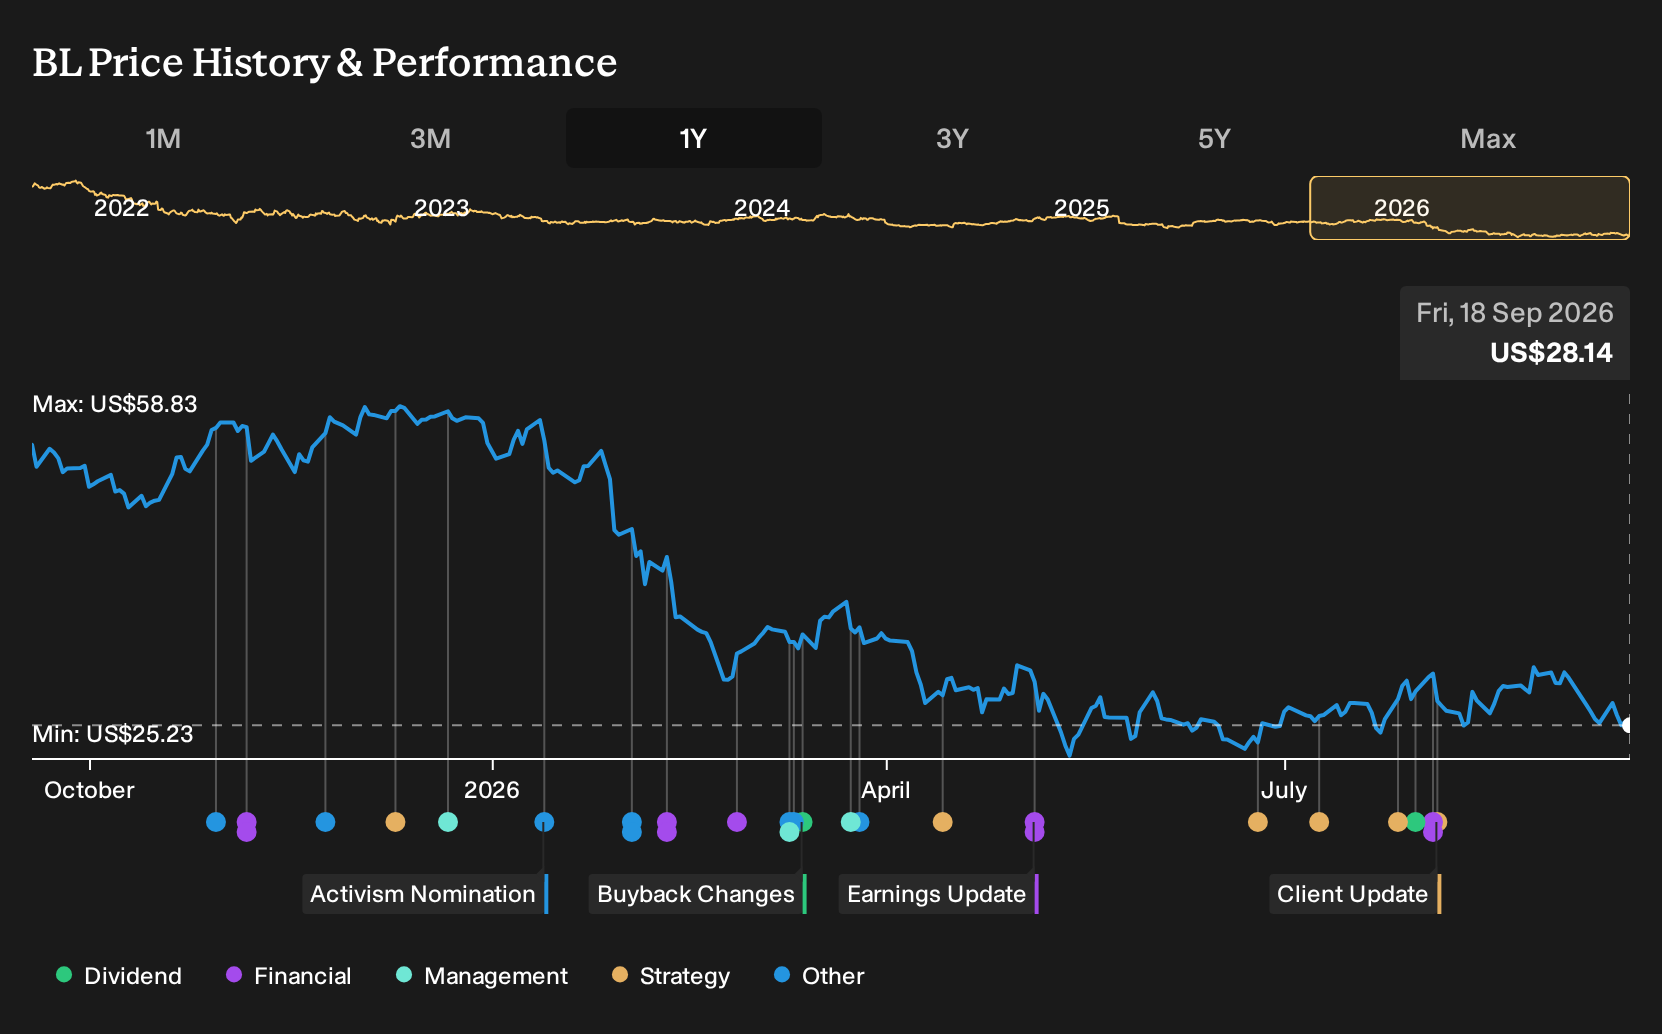
To own BlackLine, you need to believe finance teams keep shifting more of the close, intercompany, and accounts receivable stack into purpose-built cloud tools rather than relying only on ERP extensions or manual work. The recent 9.2% revenue growth supports that basic adoption story, although the stock’s 14.1% slide since results shows how sensitive sentiment is to execution.
Right now, the short term catalyst is pretty simple. Management needs to show that the move toward larger enterprise relationships translates into steadier billings and cleaner renewals after this weaker print and customer loss. The main risk is that modest top line guidance, slower deal closures, and rising competition from large ERP vendors keep billings choppy.
There were no fresh headline announcements tied directly to this quarter, so the most relevant information for you today is still the existing growth plan for BlackLine’s Studio360 platform, AI and analytics features, and deeper integrations with SAP, Snowflake, and Oracle. That is where management hopes to support bigger contracts and more embedded workflows.
In that context, the billings miss matters. It raises the bar for proving that a richer product set and value based, unlimited user pricing can offset deal delays, customer churn, and pressure from integrated suites. Your call is whether current execution bumps look like friction inside a still intact cloud finance automation story or early signs of the risks around competition and slower revenue playing out.
BlackLine's current consensus narrative points to revenues of US$1.0b and earnings of US$168.4m by 2029, based on analysts assuming 11.9% yearly revenue growth and earnings rising by roughly US$133.6m from US$34.8m today.
Uncover how BlackLine's fair value indicates a 38% potential upside to its current price, before short term execution questions fade from the spotlight.
Exploring Other Perspectives
For a very different angle on BlackLine, some of the most optimistic analysts were penciling in about 12.1% annual revenue growth and earnings of roughly US$160.0m by 2029 before this billings miss. Those expectations assume faster AI driven sales cycles. You can compare that upbeat view with today’s news and decide whether it still holds.
Explore another BlackLine fair value estimate, including one that suggests as much as 310% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your BlackLine research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BlackLine. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BlackLine's overall financial health at a glance.
Looking For More Investment Ideas Beyond BlackLine?
If you want to stress test your view on BlackLine, one effective way is to compare it with other stocks that have different balance sheet profiles, income streams, and risk levels using the Simply Wall St Screener.
- If capital preservation sits high on your list, compare BlackLine with 30 resilient stocks with low risk scores that score well on both resilience and downside protection.
- If you are hunting for mispriced quality, line up BlackLine against 33 high quality undervalued stocks that pair stronger fundamentals with what our models view as discounted prices.
- If you prefer to get in early before wider attention builds, contrast BlackLine with 16 high quality undiscovered gems that already show solid fundamentals but attract less market focus.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com