
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Higher ETF Assets Will Impact Victory Capital Holdings (VCTR) Investors
- Victory Capital Holdings reported that assets under management reached $356.469b at the end of August, compared with $345.117b at the end of July, while ETF assets were $23.474b versus $20.889b.
- The roughly $2.585b increase in ETF assets concentrates more of Victory Capital Holdings’ fee base in products that can often scale without matching cost increases.
- We will now look at how Victory Capital Holdings’ investment narrative could be affected by August’s sharp increase in ETF assets.
Scan other asset managers showing similar fee-scale potential by reviewing the hand picked 33 high quality undervalued stocks, which may also be leaning into scalable products like ETFs.
Victory Capital Holdings Investment Narrative Recap
To own Victory Capital Holdings, you need to believe the firm can grow assets faster than outflows while keeping fee pressure and costs contained. The August move in assets under management, including ETFs, ties directly to that story. It reinforces the idea that more of the franchise can be supported on the existing operating platform if scale holds.
In the near term, the key catalyst is whether higher assets under management start to show up as stronger earnings in a backdrop of fee compression. The biggest risk is that client withdrawals and lower realized fees outpace asset gathering, which would leave higher headline AUM numbers with less impact on revenue and margins.
Recent commentary around expense synergies from the Amundi and Pioneer integration is especially relevant here. Management has already identified US$70m in savings, with another US$40m targeted over about 15 months. That kind of efficiency work matters more when total assets, including ETFs, move higher.
For you as a shareholder, the combination of August ETF growth and these integration efforts ties directly into the core thesis. The story relies on Victory Capital Holdings using its broadened international distribution, product mix and technology to support more assets without a similar rise in costs, while still managing M&A and regulatory complexity as ongoing execution risks.
Victory Capital Holdings’ current analyst narrative points to revenues of US$1.9b and earnings of US$1.0b by 2029, based on assumed yearly revenue growth of 6.6% and an earnings increase of about US$644.5m from current earnings of US$355.5m.
Uncover why Victory Capital Holdings' fair value indicates a 4% potential upside to its current price that could narrow quickly.
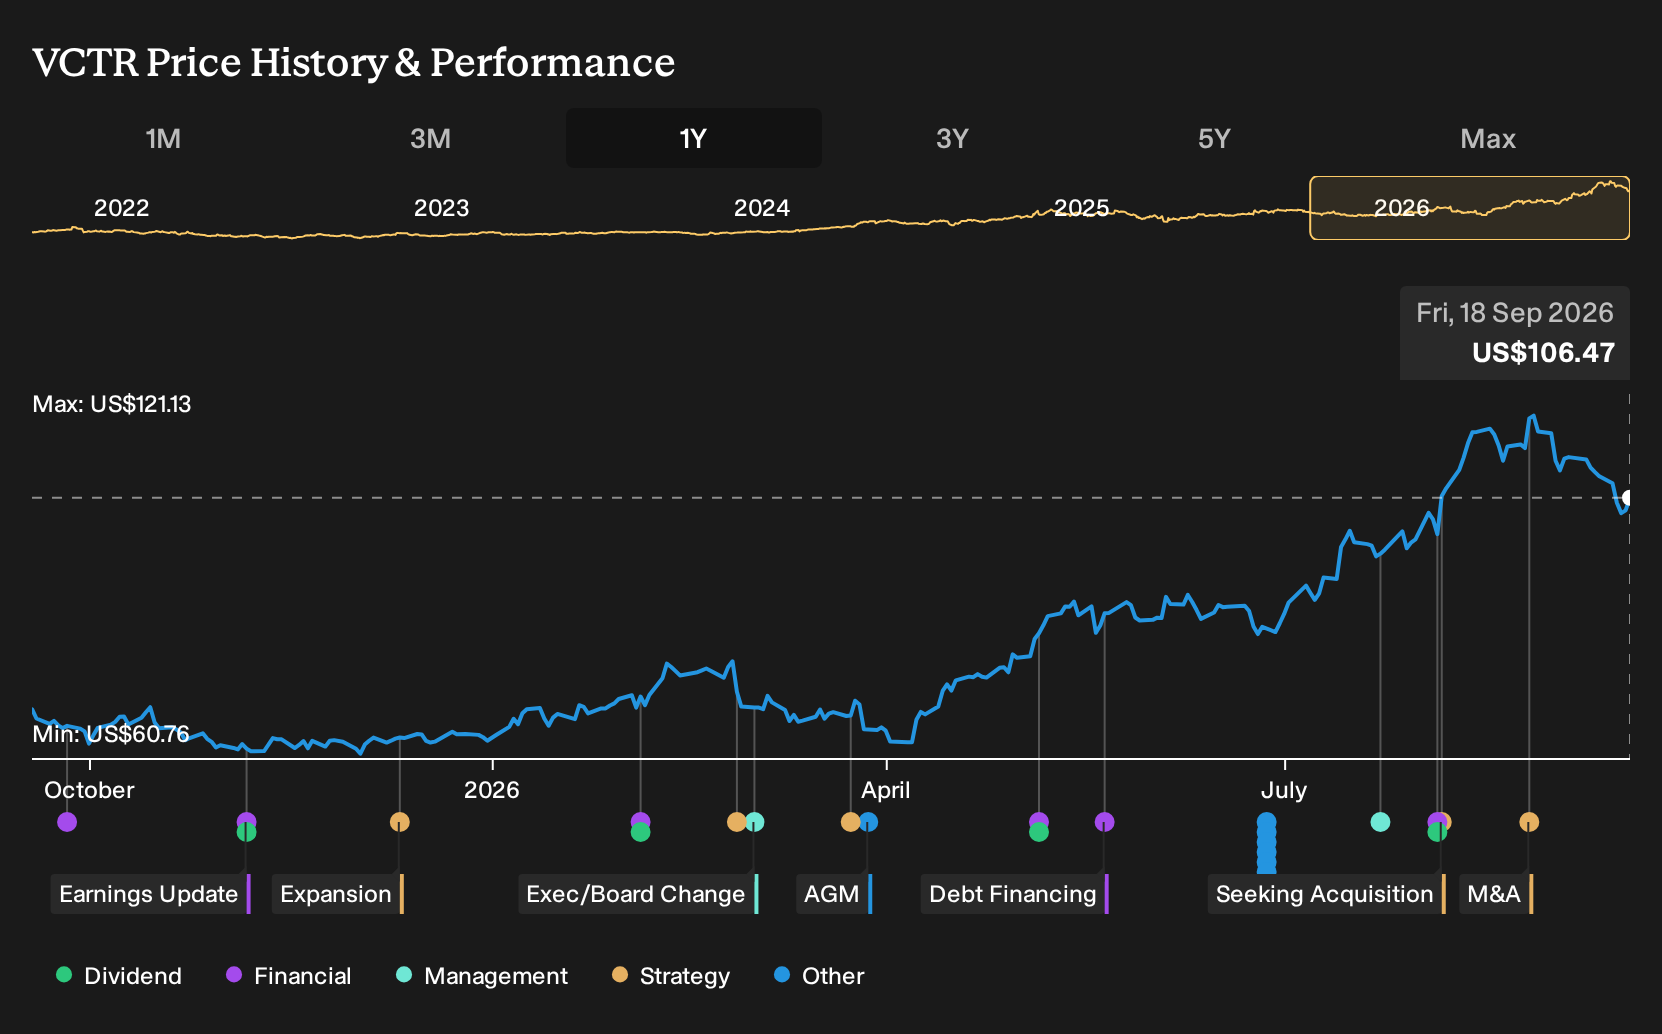
Exploring Other Perspectives
You are seeing one very optimistic angle on Victory Capital Holdings. The most bullish analysts focus on ETF scale as the big swing factor, arguing that faster ETF traction could support about US$2.0b of revenue and US$1.0b of earnings by 2029. Those projections came before this ETF AUM jump, so viewpoints may shift from here.
Explore another Victory Capital Holdings fair value estimate, including one estimate that suggests it could be worth as much as $110.33.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Victory Capital Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Victory Capital Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Victory Capital Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Victory Capital Holdings?
If the Victory Capital Holdings story has sharpened your appetite for fee-scale opportunities and strong fundamentals, it can help to line it up against a wider watchlist built with the Simply Wall St Screener.
- For investors who care most about quality at a sensible entry point, scan a curated set of companies trading below their estimated worth using the 33 high quality undervalued stocks.
- If resilience and balance sheet strength sit at the top of your checklist, filter for businesses with low leverage and solid financial footing through the list of solid balance sheet and fundamentals (23 results).
- For those who prefer a calmer ride with fewer red flags, narrow your universe to businesses with sturdier risk profiles by reviewing the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com