
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Higher Earnings Estimates Change Vestis (VSTS) Stock Narrative
- Vestis Corporation has seen analyst expectations for its full year earnings move higher in recent months, with the Zacks Consensus Estimate rising 18.3% and the stock categorized at a Zacks Rank of #2, which reflects a favorable earnings outlook based on current projections.
- The scale of the revision in profit forecasts suggests analysts view Vestis' efforts in pricing, technology upgrades, and operational execution as materially influencing its earnings power, rather than the move being driven only by short term sentiment.
- We will now look at how Vestis' higher full year earnings estimates could reshape its investment narrative for long term investors.
Vestis Investment Narrative Recap
For you to back Vestis today, you generally need to believe the uniform rental model can translate into steadier earnings as pricing, technology, and route efficiency work their way through the system. The recent 106.5% year to date share gain and higher full year earnings expectations spotlight that execution story, but do not remove the heavy lifting around customer retention and mix.
In the near term, the key swing factor is whether value based pricing and service improvements show up in cleaner margins without pushing more customers away. The biggest risk remains a mix of customer churn, high leverage of more than US$1.3b, and interest costs that are not well covered by current earnings.
The most relevant recent development for this story is the 18.3% lift in the Zacks full year earnings estimate. This ties directly to how the market reads Vestis’ operational progress and lines up with management’s focus on value based pricing, technology upgrades, and tighter cost control as the main levers for improving profitability from today’s modest earnings base.
For you as an investor, the key question is whether that improved outlook is sustainable while the business addresses churn, product mix pressure, and leverage. If execution on digital infrastructure, route optimization, and working capital discipline continues to move in the right direction, the recent earnings revision becomes less about sentiment and more about measured progress against those operational catalysts.
Vestis' analyst narrative points to revenues of US$2.8b and earnings of US$176.3 million by 2029, based on forecast revenue growth of 1.3% per year and an earnings swing of about US$181.6 million from a current earnings loss of US$5.3 million.
Uncover why Vestis' fair value indicates a 6% potential downside to its current price, which leaves little room for error.
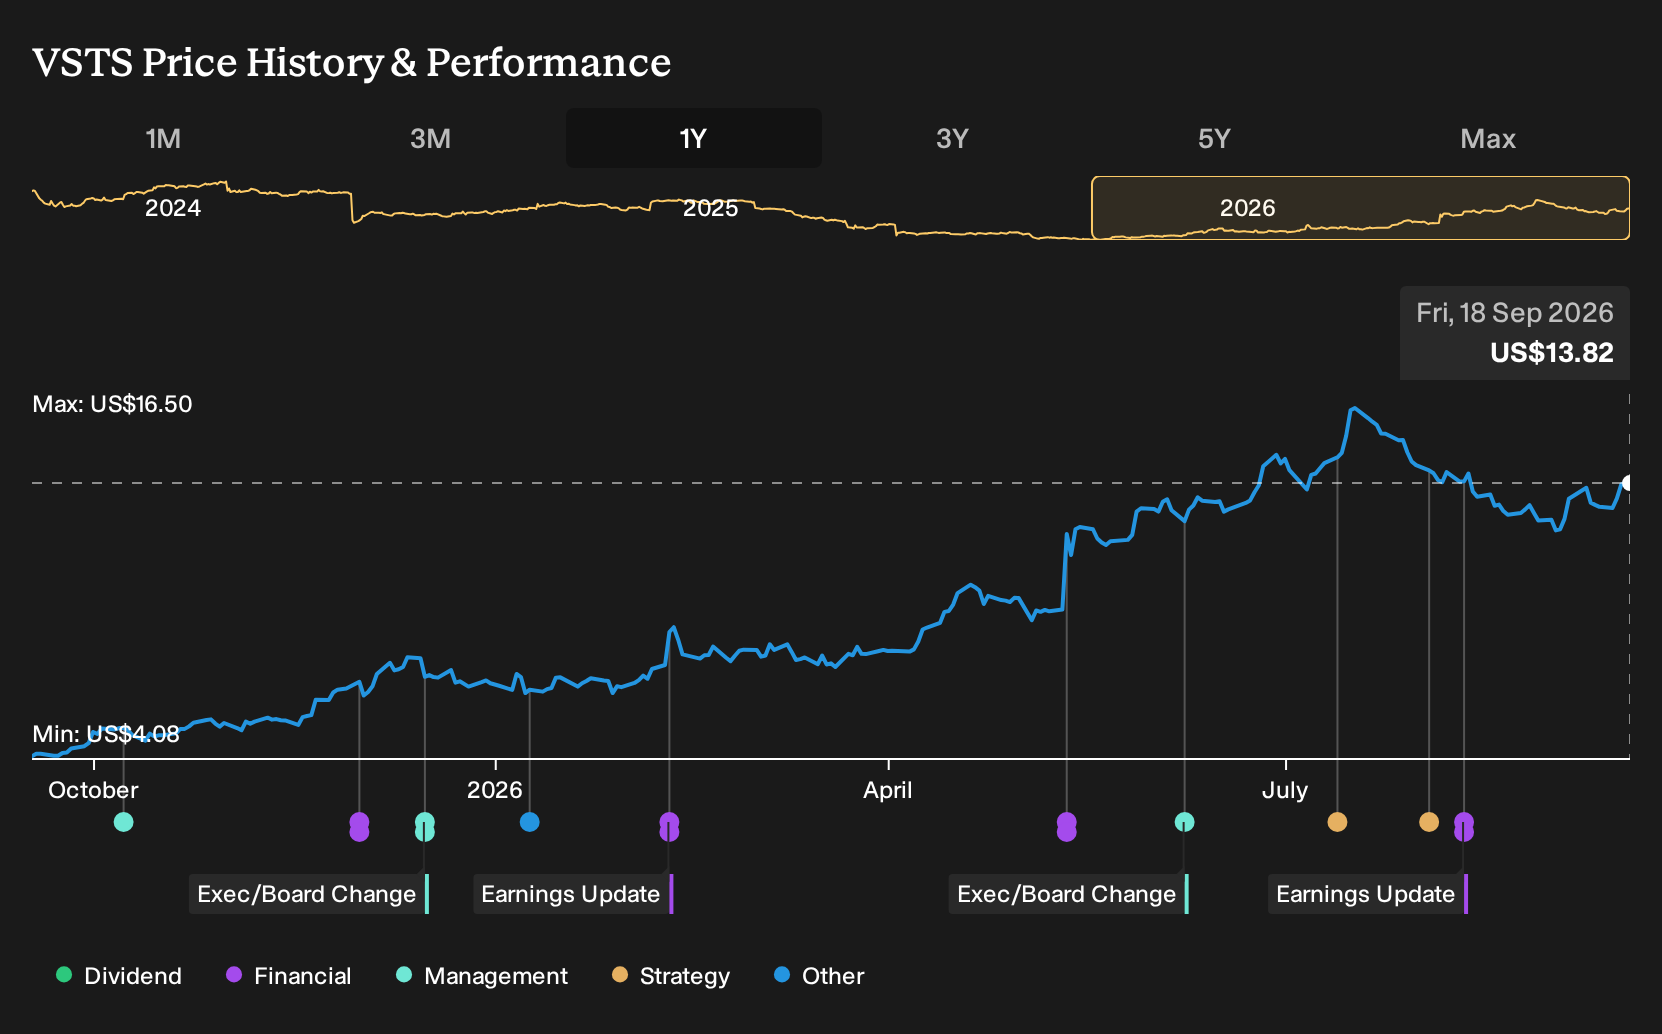
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into hygiene and sustainability as a catalyst for Vestis, arguing that recurring demand from these themes could justify revenue of about US$2.9b and earnings of roughly US$132.4 million by 2029, compared with earlier expectations closer to US$2.8b and US$176.3 million. These views were set before this earnings revision, so treat them as a starting point and assess where you agree and where you disagree.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vestis research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vestis. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vestis' overall financial health at a glance.
Looking for more investment ideas beyond Vestis?
If the Vestis story has you thinking about where else earnings revisions or balance sheet strength might be quietly reshaping the risk and reward profile, it can help to widen the lens and scan for other companies that fit your preferred criteria using the Simply Wall St Screener.
- If capital preservation sits high on your list, focus on companies that pair resilience with lower risk using the 30 resilient stocks with low risk scores to see which stocks currently screen well on stability.
- For readers who care most about financial robustness, filter for businesses with cleaner leverage and stronger fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) to spot potential candidates.
- Income oriented investors who want yield and durability together can zero in on payout strength by checking the 6 dividend fortresses that highlights companies offering higher dividends with a focus on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com