
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Gold Stocks With Profit Margins Up To 33%
Global markets are wrestling with higher interest rates, and the Federal Reserve has just nudged borrowing costs up again, which often pressures highly leveraged businesses. Low cost gold producers with strong balance sheets can look relatively resilient when money becomes more expensive. This article walks through three potential standouts from a select group of high quality gold miners and explains what makes them worth a closer look now.
The stocks covered below are only a sample, and the full Elite Gold Stocks screen surfaced 33 more producers with equally compelling balance sheets and cost profiles that are not included in this article.
If you want to identify, compare, and analyze the highest conviction gold miners in one place, head straight into the Elite Gold Stocks screener.
Newmont (NEM)
Overview: Newmont is a global gold producer focused on large, primary gold mines such as Carlin, Boddington and Éléonore, with additional exposure to copper and other metals.
Operations: Revenue is concentrated in large mining hubs, led by NGM at US$4.4b, Boddington at US$2.5b, Peñasquito at US$3.7b and Yanacocha at US$2.3b.
Market Cap: US$130.2b
Newmont matters for this Elite Gold Stocks screen because its big, low cost gold mines provide exposure to bullion prices while still aiming to keep the balance sheet on solid footing.
"Persistent global inflation and monetary debasement are likely to reinforce investor and central bank demand for gold, which will support higher sustained gold prices and directly increase Newmont's future revenues and earnings."
What really moves the needle for Newmont now is how one unseen pressure on its cost base ultimately shapes future profitability and cash returns.
That hidden cost pressure is exactly what the full narrative for Newmont unpacks, revealing how it could be masking upside for Newmont if conditions turn in its favor.

AngloGold Ashanti (AU)
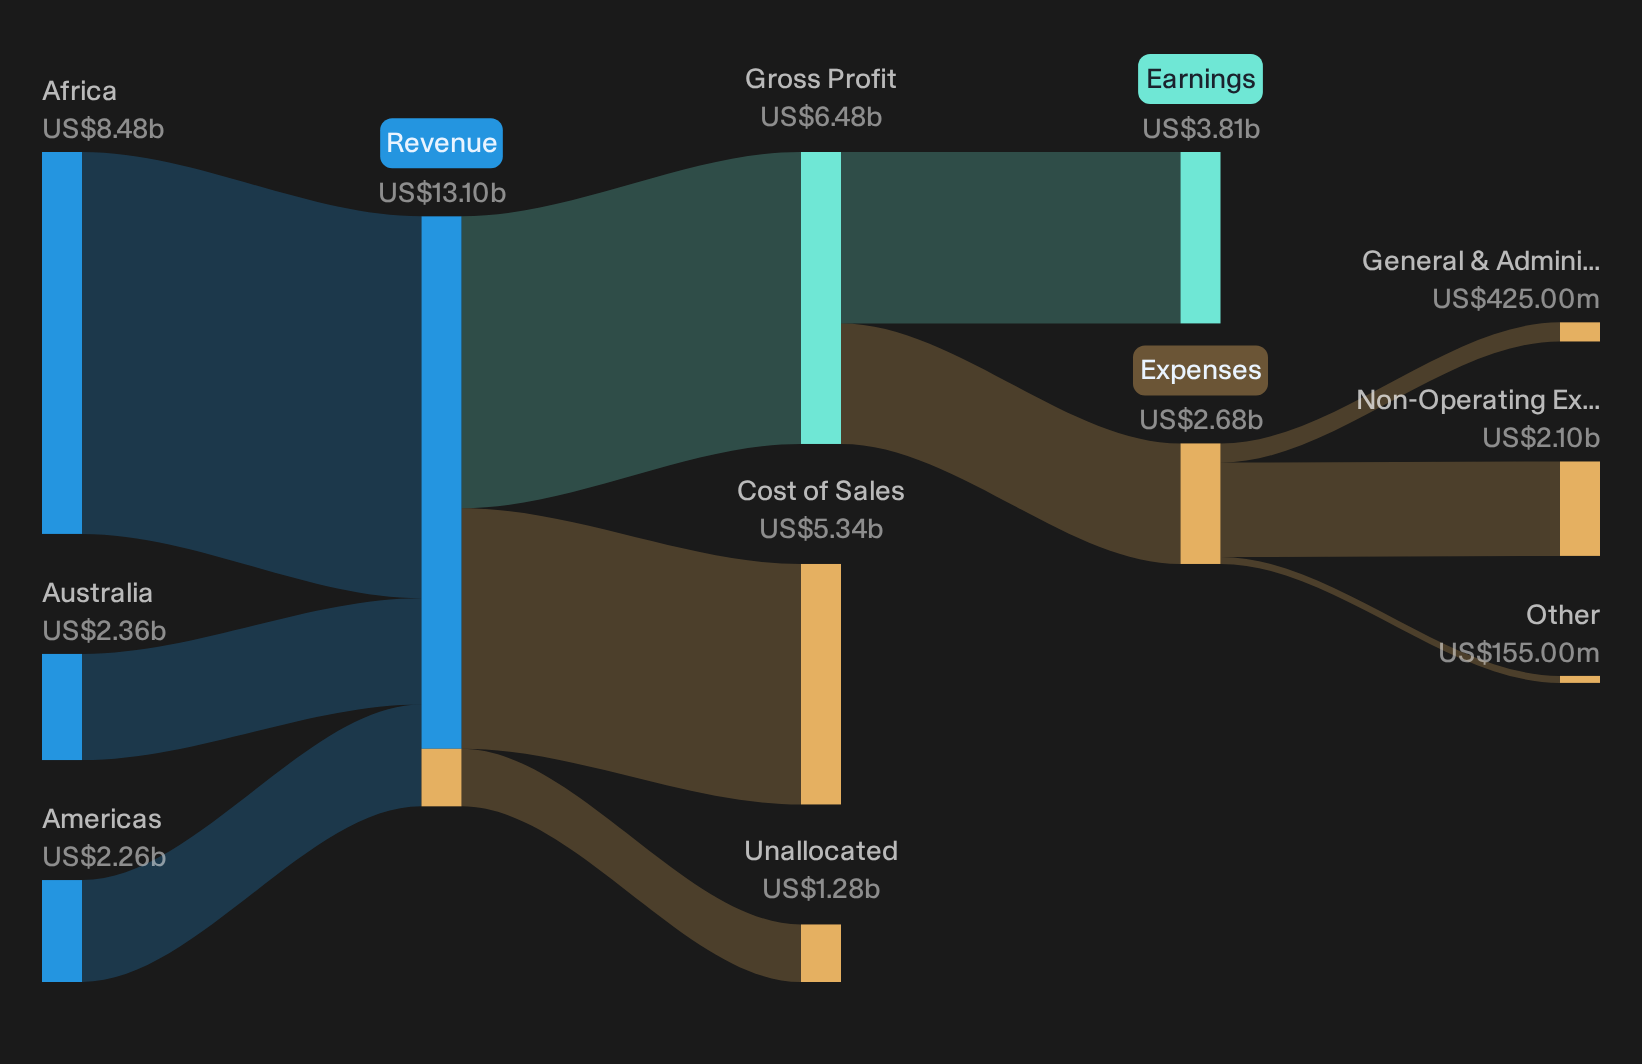
Overview: AngloGold Ashanti is a global gold producer, anchored by the Geita mine in Tanzania, with additional operations across Africa, Australia and the Americas.
Operations: AngloGold Ashanti generates US$11.8b from gold and other precious metals, led by Africa at US$8.5b, with Australia and the Americas contributing smaller shares.
Market Cap: US$52.2b
AngloGold Ashanti fits the Elite Gold Stocks theme through its large scale gold output and flagship Geita operation, which together link low cost production potential with meaningful exposure to bullion prices.
"⚠️ Cost structure above industry average"
What really matters now is how one pressure on AngloGold Ashanti’s cost base ultimately shapes the gap between revenue strength and long term margins.
That cost pressure is only one piece of the story, and the full narrative for AngloGold Ashanti shows how AngloGold Ashanti could still see margins accelerate if conditions shift in its favor.
Coeur Mining (CDE)
Overview: Coeur Mining is a Chicago based producer that focuses on gold and silver output from mines across the United States, Mexico and Canada.
Operations: Coeur Mining generates most of its US$3.2b segment revenue from Las Chispas at US$641 million and Palmarejo at US$612 million, with Rochester, Kensington and Wharf contributing meaningful additional volumes.
Market Cap: US$20.5b
For the Elite Gold Stocks screen, Coeur Mining matters because its portfolio of producing gold mines provides direct operational leverage to bullion prices, while by product metals help support the cost profile across cycles.
"The successful ramp-up and integration of the Rochester expansion and Las Chispas asset are driving significant increases in silver and gold production, positioning Coeur for robust revenue and earnings growth in the near to medium term."
What investors will be watching closely now is how one underappreciated swing factor ultimately feeds through into margins and long term cash generation.
That underappreciated swing factor is exactly what the full narrative for Coeur Mining breaks down, showing how Coeur Mining could see accelerating value if today's setup is being mispriced.

Seeking Alternatives Before The Crowd?
Fresh ideas move first. Breakout themes gain momentum, then flying prices get caught by late money. Scan these curated lists while the data still matters and get in early.
- Spot resilient cash generators and stress test your watchlist against a curated list of solid balance sheet and fundamentals (23 results) before quality gets priced higher, especially if markets start rewarding strong fundamentals again.
- Track where income seekers may head next by reviewing a hand picked mix of 6 dividend fortresses while yields remain elevated and before payout stability gets fully recognized.
- Position ahead of potential energy shifts by screening a focused group of 19 nuclear energy infrastructure stocks while they are still under the radar for now and before sentiment swings the spotlight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com