
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Broadcom Stock And 2 More Profitable AI Stocks
The Federal Reserve just kicked off a fresh rate hiking cycle, and that raises the bar for every growth story that is still losing money. Cash now pays again. That puts real attention on businesses already turning artificial intelligence spending into profits instead of promises. This article breaks down three AI-focused stocks from a curated screener that focuses on current earnings power, not distant hopes.
The stocks in this article are just a sample, and the full screen surfaced 35 more profitable AI companies with equally compelling stories that are not covered below. If you want to go straight to the source, use the Profitable AI Stocks screener to identify, analyze, and focus on the AI earners that best fit your own criteria.
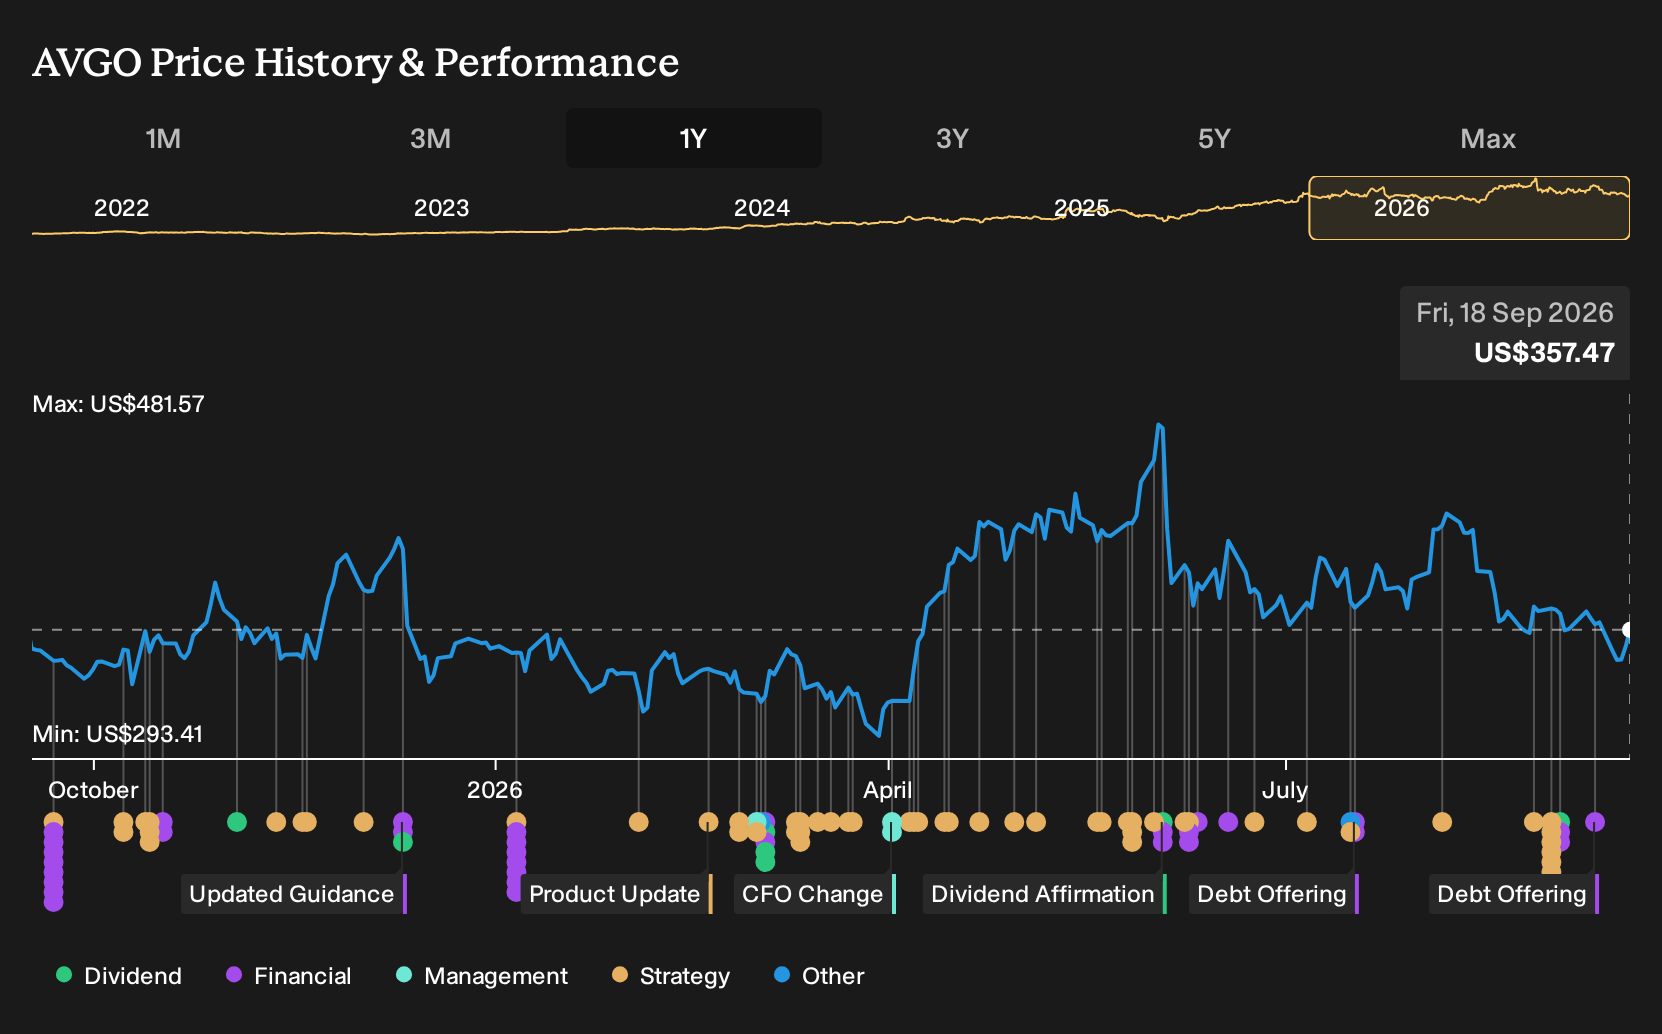
Broadcom (AVGO)
Broadcom is best known for the semiconductor and software plumbing that keeps modern computing running, with its AI-focused data center chips turning networking demand into real earnings rather than speculative promises.
Broadcom Inc. earns about US$59.4b from Semiconductor Solutions, including AI networking and connectivity hardware, and roughly US$29.7b from Infrastructure Software, while its market cap sits near US$1.66t.
"Broadcom is generating substantial free cash flow, expanding its custom silicon business, strengthening its position in networking, and integrating software assets that further diversify earnings."
What happens to Broadcom’s AI story depends heavily on one unseen pressure that could reshape how reliably those profits compound over time.
That pressure is exactly what the full narrative for Broadcom unpacks, showing how Broadcom’s AI cash engine could either absorb it or see returns decoupling from the current story.
Nebius Group (NBIS)
Nebius Group builds full stack infrastructure for AI, which anchors its role in a screener focused on companies already turning AI compute spending into real revenue rather than just promises.
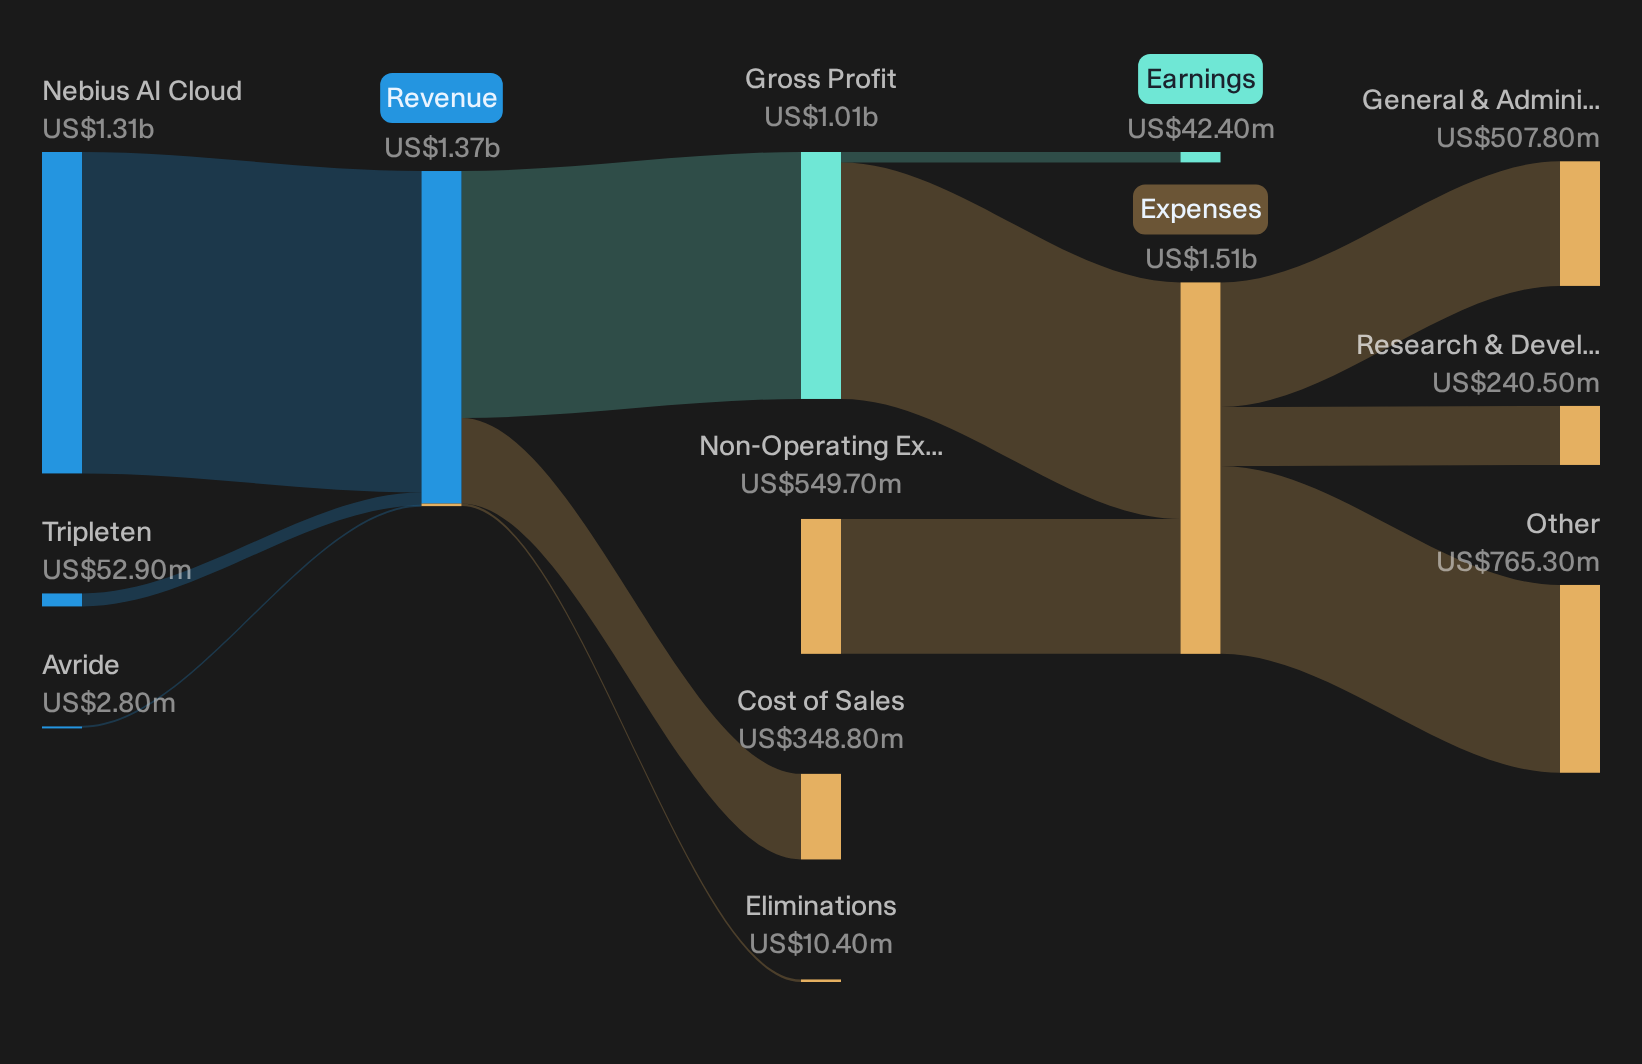
Nebius Group runs large scale GPU clusters and an AI cloud platform that generated about US$1.31b in Nebius AI Cloud revenue, alongside US$52.9 million from TripleTen and US$2.8 million from Avride, and the stock carries a market value near US$59.8b.
"As Nebius Group aggressively expands data center capacity and pursues greenfield builds to support future growth, heightened regulatory scrutiny regarding data sovereignty and localization, especially in core markets such as the U.S., Europe, and Israel, may significantly increase compliance costs and limit expansion potential."
What could significantly influence the story is how one unresolved issue affects the pricing power that supports Nebius Group’s AI cloud margins.
That pricing power question is exactly where the full narrative for Nebius Group steps in, mapping how Nebius Group’s AI buildout could turn regulatory friction into accelerating long term value.
Lumentum Holdings (LITE)
Lumentum Holdings builds the optical hardware that lets AI data centers move vast amounts of information quickly, with its high speed lasers and modules for AI and cloud networking tying the business directly into this screener’s focus on real earnings from AI infrastructure spend. It reports US$3.01b from Integrated Enterprise and carries a market value near US$80.2b.
Lumentum Holdings shows how AI infrastructure suppliers can turn heavy hardware spending into real cash flow, but that hinges on one crucial swing factor investors often overlook.
"If training-cluster buildout peaks and inference networking does not fill the gap, revenue growth could decelerate sharply."
What happens when that single assumption collides with the pace of AI networking upgrades will go a long way to shaping future margins.
If that swing factor matters to you, the full narrative for Lumentum Holdings shows how Lumentum Holdings could turn a stalled buildout into accelerating value.

Curious About What You Might Be Missing?
Fresh ideas move first. By the time every AI headline catches up, the early momentum can be gone. Scan these curated lists while it matters and explore opportunities early.
- Target income that does more than tread water by reviewing a hand picked group of high yield opportunities through the 6 dividend fortresses.
- Explore potential leaders before they leave the small cap bracket by working through a curated lineup of AI upstarts in the 36 AI small caps.
- Review a focused basket of grid and power enablers that may benefit from infrastructure spending with the 38 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com