
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Is Drawing Attention To Green Brick Partners (GRBK)?
Green Brick Partners (GRBK) reached a new milestone at Rainwater Crossing in Celina, Texas, as joint venture partner HFI Capital opened Whispering Grove, a two-acre entrance park that serves as a central feature of this master-planned community.
For context, Green Brick Partners’ share price has eased over the past quarter, with a 90 day share price return down 11.26% and a 30 day share price return down 7.20%. However, the year to date share price return is up 4.75% and the 3 year total shareholder return is 59.24%, which points to long term momentum but some recent cooling as investors reassess growth prospects and risk around projects like Rainwater Crossing.
Scan beyond Green Brick Partners and review other homebuilding and real estate developers with resilient balance sheets and fundamentals using our curated list of solid balance sheet and fundamentals (23 results).
Bulls point to Green Brick Partners’ master planned pipeline and long term shareholder returns. Bears focus on the recent pullback and slightly softer earnings growth. Which story does the current valuation really support next?
Price-to-Earnings of 9.9x: Is it justified?
Green Brick Partners trades on a P/E of 9.9x, with the last close at $66.21, while still being described as trading at good value compared with peers and the broader US market.
The P/E ratio compares what investors pay for each dollar of current earnings. For a homebuilder and land developer like Green Brick Partners, it helps frame how the market weighs its current profitability against the earnings profile that comes with cyclical housing demand and project timing.
This stock carries several mixed signals that feed into that multiple. Earnings have risen by 10.9% per year over the past 5 years, yet profit fell 16.9% in the most recent year and net profit margins eased from 16.7% to 14.6%. Return on equity of 15.4% is classified as low versus a 20% benchmark, and earnings are forecast to decline by an average of 0.6% per year over the next 3 years, so the current earnings power is doing a lot of the heavy lifting in justifying the price investors pay today.
Set against that earnings profile, the market is applying a P/E that is described as good value compared with both the US Consumer Durables industry average of 12.9x and a peer group on 17.1x. The ratio also sits below an estimated Fair P/E of 12.8x. This suggests a level that investor expectations could move toward if sentiment around Green Brick Partners normalises relative to that fair ratio benchmark.
Explore the SWS fair ratio for Green Brick Partners.
Result: Price-to-Earnings of 9.9x (UNDERVALUED)
Still, if homebuyer activity softens or Green Brick Partners encounters delays in large communities like Rainwater Crossing, that P/E support could erode quickly.
Find out about the key risks to this Green Brick Partners narrative.
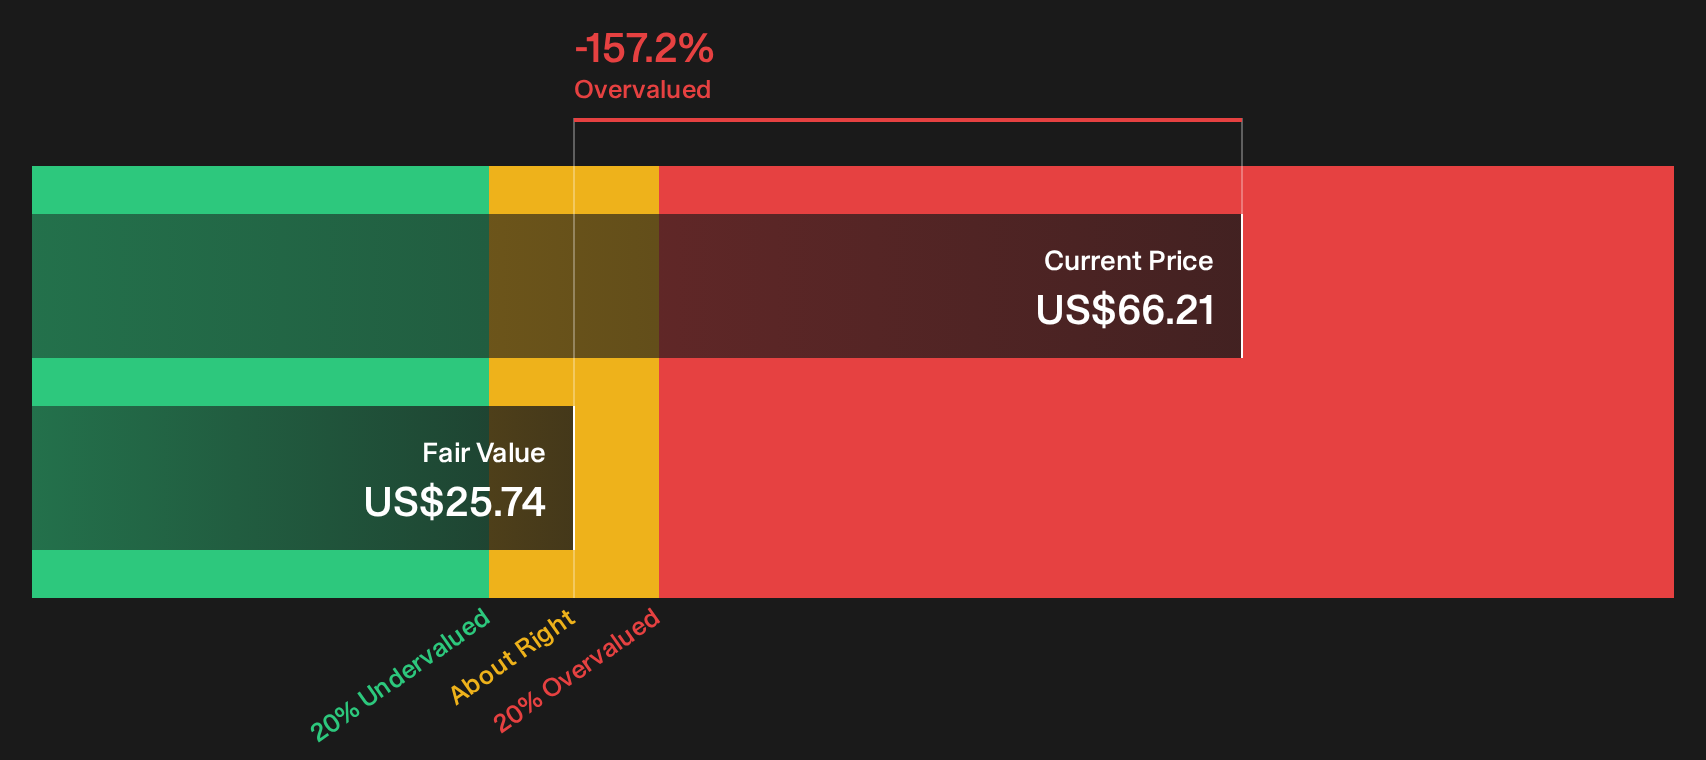
Another View: SWS DCF Says Green Brick Partners Is Overvalued
The P/E story points to Green Brick Partners looking cheap, but the SWS DCF model tells a very different story. On that framework, an estimate of future cash flow value sits at $25.74 per share versus the current $66.21 price. This implies the stock screens as overvalued on cash generation.
For readers who want to see how that cash flow view is built line by line, and how sensitive it is to different assumptions, Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Green Brick Partners for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or real opportunity for Green Brick Partners? Weigh the 1 key concern against the 2 potential upsides and decide quickly where you stand by reviewing the 2 key rewards and 1 important warning sign.
Want more ideas beyond Green Brick Partners?
You have seen how one stock can split opinion. Now widen the lens and pressure test your thinking against a broader set of opportunities.
- Target potential mispricing by scanning a curated group of companies that combine quality fundamentals with appealing entry points through the 33 high quality undervalued stocks.
- Strengthen income potential by focusing on businesses that pair higher yield with robust cash generation using the 6 dividend fortresses.
- Prioritise capital preservation by filtering for enterprises screened for resilience and lower risk profiles via the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com