
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Strong Buy Upgrade Could Be A Catalyst For Kaiser Aluminum Stock (KALU)
- Kaiser Aluminum was recently upgraded to a Zacks Rank #1, reflecting analyst expectations for stronger earnings underpinned by its value added aerospace, packaging and engineering products.
- The focus on higher margin coated packaging and aerospace plate capacity sits at the center of this optimism around Kaiser Aluminum's earnings profile.
- We will look at how Kaiser Aluminum's broader investment narrative intersects with this earnings focused upgrade and improving capacity utilization.
Scan beyond Kaiser Aluminum and see how other earnings driven industrials line up with our hand picked 33 high quality undervalued stocks benefiting from similar margin focused stories.
Kaiser Aluminum Investment Narrative Recap
To be a shareholder in Kaiser Aluminum, you need to believe that its higher value aerospace, packaging and engineering products can keep earning attractive conversion economics even if headline revenue growth is modest. The near term story still turns on getting Trentwood and Warrick running cleanly at higher utilization, which would translate existing demand into steadier margins and cash generation.
The key short term catalyst is execution on that mix shift toward coated packaging and aerospace plate, without new start up friction or outages eroding profitability. The biggest risk is leverage and cash flow coverage if volumes or pricing soften, because debt is not well covered by operating cash flow based on current assessments.
The Zacks Rank upgrade ties most directly to the same operational levers investors already watch. It points to improving earnings expectations that align with Trentwood Phase 7 ramping, Warrick’s fourth coated line maturing and the broader tilt toward value added aerospace and packaging volumes rather than bare commodity style output.
No fresh corporate announcements were flagged alongside this rating change. The relevant context is still the existing project slate and balance sheet path. For you as a shareholder, the practical question is whether Kaiser Aluminum can convert that installed capacity into consistent free cash flow while managing debt, especially if industry forecasts calling for revenue and earnings declines prove accurate.
What The Analyst Case Implies For Kaiser Aluminum
Kaiser Aluminum's narrative projects revenues of US$4.4b and earnings of US$202.2m by 2029. This aligns with analyst assumptions for yearly revenue growth of 1.8% and an earnings decline of US$24.8m from current earnings of US$227.0m.
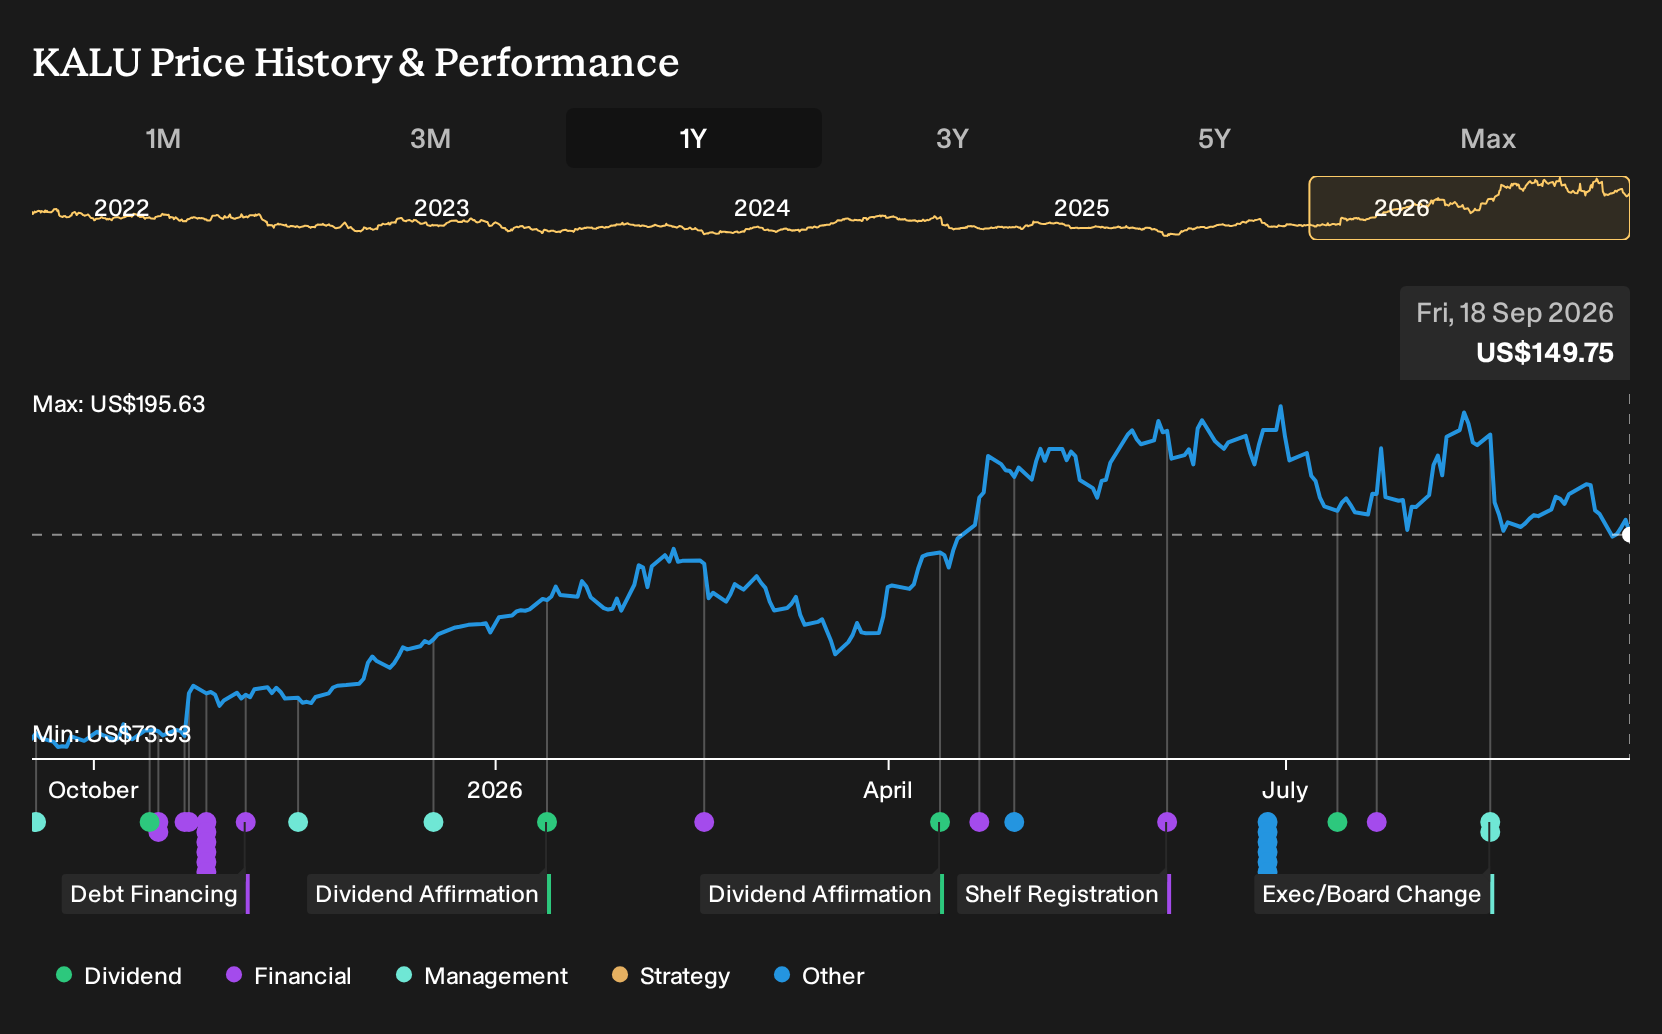
Uncover why Kaiser Aluminum's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on Kaiser Aluminum leans hard into Warrick. Bullish analysts were penciling in revenue climbing toward US$5.2b and earnings of US$246.9m by 2029, assuming coated packaging and an 80% utilization goal really take hold. That is much more optimistic than consensus and could shift again after this Zacks Rank news.
Explore 2 other Kaiser Aluminum fair value estimates, including one that suggests potential upside of as much as 187% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Kaiser Aluminum research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kaiser Aluminum. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kaiser Aluminum's overall financial health at a glance.
Looking for more Kaiser Aluminum style investment ideas?
If the Kaiser Aluminum story has you thinking about where else earnings quality, balance sheet strength and dividends might line up in your favor, the Simply Wall St Screener can help you quickly sort through thousands of stocks using the same kind of fundamentals that matter here.
- For investors who care most about resilient businesses with room to rerate, scan a curated set of companies trading on attractive fundamentals through the 33 high quality undervalued stocks.
- If capital preservation and steadier return profiles sit higher on your list, filter for companies with stronger finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Income focused investors can zero in on cash return potential by reviewing a hand picked 6 dividend fortresses that screens for higher yielding payers with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com