
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Monthly Pass Payments Could Be A Game Changer For Six Flags Stock (FUN)
- Six Flags Entertainment introduced Flex Pay by Upgrade, a financing option that lets eligible guests spread online purchases of Season Passes and other qualifying products of $49 or more into fixed monthly installments, with APRs ranging from 0% to 36% depending on credit and other approval factors.
- The Flex Pay rollout ties Six Flags Entertainment’s season pass model more closely to predictable monthly budgets, which could influence demand patterns for advance bookings, premium products, and multi-visit experiences across its park portfolio.
- This article examines how Six Flags Entertainment’s investment narrative is shaped by the new Flex Pay installment option for season passes.
Scan beyond Six Flags Entertainment and see how other experience driven operators are reshaping demand with flexible pricing and financing through a curated set of 16 high quality undiscovered gems
Six Flags Entertainment Investment Narrative Recap
For Six Flags Entertainment to make sense in a portfolio, you need to be comfortable with a leveraged, capital intensive leisure group that depends on steady attendance and season pass uptake. The near term story leans heavily on improving recurring revenue, cost discipline and merger synergies while working back from a large reported loss and unprofitable footing.
The Flex Pay launch plugs into that near term catalyst by aiming to smooth out household budgeting and lock in more committed guests. The biggest immediate risk still sits on the balance sheet. Net debt of about US$5.3b and high interest costs leave little room for revenue shocks, weather disruption or misfires on reinvestment.
The most relevant recent move around this news is Six Flags Entertainment’s push into upgraded digital and ecommerce infrastructure. Flex Pay fits into that stack, since it operates within the online checkout flow and relies on a clear path from product selection to third party credit approval.
If that broader digital push is effective, the business gains more levers to adjust pricing, run promotions and test the impact of installment options on attendance and in park spending. If execution is weak or weather and cost headwinds are more severe, the financing feature risks becoming just another tool that does not significantly affect debt and profitability targets.
Six Flags Entertainment's narrative projects US$3.2b revenue and US$97.2m earnings by 2029. That aligns with analyst assumptions of 1.2% yearly revenue growth and implies an earnings increase of about US$1.9b from current earnings of a US$1.8b loss.
Uncover how Six Flags Entertainment's fair value indicates a 73% potential upside to its current price, which could narrow quickly.
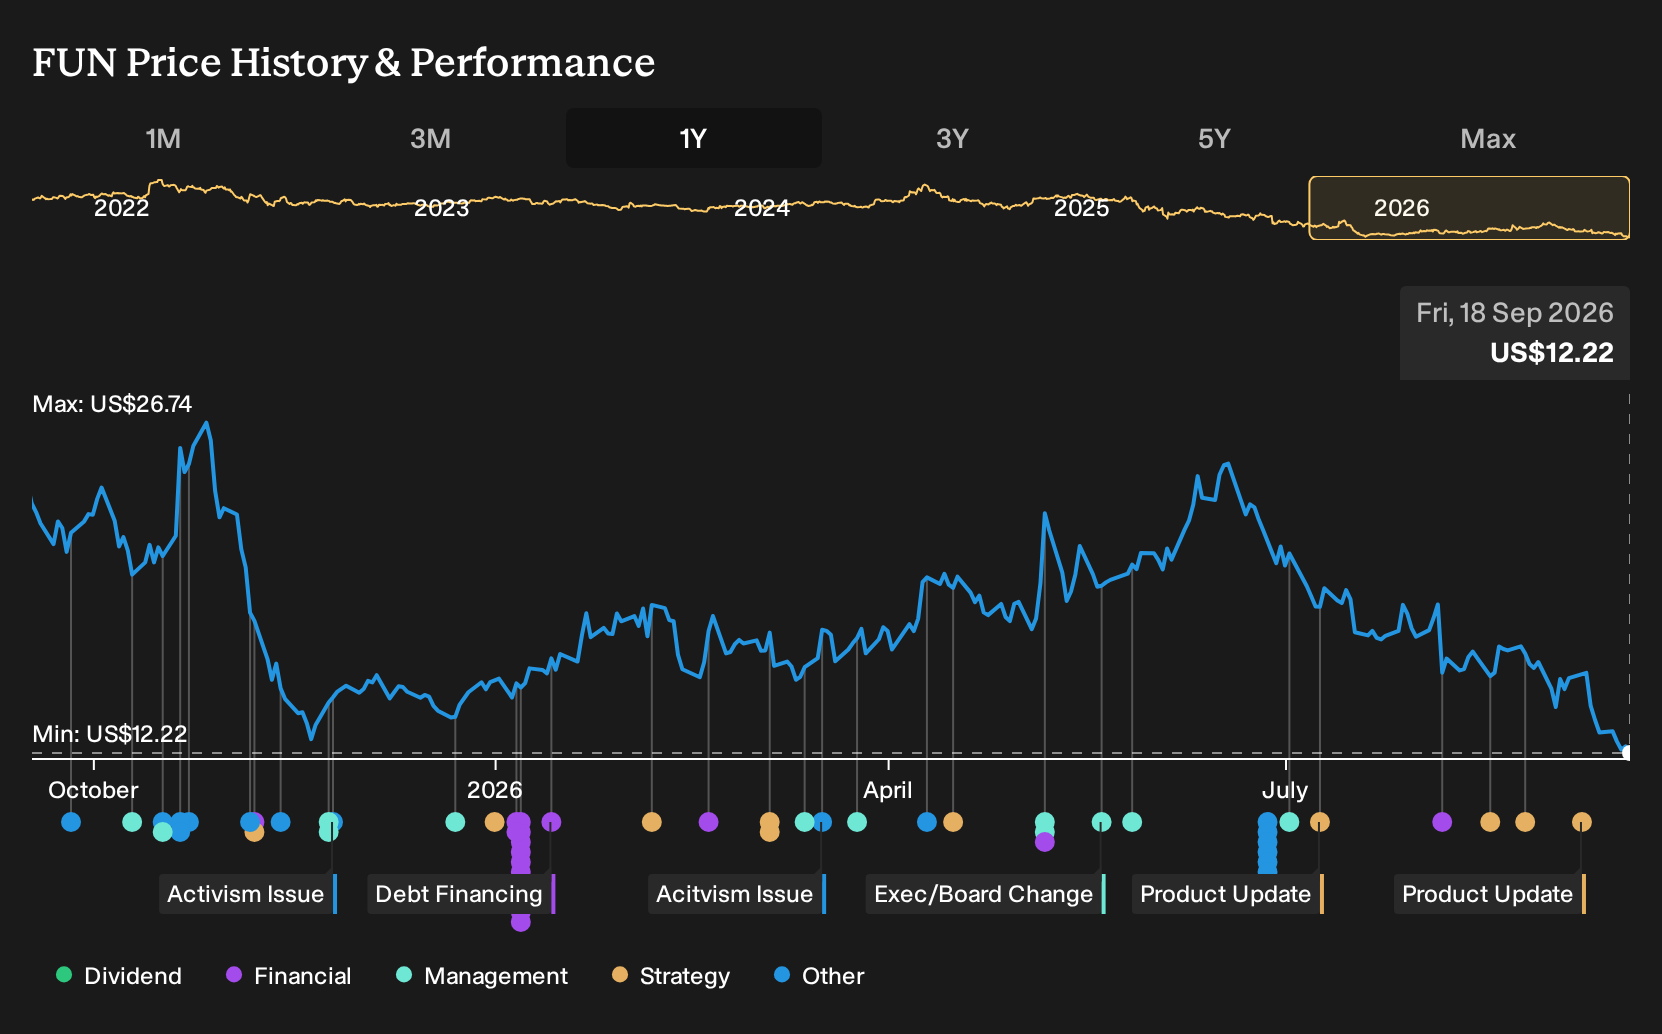
Exploring Other Perspectives
For a different angle on Six Flags Entertainment, focus on the bullish view that digital integration could be the real swing factor. The most optimistic analysts were already penciling in US$3.2b of revenue and US$275.2m of earnings by 2029 before Flex Pay existed. You can treat today’s news as a fresh reason to compare those upbeat expectations with more cautious scenarios.
Explore 4 other Six Flags Entertainment fair value estimates, including one that suggests potential upside of as much as 381% from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Six Flags Entertainment research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Six Flags Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Six Flags Entertainment's overall financial health at a glance.
Looking for more investment ideas beyond Six Flags Entertainment?
If the Flex Pay story has sharpened your view on Six Flags Entertainment, you can use that same lens on other companies. The Simply Wall St Screener lets you quickly filter for portfolios built around quality, balance sheet strength or specific return profiles instead of scrolling through endless tickers.
- Prioritize financial resilience by zeroing in on companies with stronger funding profiles through the list of solid balance sheet and fundamentals (23 results).
- If you care most about capital preservation and steadier profiles, focus on the 30 resilient stocks with low risk scores to see which businesses score well on risk metrics.
- For investors hunting for underfollowed opportunities with sound fundamentals, the 16 high quality undiscovered gems can surface stocks that might not yet be widely watched.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com