
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Targa Resources (TRGP) Sustainability Report Puts Its Valuation Case Back In Focus
Targa Resources (TRGP) has released its 2025 Sustainability Report, giving investors fresh detail on how environmental, social, and governance priorities intersect with this Houston based infrastructure operator’s natural gas and NGL focused business.
Targa Resources’ share price has moved to US$292.19, with a 90 day share price return of 13% and a year to date gain of 56.44%. The 1 year total shareholder return of 81.52% and 5 year total shareholder return above 5x suggest strong longer term momentum around the stock as investors digest new disclosures such as the 2025 Sustainability Report.
Scan beyond Targa Resources and see how other energy infrastructure players with strong momentum and detailed disclosures stack up in our curated list of 33 high quality undervalued stocks.
For Targa Resources, an 81.52% one year total return could signal a stronger underlying infrastructure franchise, or it could reflect sentiment chasing recent ESG headlines. The valuation work starts with separating those forces.
Most Popular Narrative: 8% Undervalued
The most followed valuation storyline currently places Targa Resources’ fair value at $318.81, modestly above the recent $292.19 close. This frames the recent rally against a still supportive long term model built on contracted growth and export optionality.
Substantial investment in integrated export infrastructure, including the expansion and debottlenecking of LPG export facilities and new fractionation trains, directly leverages rising international and petrochemical sector demand for U.S. NGLs. This creates long term opportunities to enhance utilization and operating leverage, which may support higher earnings and margins.
See why 19 investors see Targa Resources as 8% undervalued.
Result: Fair Value of $318.81 (UNDERVALUED)
Still, the story around Targa Resources can change quickly if Permian overbuild pressures fees, or if tighter environmental rules push up long term project costs.
Find out about the key risks to this Targa Resources narrative.
Another View On Targa Resources' Valuation
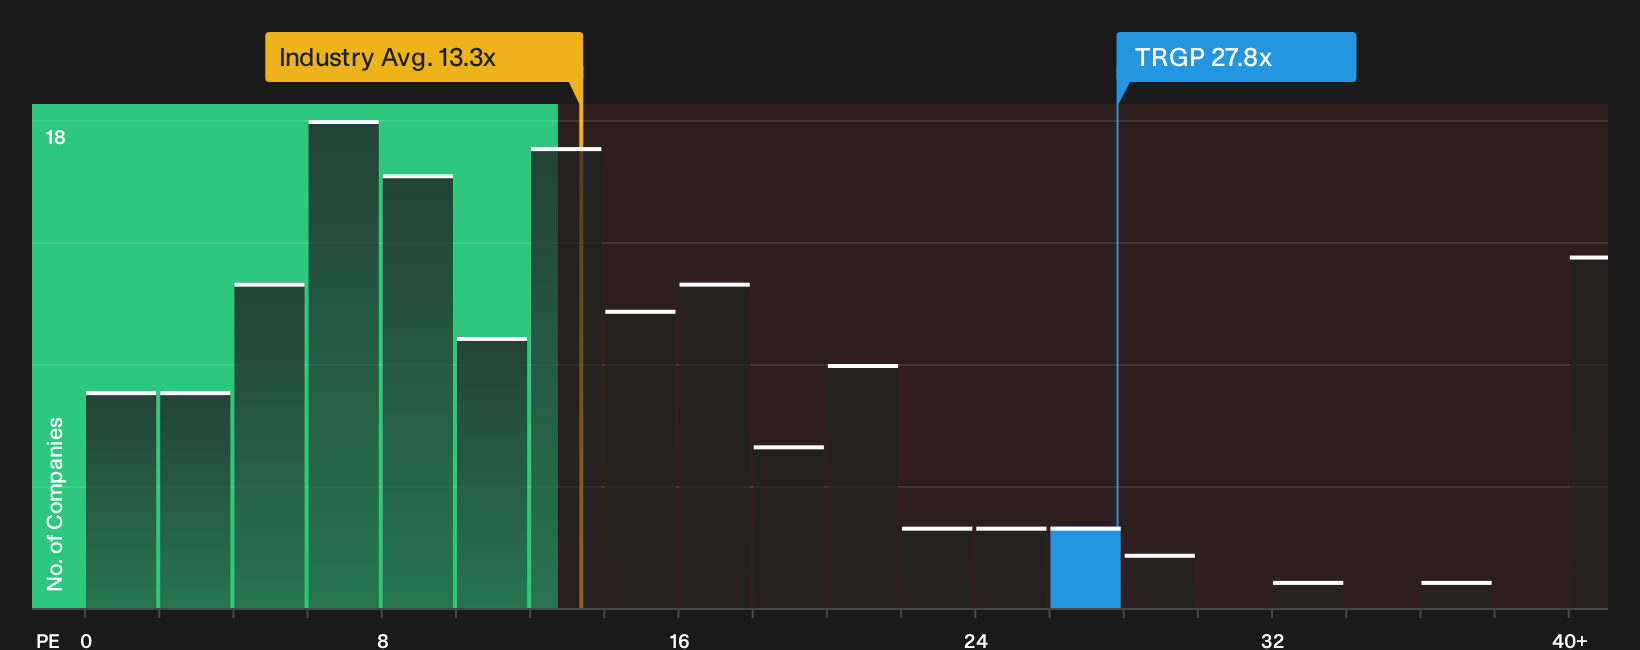
The first fair value story for Targa Resources leans on long term cash flow and analyst targets. A simple P/E lens paints a very different picture. TRGP trades at 27.8x earnings versus 13.3x for the US Oil and Gas group and a fair ratio of 25.3x, which points to a richer entry point and a thinner margin for error if growth cools.
That premium may reflect confidence in the Exxon contracts and Permian buildout, or it may leave holders more exposed if sector sentiment or earnings delivery reset sharply from here. Which side of that trade-off feels more realistic to you as an investor?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of optimism and concern around Targa Resources makes this a live debate, not a settled verdict, so move quickly and pressure test the numbers yourself. To see the key issues investors are weighing on both sides, review the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Targa Resources?
If Targa Resources has sharpened your thinking, do not stop here. Broaden your watchlist using focused stock ideas that match how you like to invest.
Put potential income first and review companies that feature reliable payouts and higher yields with the help of 6 dividend fortresses.
Prioritize resilience and stress test your downside by scanning through a 30 resilient stocks with low risk scores tailored to businesses with sturdier risk profiles.
Hunt for underfollowed opportunities and see which firms with strong fundamentals are hiding inside our curated 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com