
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Foresight Group Holdings And 2 British Cash Flow Stocks To Watch
The Bank of Japan lifting interest rates to a 31 year high has pushed investors to look harder at where cash will actually come from in their portfolios as borrowing costs rise and easy money fades. That focus puts undervalued British businesses with solid cash flow potential in the spotlight. This article highlights three stocks from our cash focused value screener that could appeal to patient UK investors.
These three ideas are just a sample, and the full screen surfaced 7 more UK businesses with similarly cash driven stories that are not covered below. To go beyond the shortlist and actively analyze, compare, and identify your own highest conviction opportunities, head straight into the Undervalued Stocks Based On Cash Flows screener.
Foresight Group Holdings (LSE:FSG)
Foresight Group Holdings is an infrastructure and private equity manager with a strong focus on managing renewable energy assets that generate long term, contract backed cash flows. This is exactly the type of cash profile this screener is built to surface.
Foresight Group Holdings earns most of its income from Real Assets at about £114.8 million, with a further £50.1 million from Private Equity, giving it a sizeable fee base for an asset manager of roughly £493 million in market value.
For investors interested in cash focused value ideas, Foresight Group Holdings offers an example of how fee income from long life renewables and real assets can underpin a discounted cash flow based valuation story without relying on speculative turnarounds or one off trading gains.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What really matters from here is how a single pressure on fee margins and capital costs shapes the cash generation that underpins that story.
If that pressure on cash generation is what you care about, read the full narrative for Foresight Group Holdings to see how Foresight Group Holdings could handle it as conditions shift.
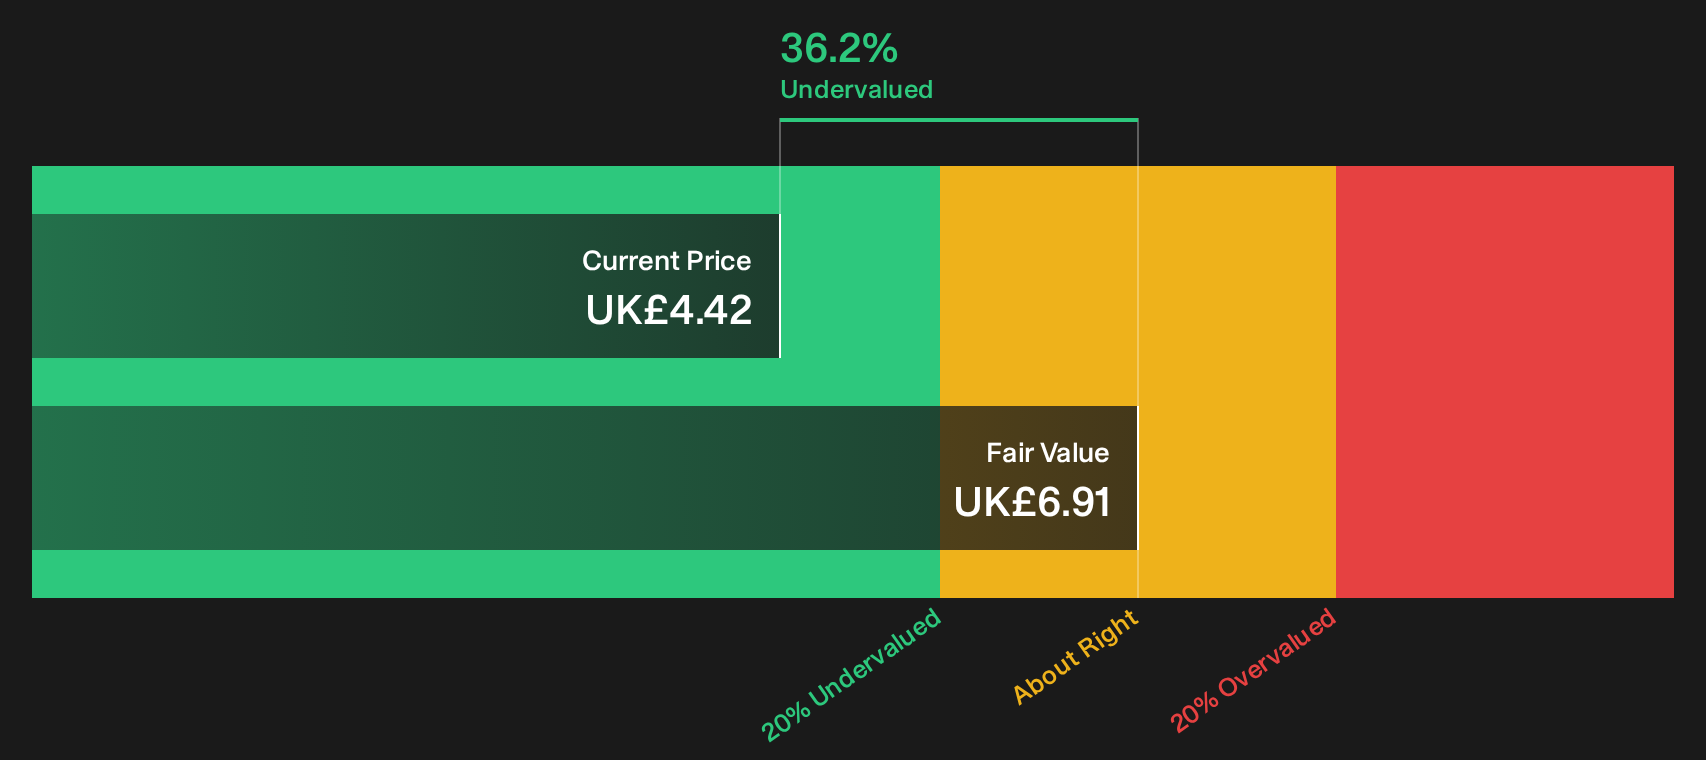
Polar Capital Holdings (AIM:POLR)
Polar Capital Holdings is a London based asset manager that runs equity, balanced and hedge funds for institutional and professional investors, earning fee based cash flows that fit the Undervalued Stocks Based On Cash Flows theme. Its investment management arm generates about £263.6 million of revenue and the business is valued around £789.8 million.
Polar Capital trades at roughly 43% below an SWS DCF fair value. It runs a high margin, fee driven investment management franchise with a 22.3% net profit margin and 5.51% dividend yield. The key question for value focused investors is whether those recurring cash flows can keep compounding if pressures on fund flows and AUM trends shift direction.
If you are weighing whether those fee based earnings can keep compounding, go straight to the analyst forecasts for Polar Capital Holdings to see how the story could evolve.
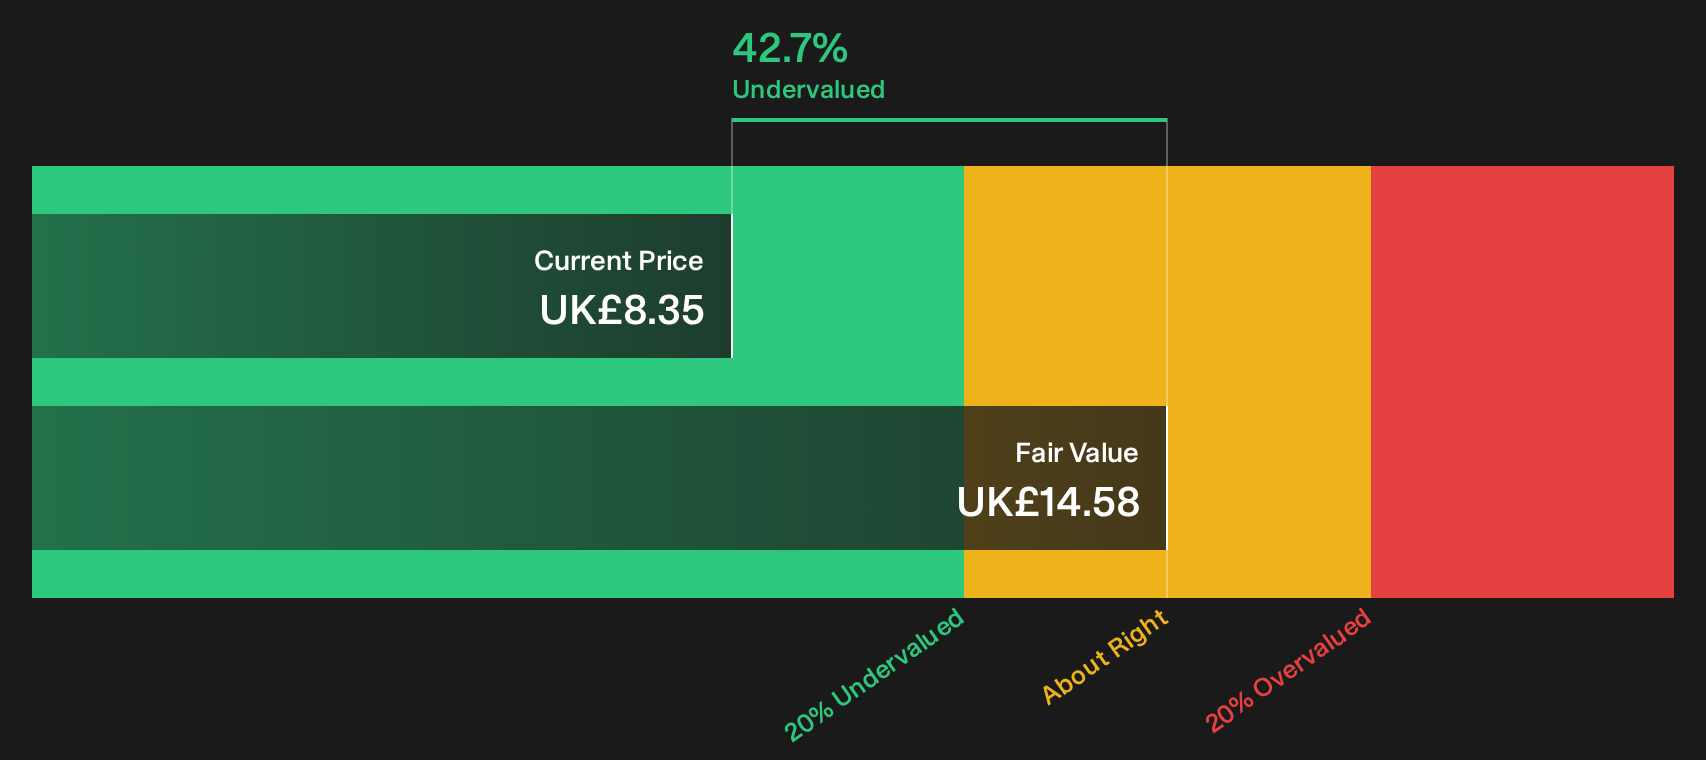
PayPoint (LSE:PAY)
PayPoint leans into the screener’s cash flow theme through its payments terminals and retailer services, which throw off steady transaction fees, while the Love2shop voucher arm adds a second income stream. Together, these support a £179 million and £158 million split on revenue and a £370 million market value.
"Ongoing investments in advanced automation, process simplification, and AI-driven analytics could deliver cost reductions and persistent net margin improvements that are materially above current market expectations."
What really shapes PayPoint’s cash flow appeal now is whether one quiet pressure on future revenues tightens or eases over the next few years.
Whether that revenue pressure tightens or eases, the full narrative for PayPoint shows how PayPoint’s cash engine could accelerate or stall as those trends play out.

Seeking Fresh Alternatives Before Others Do
Fresh ideas move first. By the time the crowd spots the breakout, the best entry points can be gone. Scan under the radar for now and act now.
- Track cash rich businesses quietly building momentum through the list of solid balance sheet and fundamentals (11 results) before other investors start paying attention and prices begin moving.
- Target income opportunities using the 1 dividend fortresses while yields remain elevated and share prices have not fully reflected changing demand.
- Look for early developments in frontier technology by tapping the 25 quantum computing stocks while expectations are still evolving and pricing is not focused only on the most widely discussed stories.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com