
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Lemonade (LMND) Stock Could Be Above Fair Value On Sales Growth Hopes
Lemonade has seen its share price move sharply over the past few years, which naturally puts the spotlight on what investors are paying for its sales today. With the stock now trading at US$48.58, the question is how that price lines up with the revenue the business is currently generating.
- Over the past 3 years the stock has returned about 298.2%, which makes the current sales multiple a central piece of the story for anyone looking at Lemonade now.
- The business model is still heavily focused on scaling its insurance platform, so expectations for future revenue growth and the path to more efficient underwriting can shape how much investors are willing to pay for each dollar of sales.
- There is a second opinion on Lemonade worth weighing. See what analysts think Lemonade's shares could be worth.
The stock's next move may depend on whether the current price is well supported by Lemonade's sales base and how that relationship compares with the Fair Ratio benchmark.
If you are weighing whether Lemonade's current P/S multiple feels stretched or reasonable, it can help to benchmark it against a wider group using a focused screen such as 29 high quality undervalued stocks
Does Lemonade Look Pricey on Sales?
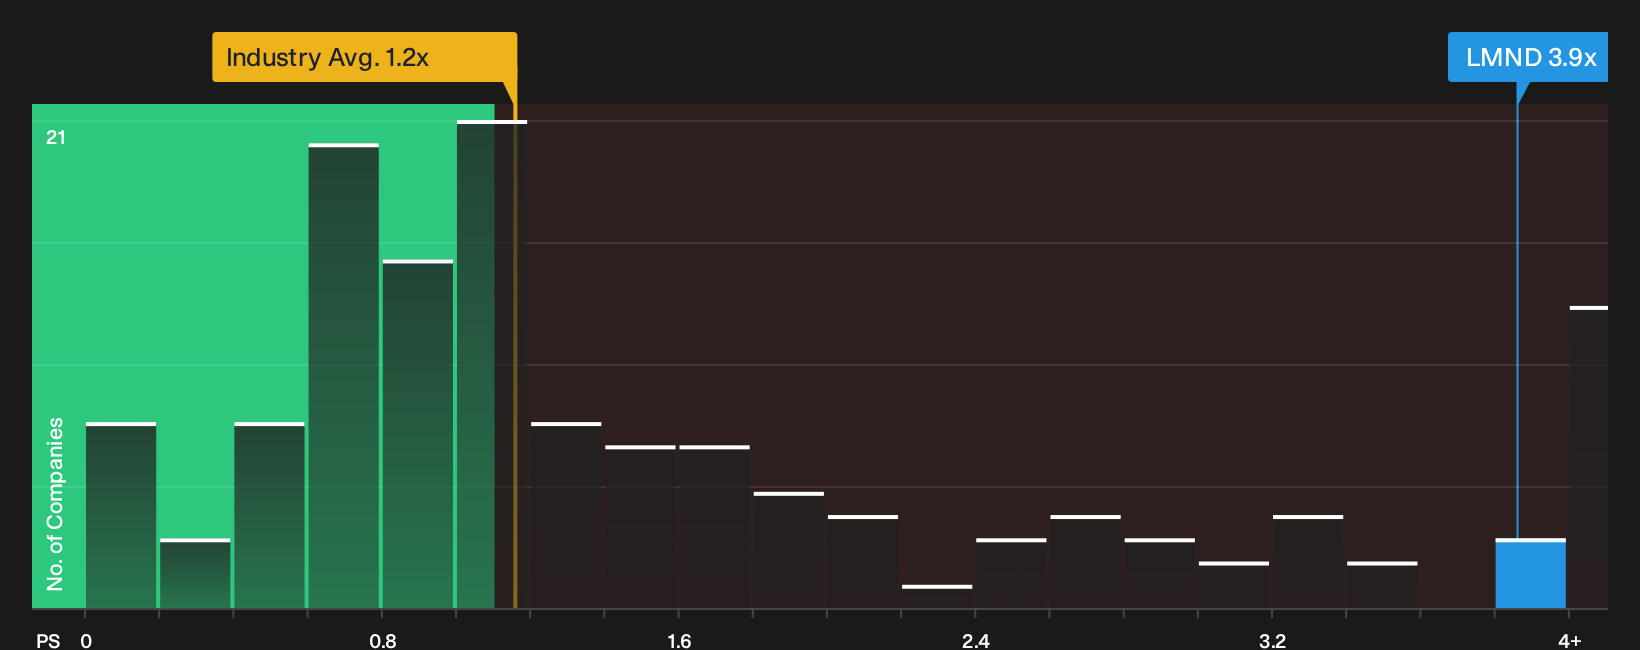
P/S fits Lemonade because investors are mostly weighing top line potential rather than current earnings. At a P/S of 3.9x, the stock trades at more than double the Insurance industry average of 1.2x and also carries a premium to the peer group on about 1.9x. That sets a clear expectation that Lemonade will convert its digital insurance platform and customer base into stronger economics over time, rather than simply tracking the sector.
The Fair Ratio model, which blends factors such as growth profile, profitability, size and risk, points to a lower multiple than the one the market is currently paying. On this framework, Lemonade screens as overvalued on P/S, so anyone considering the shares needs to judge whether the product, underwriting approach and data advantage justify paying materially more per dollar of revenue than both peers and the tailored benchmark. Explore the numbers behind Lemonade's P/S valuation.
The Lemonade Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Lemonade pick up where the valuation puzzle leaves off by spelling out the growth, margin and earnings paths that would need to hold for the stock to be worth materially more or materially less than today’s price on the Community page. Instead of a single output from a ratio or model, these narratives unpack the future that figure leans on so you can watch in real time whether Lemonade’s actual progress stays aligned with those assumptions.
Community views on Lemonade split between those who see an AI driven insurance platform with room to run and those focused on data, climate and valuation risks.
Bull case: 18% undervalued
"Lemonade's rapid adoption and integration of in-house AI-driven underwriting platforms and proprietary data provide a sustainable long-term efficiency advantage..."
Discover why this Narrative puts Lemonade at 18% undervalued.
Bear case: 31% overvalued
"Lemonade faces a material risk to future revenue and net margins due to mounting global data privacy regulations, such as GDPR and CCPA..."
Explore why this Narrative puts Lemonade at 31% overvalued.
One more angle on Lemonade that many investors check
After thinking about what you are paying for Lemonade's current sales, the next piece many investors look at is how professional forecasters see the business a few years out compared with that pricing today. Explore where analysts expect Lemonade to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com