
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Everpure (P) Could Be 42% Undervalued On Needham Coverage
Everpure (P) is back in focus after Needham launched coverage, sending the share price up 4.4% and giving investors fresh reason to reassess this data storage specialist.
The recent 6.5% 1 day share price return and 10.5% 7 day share price return add to a strong year to date share price return of 50.7%. However, the stock is still down 11.2% on a 30 day share price basis. At the same time, the 3 year total shareholder return of about 200% and 5 year total shareholder return of about 285% point to powerful longer term momentum that the Needham coverage and upcoming 2026 analyst day have brought back into focus for Everpure.
Scan Everpure along with other high-momentum data and infrastructure plays by running the hand picked 89 AI infrastructure stocks that tracks similar demand for storage and compute capacity.
Everpure looks like a strong storage platform with real revenue and earnings growth on the board, and a 50% plus year to date share price gain now in the mix. Is that quality still coming at a reasonable price after the Needham move and fresh analyst excitement ahead of the 2026 investor day, or are investors now paying a premium for the story?
Most Popular Narrative: 42% Undervalued
Everpure last closed at $103.99, while the leading narrative-based fair value sits at $180. That gap has put fresh attention on whether the recent rally is just catching up to the story or still leaving meaningful upside on the table.
The market is pricing Everpure as an enterprise storage company. That is the wrong category. Once two or three analysts figure out what is actually happening inside this business, the multiple closes toward AI infrastructure peers, and the stock moves $70 to $80 from here without a single change in fundamentals. Let me walk through why.
See why 44 investors see Everpure as 42% undervalued.
Result: Fair Value of $180 (UNDERVALUED)
Still, this Everpure thesis leans heavily on hyperscale uptake and very low Evergreen churn, and any disappointment on either front could quickly puncture the re rating story.
Find out about the key risks to this Everpure narrative.
Another View On Everpure’s Valuation
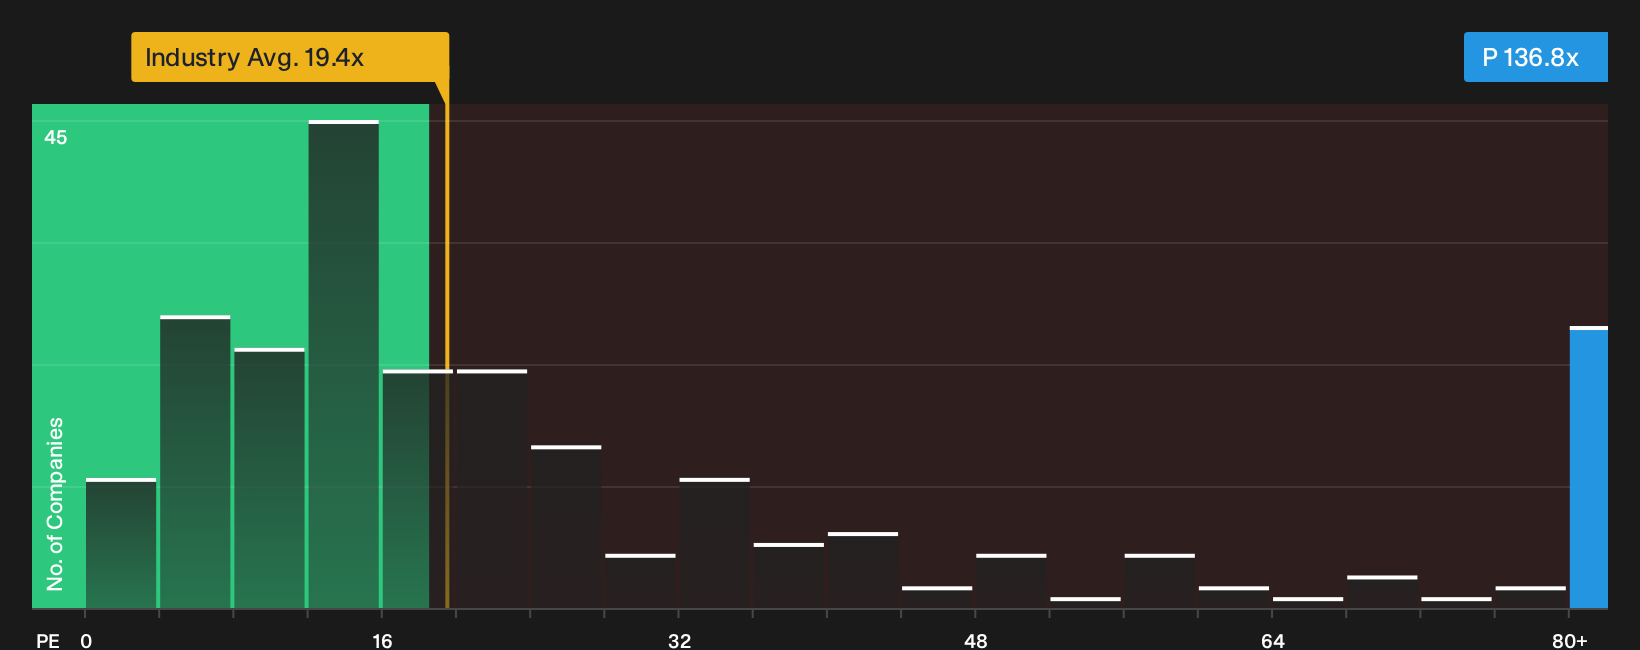
There is a different read on Everpure when you look at simple P/E based pricing. The stock trades on a P/E of 136.8x, while the fair ratio is 54.5x and the Global Tech industry sits at 19.4x, with peers around 20.6x. That kind of gap can mean investors are paying a high premium for the current story. Is that a risk you are comfortable with, or a quality premium you think holds up over time?
For a closer look at how this pricing compares with similar companies and what the fair ratio gap might mean in practice, check the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Everpure is clearly split. This is exactly why it helps to move fast, pull up the data yourself, and test every claim against your own risk tolerance. To see the mix of concerns and positives in one place, start with the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Everpure?
Do not stop at Everpure. Fresh ideas often come from comparing it with other resilient businesses, and the screener tools can surface those in minutes.
- Target resilient potential by reviewing stocks that have cleared strict balance sheet and fundamentals checks through the list of solid balance sheet and fundamentals (23 results).
- Spot possible mispriced opportunities by scanning the 16 high quality undiscovered gems, which filters for quality fundamentals the market may not be fully pricing yet.
- Prioritise stability and sleep better at night by focusing on the 30 resilient stocks with low risk scores, which highlights companies with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com