
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Atlas Copco (OM:ATCO A) Service Center Expansion
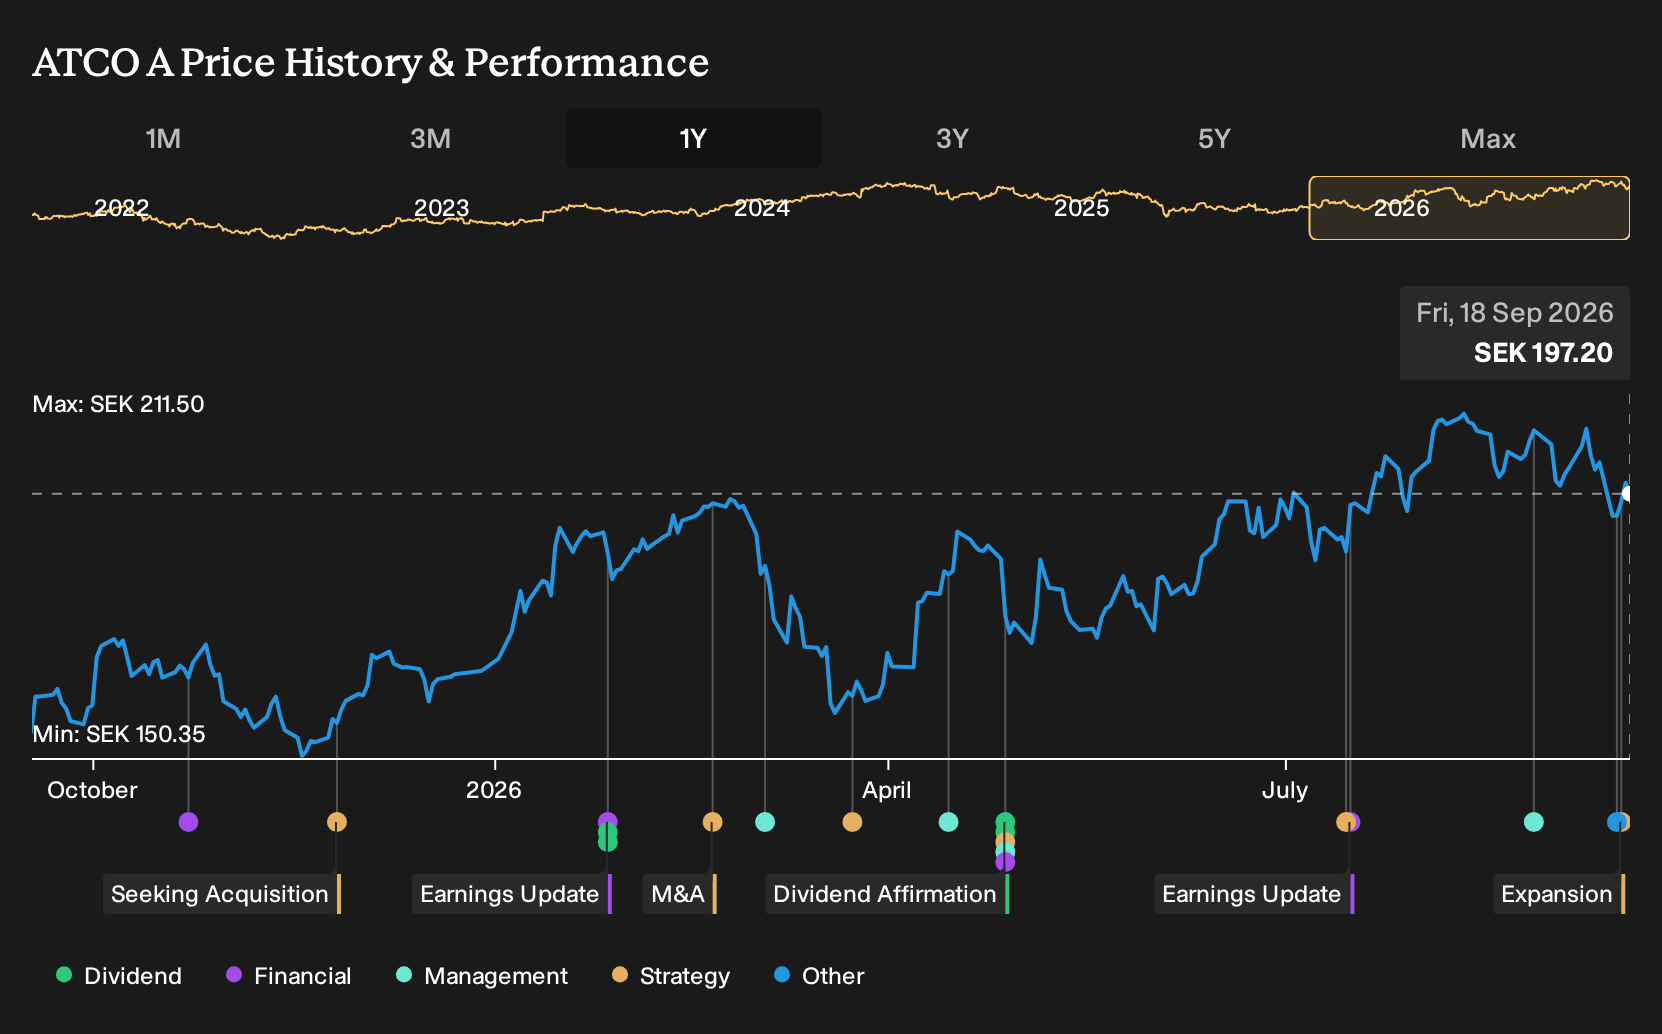
- Atlas Copco has broken ground on a 355,000 square foot North American Service Center in Lancaster County, South Carolina. The facility is designed to support warehousing and distribution of equipment and millions of spare parts, with operations planned to start in June 2027.
- The facility’s use of advanced robotics, automation, and energy efficient design indicates a push for scaled service capacity and logistics efficiency in Atlas Copco’s North American operations.
- Attention now turns to how Atlas Copco's broader investment narrative could be shaped by this automated North American Service Center build out.
Atlas Copco Investment Narrative Recap
To own Atlas Copco, you need to believe that compressed air, vacuum, tools, and related services keep finding work across cycles, and that service and aftermarket continue to anchor earnings. The new North American Service Center fits that logic by aiming to support those recurring activities, although it does not change the near term reliance on customer decisions for larger compressor and Gas & Process orders.
In the short term, the critical swing factor remains how quickly hesitant customers resume placing bigger equipment projects. Key risks still sit in currency pressure, potential tariff moves, and weaker orders in China and parts of Europe. The Lancaster build looks important for long run logistics and cost efficiency, but its impact on near term orders and margins appears limited.
The service center ground breaking in South Carolina is the operational move that ties most directly to the current catalyst list. Management is putting capital into warehousing, automation, and energy efficient infrastructure that is intended to handle compressed air equipment, tools, portable power, and millions of parts. That aligns tightly with the push toward a larger, higher margin service base.
This build also connects to the automation and digitalization theme around Atlas Copco. Advanced robotics and automated handling support quicker deliveries and, if executed well, more consistent service quality for industrial and semiconductor customers. Execution risk is real, from build costs to integration across four big US facilities. Investors will likely watch timelines, budget discipline, and operational uptime once the hub goes live in 2027.
Atlas Copco's current earnings of SEK 26.6b are covered by analyst expectations that revenues will reach SEK 232.4b and earnings will reach SEK 41.0b by 2029. This implies 11.0% yearly revenue growth and an earnings increase of SEK 14.4b from earnings today.
Uncover how Atlas Copco's fair value indicates an 11% potential upside to its current price before other investors move to close that gap.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for Atlas Copco. They lean hard into semiconductor related vacuum demand and, before this service center news, were already pencilling in revenue of about SEK 259.9b and earnings of SEK 46.8b by 2029. Those expectations may shift once this logistics build is fully factored in. Treat this as one of several viewpoints to compare for yourself.
Explore 3 other Atlas Copco fair value estimates, including one that suggests up to 11% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Atlas Copco research is our analysis highlighting 1 key reward that could impact your investment decision.
- See our latest analysis for Atlas Copco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Atlas Copco's overall financial health at a glance.
Looking for more Atlas Copco style ideas?
If the Atlas Copco story has you thinking about where automation, balance sheet strength, and resilient cash generation might show up next, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors hunting for potential mispricings with quality fundamentals behind them, the 173 high quality undervalued stocks can help surface candidates worth a closer look.
- If resilience and capital preservation matter most to you, consider filtering for companies with steadier profiles using a 227 resilient stocks with low risk scores that keeps downside firmly in view.
- Those who prefer businesses with cleaner finances and fewer balance sheet surprises might start with a list of solid balance sheet and fundamentals (197 results) that narrows the field to sturdier operators.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com