
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Dell Technologies (DELL) Earnings Strength Keeps Valuation In Focus
Dell Technologies (DELL) just closed out a multiyear buyback, retiring 204.4 million shares for US$19.6b, even as record AI server demand, rising revenue guidance, and strong earnings revisions keep the stock firmly in the spotlight.
The recent 4.46% 1 day share price return, on top of a 16.14% 7 day move and 25.55% 30 day share price return, shows momentum building around Dell Technologies as investors react to record AI server orders, raised revenue guidance and expanding partnerships. That short term surge sits on top of a very large 3 year total shareholder return of about 8x. This suggests that the market has been steadily repricing Dell’s AI and infrastructure exposure rather than treating this year’s 360.41% year to date share price return as a one off spike.
Scan how Dell Technologies fits into the wider AI hardware surge by comparing it against 89 AI infrastructure stocks, which is now capturing capital flowing into data center buildouts and high performance compute suppliers.
After a move like this, along with a completed US$19.6b buyback and an options market implying huge swings, does Dell Technologies still offer a favourable trade off between upside potential and downside risk, or has most of the edge already gone?
Most Popular Narrative: 4% Overvalued
Dell Technologies closed at $588.40 against a widely followed fair value estimate of about $564, so the current debate is whether AI driven momentum justifies that premium or stretches it too far.
Dell is shifting its business mix toward more IP rich and margin accretive storage and services through modernization and efficiency improvements, which is likely to expand operating margins and long-term earnings power.
See why 222 investors see Dell Technologies as 4% overvalued.
Result: Fair Value of $564 (OVERVALUED)
Still, Dell Technologies faces two clear swing factors: weaker margins if AI hardware pricing softens, and ongoing pressure from its more cyclical, PC-focused Client Solutions Group.
Find out about the key risks to this Dell Technologies narrative.
Another View: Cash Flows Point To Undervaluation
The first fair value debate around Dell Technologies is anchored in analyst targets near $564 and argues the stock is about 4% overvalued. A different lens tells another story. The SWS DCF model, based on projected future cash flows, puts fair value closer to $625.94, which screens as undervalued at the recent $588.40 price.
That gap matters. It suggests investors who only look at earnings multiples and price targets might be underestimating the cash that Dell Technologies is expected to generate over time. The question is simple: Which lens do you trust more when both are built on assumptions that can change quickly?
Look into how the SWS DCF model arrives at its fair value.
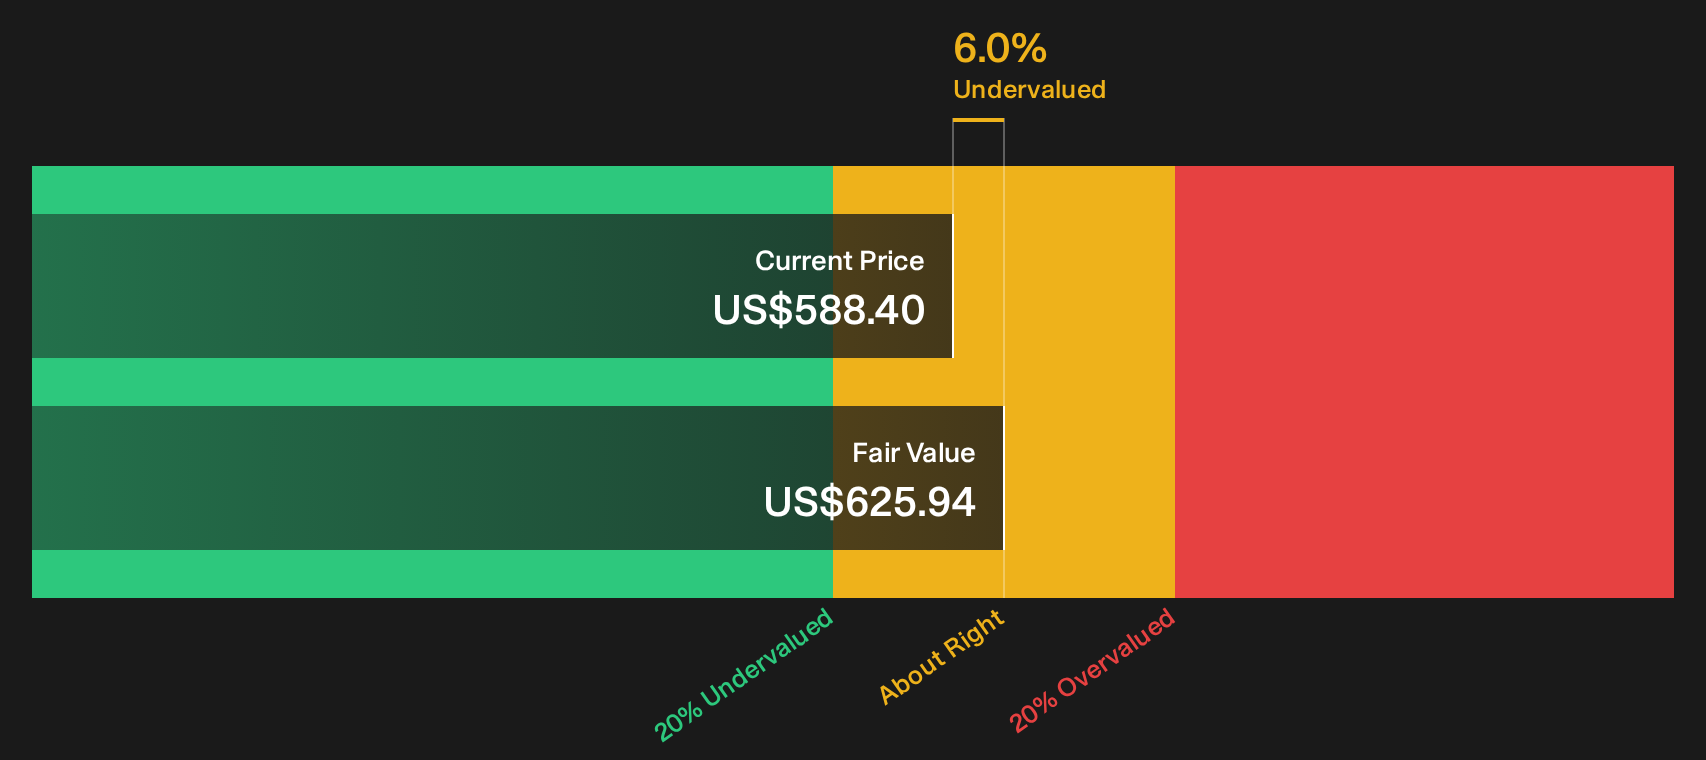
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dell Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Dell Technologies valuations can either feel exciting or confusing, so move quickly, review the full picture, and weigh both sides through the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Dell Technologies?
If Dell Technologies has sharpened your thinking about AI, do not stop there. Broaden your watchlist and give yourself options before the next move hits.
- Target resilient compounding by scanning a curated set of 30 resilient stocks with low risk scores that aim to keep portfolio swings more controlled.
- Hunt for quality at a discount by checking the 29 high quality undervalued stocks that pair stronger balance sheets with supportive fundamentals.
- Unearth early stage potential by reviewing a focused 7 elite penny stocks with strong financials that screens for stronger financial profiles at lower share prices.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com