
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Sterling Infrastructure (STRL) Stock Looks Like A Cash Flow Bargain
Sterling Infrastructure has been on a powerful multi‑year run, and that kind of track record naturally raises a question for you as an investor. Is the current share price still aligned with the cash flows the business is expected to generate, or has the story run ahead of the underlying money coming in the door?
- Over 5 years, Sterling Infrastructure has delivered a very large total return of about 22x, which puts a lot of weight on whether its cash flows can keep backing up that kind of share price journey.
- The company’s focus on infrastructure and construction projects means its valuation now leans heavily on how reliably it can turn awarded work into steady free cash flow, rather than just booked revenue.
- What if you looked at Sterling Infrastructure through its earnings instead? See what Sterling Infrastructure's 35.9x P/E says about the price.
The issue now is whether Sterling Infrastructure’s current market value is justified by the cash flows implied by its intrinsic value estimates.
If you want a second reference point while you assess whether Sterling Infrastructure’s recent run is justified by its cash flows, it may be helpful to compare it with a focused list of 29 high quality undervalued stocks.
Is Sterling Infrastructure a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here is built around the cash Sterling Infrastructure can return to shareholders over time. Latest twelve month free cash flow sits at about $483.7 million, which gives the analysis a solid starting base rather than a speculative story.
Looking ahead, the DCF uses a growing cash flow path, with projected annual free cash flow rising into the low $1b area by 2030. Those forecasts are anchored both in analyst estimates and in more mechanical extensions for the later years, so the curve assumes progress but not an endless acceleration. When those future cash streams are discounted back and compared with today’s share price of $505.72, the projections put Sterling Infrastructure's estimated intrinsic value substantially above the current share price. Find out what Sterling Infrastructure could be worth using our Discounted Cash Flow (DCF) estimate.
The Sterling Infrastructure Narrative: What Would Justify Today's Price?
Narratives for Sterling Infrastructure pick up where the valuation puzzle leaves off by making clear which paths for growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than today’s price. They sit on Simply Wall St's Community page and translate a single output from a ratio or model into a concrete future scenario that you can watch over time to see whether it actually plays out.
One of the top community narratives on Sterling Infrastructure: 28% undervalued
"While Sterling Infrastructure has a combined backlog of US$5.6b and additional high probability future phase opportunities of more than US$1.4b that extend project visibility over many years..."
Discover why this Narrative puts Sterling Infrastructure at 28% undervalued.
One more factor to weigh before acting on Sterling Infrastructure’s valuation story
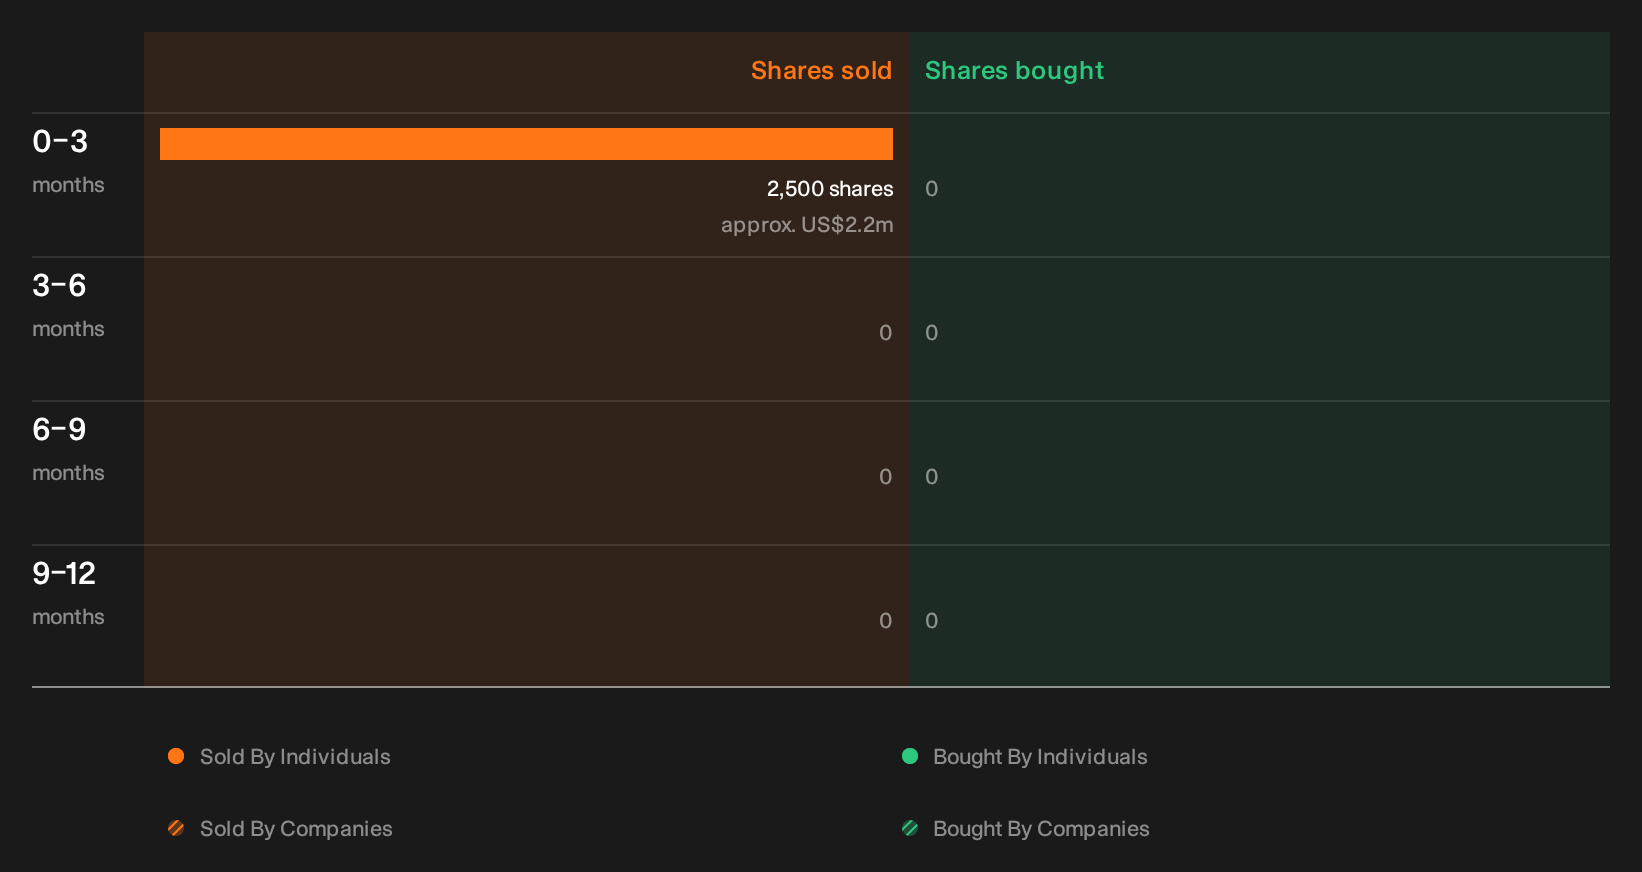
Before you decide how to treat Sterling Infrastructure’s valuation, it is worth checking the recent insider transactions our system has picked up, including who has been selling, how much, and what that might signal. See the recent insider selling flagged for Sterling Infrastructure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com