
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Appier Group (TSE:4180), Why Is The Market Taking A Closer Look?
Recent trading in Appier Group (TSE:4180) has drawn attention after a sharp move over the past 3 months, putting its AI-focused SaaS model and regional revenue mix back under the microscope for investors.
The recent 90-day share price return of 88.79% suggests momentum has been building for Appier Group, even though the 1-year total shareholder return is still down 10.59%. This leaves the current ¥1,516 level looking like a sharp rebound rather than a completed turnaround.
Compare Appier Group's recent rebound with other AI-focused opportunities and scan a curated set of 38 profitable AI stocks that aren't just burning cash.
For Appier Group, that 3 month surge could be read as confidence in its AI SaaS engine, or as traders crowding into a hot theme. Which story does the current valuation reflect?
Price-to-Earnings of 46.1x: Is it justified?
Appier Group is trading on a P/E ratio of 46.1x, which sets a high bar for the current ¥1,516 share price compared with many software peers.
The P/E multiple compares the stock price with earnings per share, so a higher figure usually signals that investors are willing to pay more today for each unit of profit. For an AI-focused SaaS player like Appier Group, that type of premium often reflects expectations for sustained expansion in revenue and profitability rather than current earnings alone.
Analysts currently expect Appier Group's earnings to grow at 31.9% per year, with revenue projected to expand at 19.4% per year, which is faster than the wider JP market forecasts. In that context, the present 46.1x P/E indicates investors are already pricing in a strong earnings path. The estimated fair P/E of 37.5x from the SWS fair ratio model points to a level the market could move toward if enthusiasm cools.
Relative to the JP Software industry average P/E of 18.2x and the peer group average of 27.3x, Appier Group trades at a materially richer valuation, which suggests the market is paying a steep premium for its AI SaaS profile and growth forecasts.
Explore the SWS fair ratio for Appier Group.
Result: Price-to-Earnings of 46.1x (OVERVALUED).
Still, the narrative around Appier Group can shift quickly if high expectations on earnings growth or its concentrated exposure to Northeast Asia begin to look fragile.
Find out about the key risks to this Appier Group narrative.
Another View On Appier Group's Value
The P/E story presents Appier Group as expensive, and the SWS DCF model is even harsher. With a future cash flow value estimate of ¥728.46 against a ¥1,516 share price, the stock appears heavily overvalued on this basis. If the P/E already looks punchy, an important question is what happens if the market places more weight on the cash flow view.
Look into how the SWS DCF model arrives at its fair value.
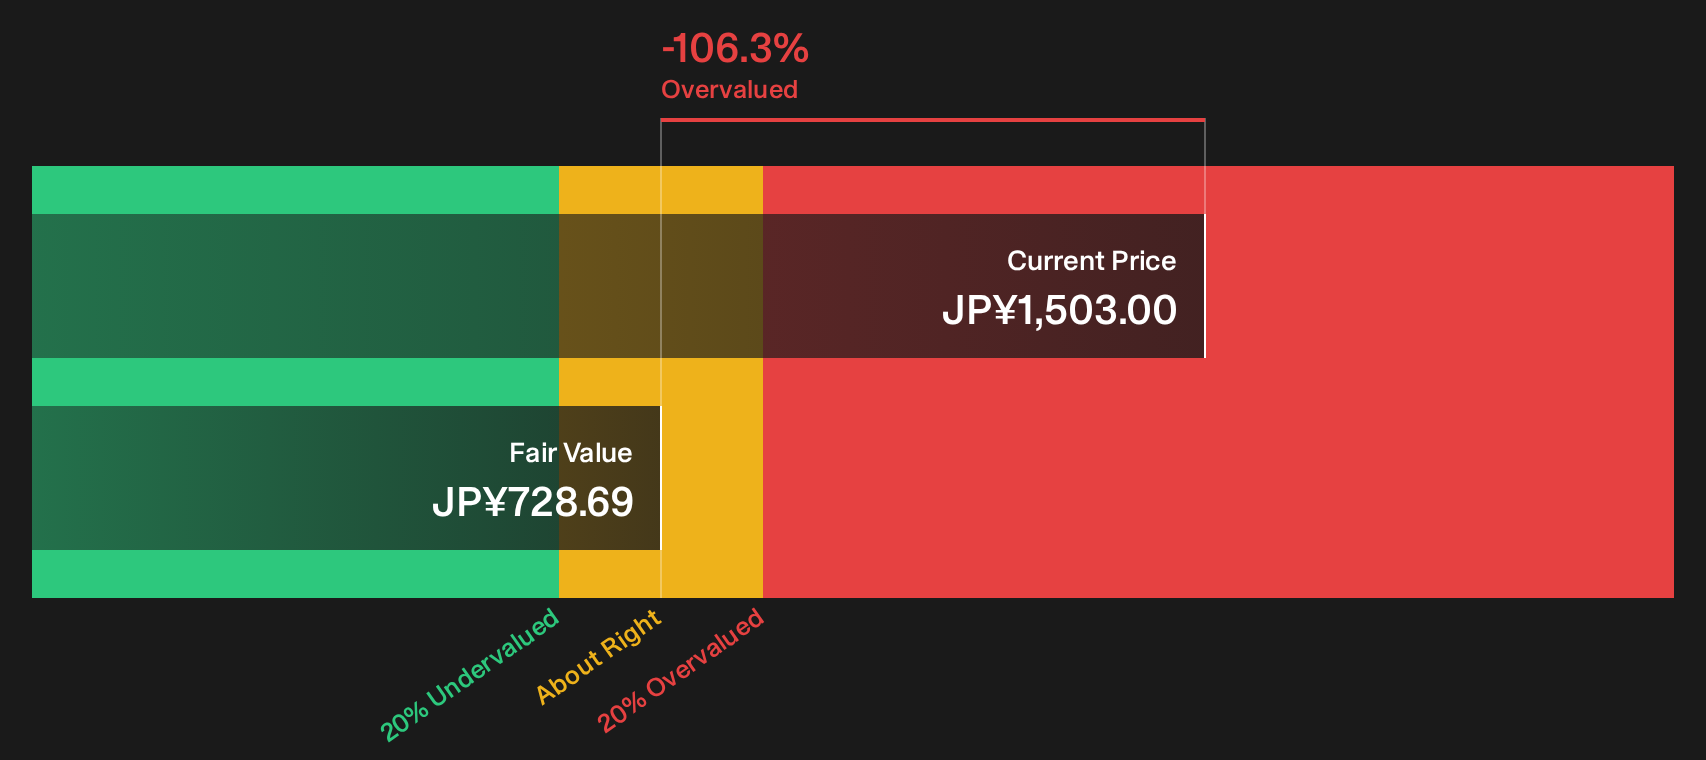
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Appier Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Appier Group can make the story feel conflicted. This is exactly when it can be useful to act quickly and form your own view. To consider both the optimism and the concerns side by side, review the 2 key rewards and 1 important warning sign.
Looking for more Appier Group investment ideas?
Do not stop your research with Appier Group alone. Use the Simply Wall Street Screener to spot fresh opportunities that fit your style before others move first.
- Target potential mispricings by scanning a focused set of 17 high quality undervalued stocks that pair quality fundamentals with market skepticism.
- Prioritise resilience by zeroing in on a list of solid balance sheet and fundamentals (20 results) so you can focus on businesses with sturdier financial foundations.
- Hunt for early-stage potential with a curated group of 1 elite penny stocks with strong financials that already show stronger financial traits than most tiny stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com