
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Northern Star Resources (ASX:NST) Undervalued Following Its Board Refresh?
Northern Star Resources (ASX:NST) has refreshed its board, appointing Mark Cutifani CBE and Peter Rozenauers as independent non executive directors from 1 October 2026. The appointments add extensive mining and investment experience to the board.
Northern Star Resources shares trade at A$22.21 after a 6.42% 90 day share price return, while the year to date share price is down 9.09%. Over a longer stretch, the 1 year total shareholder return of 9.53% and 5 year total shareholder return of 187.84% indicate that returns have varied across different time periods, with shorter term moves remaining mixed.
Scan how Northern Star Resources compares with other gold producers by running through our hand picked 36 elite gold producer stocks while this board refresh is in focus.
Northern Star Resources now trades with a mixed recent record and a refreshed board, which raises a simple tension. Are you seeing a shift in sentiment, or a clearer view of the underlying business value emerging next?
Most Popular Narrative: 7% Undervalued
Northern Star Resources last closed at A$22.21, while the most followed narrative pegs fair value closer to A$23.94. This leaves a modest valuation gap that depends on the execution of its largest projects.
The recent acquisition and progression of the Hemi project, combined with a robust 10-year reserve-backed production profile, offers significant long-term production optionality and ensures continued exposure to increasing wealth and gold consumption in emerging economies, bolstering longer-term revenue prospects.
See why 85 investors see Northern Star Resources as 7% undervalued.
Result: Fair Value of A$23.94 (UNDERVALUED)
Still, the Northern Star Resources story could shift quickly if cost inflation at key sites eats into margins or if major projects face delays or overruns.
Find out about the key risks to this Northern Star Resources narrative.
Another View on Northern Star Resources Valuation
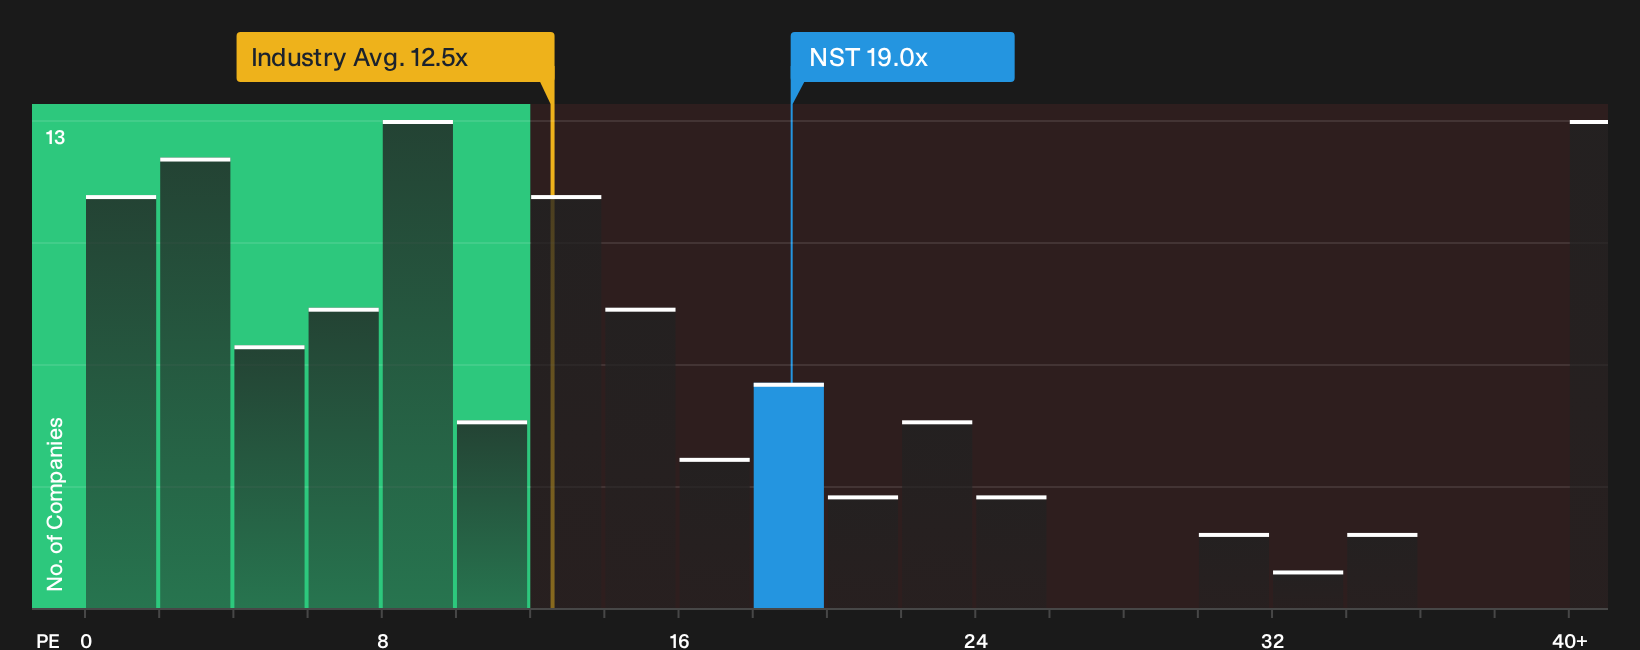
Northern Star Resources looks slightly undervalued against the A$23.94 fair value used in the leading narrative, yet the current P/E of 19x brings a different message. It sits above the Australian Metals and Mining sector at 12.5x, but below a 23.1x fair ratio estimate and a 27.9x peer average.
That mix of richer pricing than the wider industry but cheaper levels than peers and the fair ratio points to real valuation risk if sentiment cools. It also leaves some room for the market to move closer to those higher benchmarks if the story develops in line with current expectations.
See what the numbers say about this price, find out in our valuation breakdown.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment in this Northern Star Resources story is mixed, so treat the numbers as a prompt and not an answer. Act quickly, pull up the key datapoints yourself, and pressure test whether those potential rewards still look compelling once you have reviewed the 2 key rewards.
Looking for more Northern Star Resources style ideas?
If Northern Star Resources has caught your attention, do not stop there. Use the Simply Wall Street Screener to quickly surface fresh opportunities that fit your own criteria.
- Target potential mispricings by scanning a curated 5 high quality undervalued stocks that line up with solid fundamentals and room for sentiment to improve.
- Strengthen your income watchlist by reviewing a focused 3 dividend fortresses that may suit investors who prioritise reliable cash distributions.
- Dial down portfolio stress by checking a 7 resilient stocks with low risk scores that emphasises resilience and more predictable business profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com