
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will $2 Billion Debt Tender Change ONEOK's (OKE) Narrative
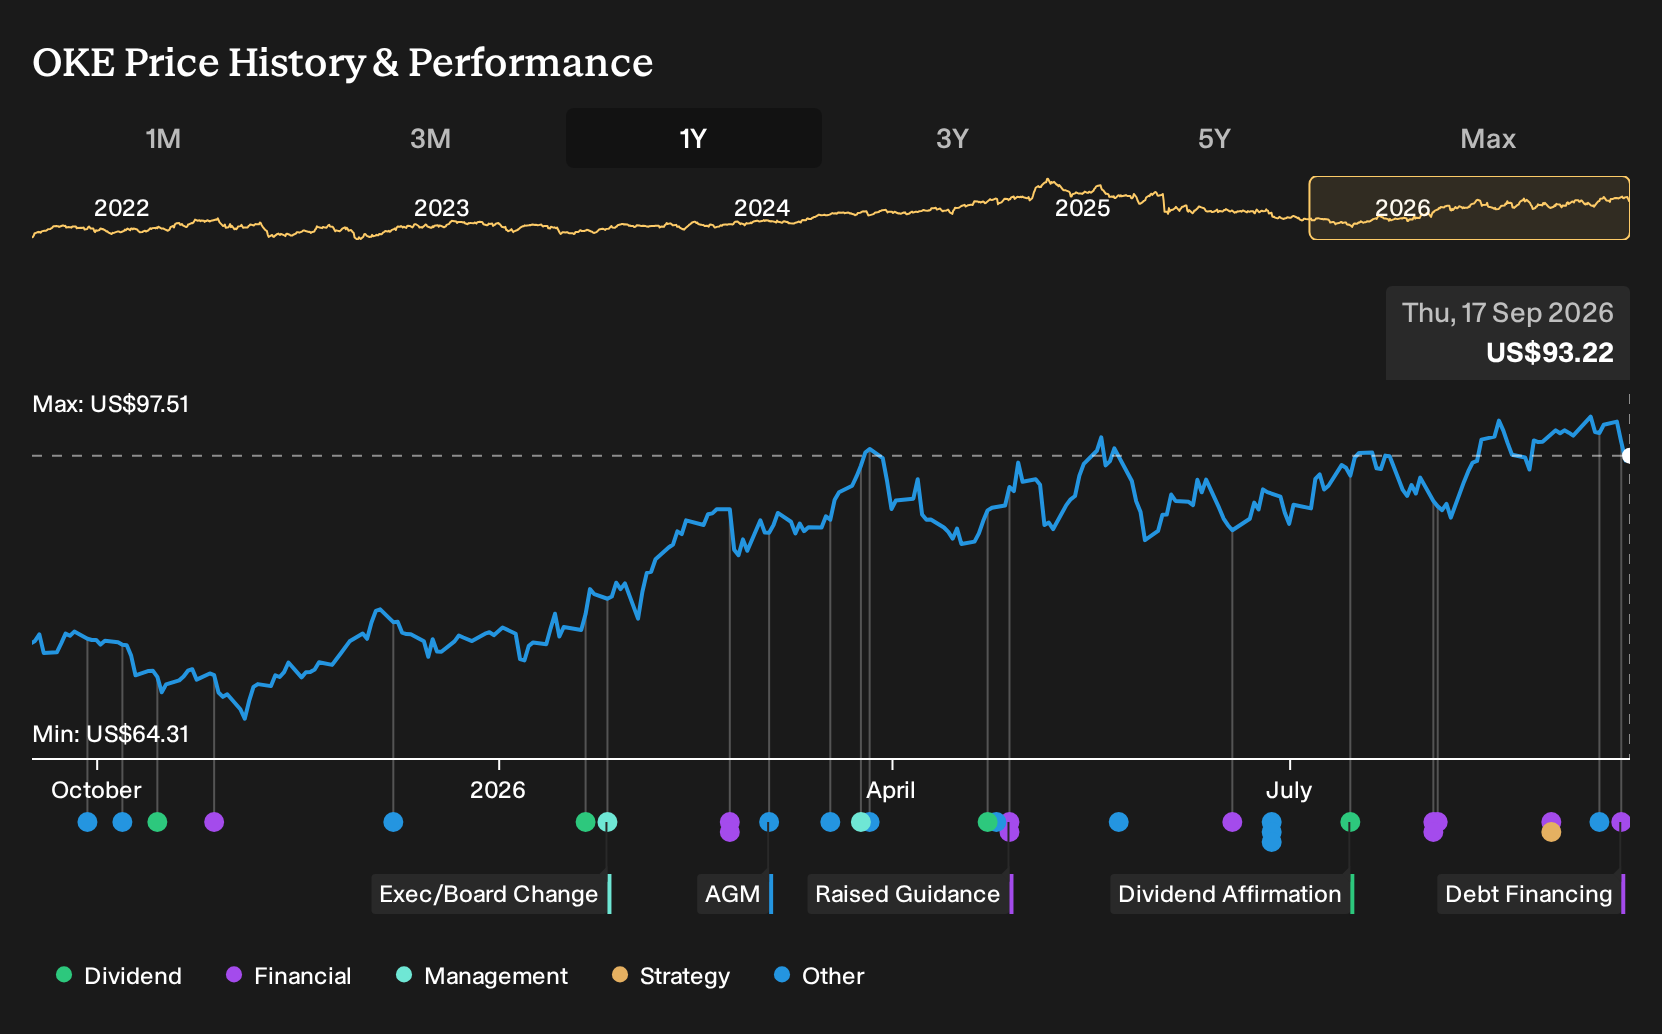
- ONEOK completed a corporate reorganization on September 10, 2026 and launched cash tender offers of up to US$2 billion for a range of senior notes, with early tenders already equaling the maximum aggregate amount.
- The combination of revised Oklahoma governance documents and a large debt repurchase program signals a focus on tighter control over key decisions and potential balance sheet repositioning that could influence long term financing costs.
- This article examines how ONEOK's investment narrative is affected by the reorganization and the US$2 billion debt tender program.
Scan how ONEOK’s debt tender shapes your view on balance sheet strength, and then compare it with a curated list of solid balance sheet and fundamentals (23 results) that could offer similar financial discipline.
ONEOK Investment Narrative Recap
To own ONEOK, you need to be comfortable with a midstream operator that leans heavily on U.S. NGL and natural gas throughput, volume driven earnings and ongoing build out in basins like the Permian. The near term swing factor is execution on these projects while keeping margins steady as commodity spreads stay tight. The fresh US$2b tender does not alter that core thesis in a major way.
The biggest near risk remains leverage and cash coverage, since debt is not well covered by operating cash flow and the dividend is only partly backed by free cash generation. If commodity volatility persists or integration from recent acquisitions disappoints, pressure on net margins and capital flexibility becomes more important than the tender itself.
The debt tender announcement is the key development here. ONEOK is offering to repurchase up to US$2b of senior notes across a wide maturity range, with early tenders already matching the maximum. Those securities are now fully and unconditionally guaranteed by ONEOK after the reorganization, which ties the liability profile more tightly to the listed parent.
For you as a shareholder, this sits at the intersection of potential catalysts and key risks. Execution on this tender could influence future interest costs, financial flexibility and how quickly management can respond to weak commodity spreads or slower volume growth. It also interacts directly with existing concerns that leverage and operating cash coverage remain watch points rather than settled issues.
ONEOK's narrative projects US$40.4b revenue and US$4.4b earnings by 2029. This implies fairly flat yearly revenue trends and an earnings increase of about US$0.7b from current earnings of roughly US$3.7b, based on the current analyst consensus.
Uncover why ONEOK's fair value indicates an 8% potential upside to its current price that could close faster than many investors expect.
Exploring Other Perspectives
One alternate view on ONEOK puts long term demand risk front and center. The most cautious analysts were modeling revenue at about US$27.2b and earnings near US$3.8b by 2029, well below the consensus path. You can treat this US$2b debt tender and tighter Oklahoma control as fresh information that may shift those expectations over time.
Explore 6 other ONEOK fair value estimates, including one that indicates as much as 7% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your ONEOK research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ONEOK. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ONEOK's overall financial health at a glance.
Looking for more investment ideas beyond ONEOK?
Once you have a clear view on ONEOK, it can help to set it in context by scanning other businesses with different balance sheet profiles, payout policies and valuation setups using the Simply Wall St Screener.
- If capital preservation sits high on your list, compare ONEOK with a group of companies screened for resilient fundamentals through a 30 resilient stocks with low risk scores.
- If value is your main focus, line ONEOK up against a curated 29 high quality undervalued stocks and see which businesses stack up more attractively on quality and price.
- If steady cash returns matter most to you, weigh ONEOK's payout against a hand picked group of income ideas drawn from a 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com