
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Premium Toothpaste Push Change Colgate's (CL) Narrative
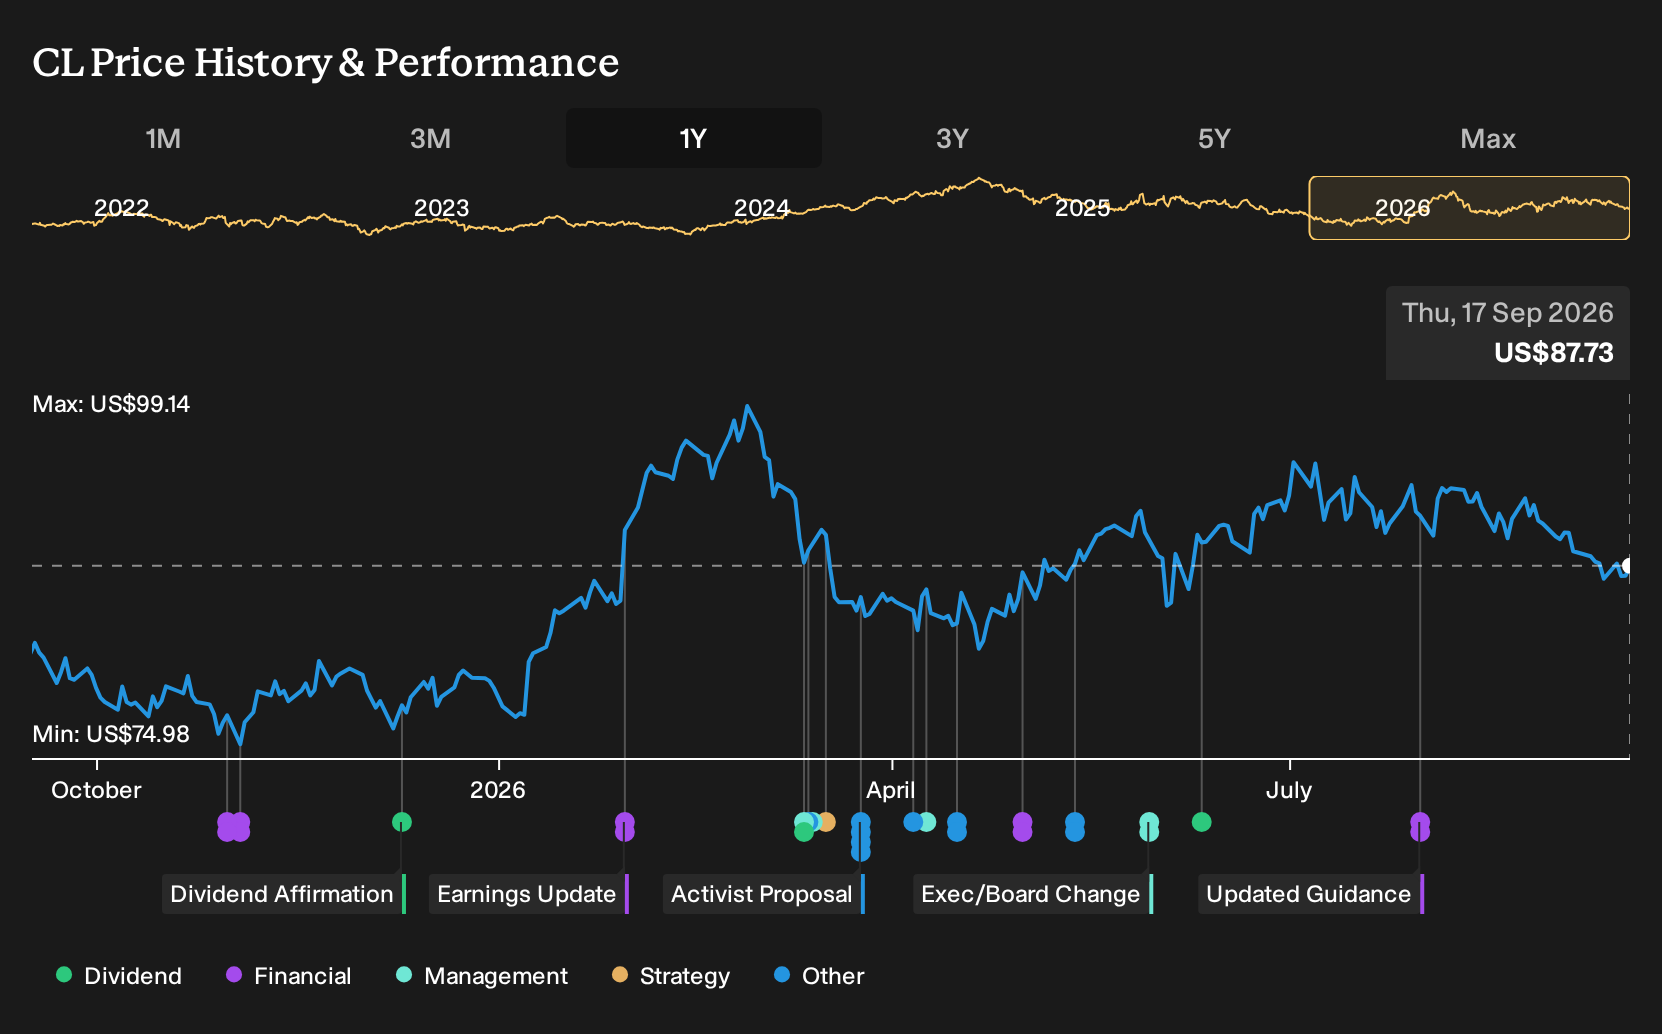
- Colgate-Palmolive's board declared a quarterly cash dividend of $0.53 per share, paid in November 2026, extending an uninterrupted payment record on its common stock that began in 1895.
- Management is pairing this long-running dividend commitment with increased support for premium toothpaste and higher advertising in North America as it works through recent category softness and tougher competition.
- We will now assess how Colgate-Palmolive's investment narrative could be influenced by this renewed advertising push behind premium toothpaste.
Scan beyond Colgate-Palmolive to compare its renewed dividend commitment and brand investment with a handpicked 6 dividend fortresses that also pairs income with resilient business models.
Colgate-Palmolive Investment Narrative Recap
To own Colgate-Palmolive, you need to believe its everyday brands in oral care and pet nutrition can keep pulling in steady demand even when consumers become more price sensitive. In the near term, a key issue is whether the premium toothpaste push and higher advertising can firm up North America after recent category softness.
The biggest risk right now is that cautious shoppers trade down or stick with private labels, limiting how much Colgate-Palmolive can rely on premium tiers to support margins while raw material costs remain a swing factor. The fresh dividend affirmation itself does not materially change that near-term operating story.
The most relevant announcement here is the September 17 dividend declaration of a US$0.53 quarterly payout, extending a record of uninterrupted dividends since 1895. For you as a shareholder, that highlights management’s willingness to keep returning cash while the business absorbs higher marketing spend and works through weaker recent profit margins.
This matters for potential catalysts because the dividend commitment sits alongside plans to increase support for premium toothpaste, adjust selective pricing and invest more in advertising. Execution risk is clear. Colgate-Palmolive has to fund this higher spend from operations while dealing with high debt, past one-off charges and pressure on its 9.7% net margin.
Colgate-Palmolive's current analyst story points to revenues of US$23.1b and earnings of US$3.4b by 2029. This implies revenue growth of 3.2% per year and an earnings increase of US$1.4b from the US$2.0b reported today.
Uncover why Colgate-Palmolive's fair value indicates a 13% potential upside to its current price that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly US$86 to US$128, so one group of retail investors sees Colgate-Palmolive as close to its current price, while others attach a much richer label. Set that against risks around raw material costs and consumer caution, then explore these alternative views for yourself.
Explore 3 other Colgate-Palmolive fair value estimates, including one that suggests the potential for as much as 46% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Colgate-Palmolive research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Colgate-Palmolive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colgate-Palmolive's overall financial health at a glance.
Looking For More Investment Ideas Beyond Colgate-Palmolive?
Once Colgate-Palmolive is on your radar, it can help to widen the lens and compare it with other businesses that match your income, quality or risk preferences. The Simply Wall St Screener lets you jump straight to focused shortlists rather than wading through hundreds of tickers.
- If you want income with staying power, scan a curated group of resilient payers through the 6 dividend fortresses.
- For investors hunting for quality at a sensible entry point, filter for opportunities trading below their assessed value using the 29 high quality undervalued stocks.
- If balance sheet strength is your priority, start with a list of solid balance sheet and fundamentals (23 results), which aims to put financial resilience front and center in your research.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com