
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Benchmark Electronics (BHE) Could Be 13% Undervalued On Strong Q2 And Upbeat Guidance
Benchmark Electronics (BHE) has reaffirmed its quarterly dividend at $0.17 per share, following Q2 results that topped analyst expectations on both revenue and earnings and guidance that ran ahead of forecasts.
At a share price of $74.55, Benchmark Electronics has seen strong momentum this year, with a year to date share price return of 69.82% and a 1 year total shareholder return of 85.22%. However, the 90 day share price return has declined 19.12% as expectations reset around the recent run up and Q2 news.
Scan for other companies showing similar earnings momentum and dividend support using our hand picked list of 16 high quality undiscovered gems.
Benchmark Electronics now combines a solid operating story with a sharp pullback in the share price. The business appears strong. The open question is whether that recent reset leaves the stock priced fairly or stretched.
Most Popular Narrative: 13.3% Undervalued
Benchmark Electronics is trading at $74.55 against a widely followed fair value estimate of $86, which sets up a story built on higher growth expectations, richer margins and a higher future earnings multiple than the market is currently assigning.
Benchmark is positioned to benefit from the surging demand for advanced computing and AI infrastructure, as evidenced by recent contract wins in water-cooling for high-performance computing and AI data centers, and ramping opportunities expected to drive a return to revenue growth in AC&C by late 2025 and into 2026. This supports both revenue acceleration and an upward mix in gross margin due to the complexity of these projects.
See why 6 investors see Benchmark Electronics as 13% undervalued.
Result: Fair Value of $86 (UNDERVALUED)
Still, the bullish Benchmark Electronics story could fray if semi-cap demand stays weak for longer, or if AC&C program ramps arrive later than analysts expect.
Find out about the key risks to this Benchmark Electronics narrative.
Another View: Benchmark Electronics Through The P/E Lens
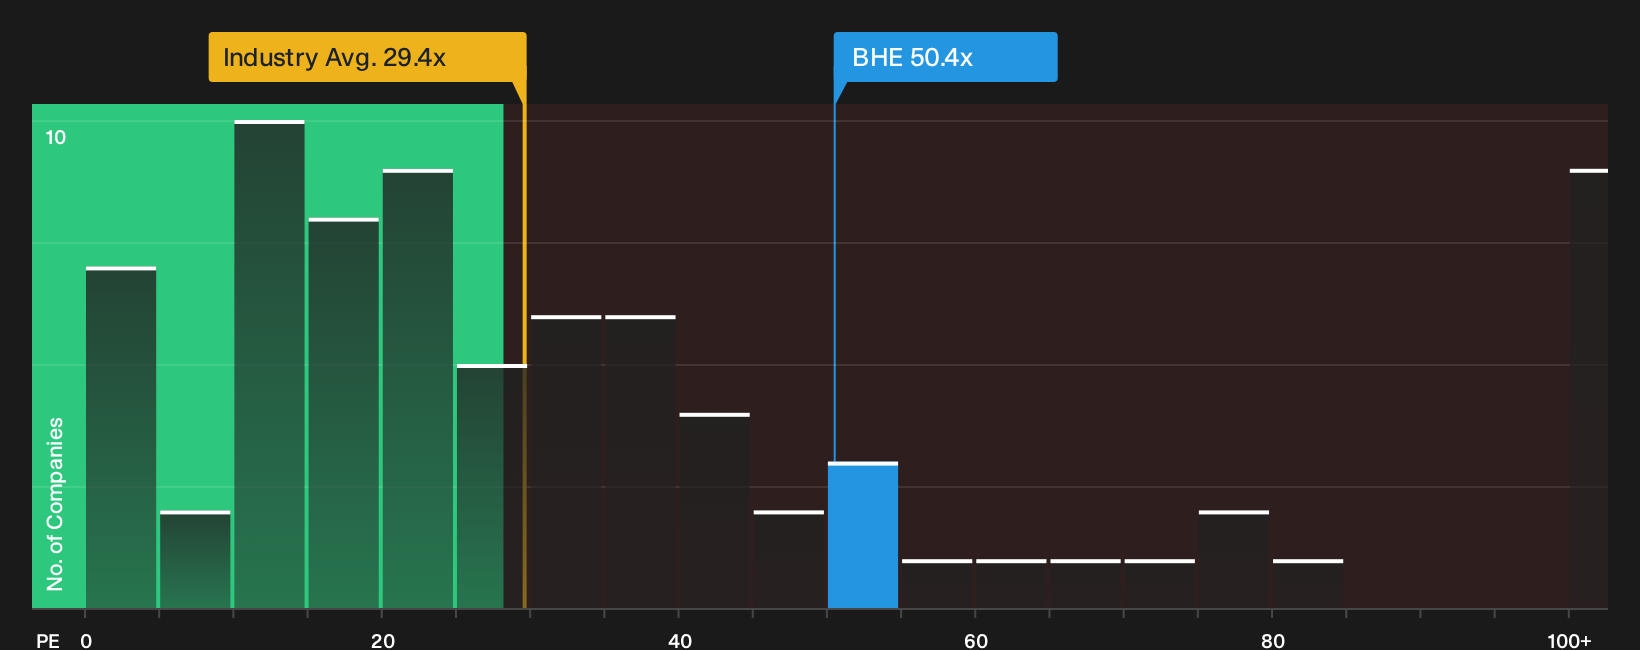
The first fair value story for Benchmark Electronics leans on growth and margin improvement. A simple P/E check paints a tougher picture. The stock trades on 50.4x earnings, above the estimated fair ratio of 33.6x, the US Electronic industry on 29.7x, and peers at 49.5x.
That kind of premium can signal confidence in the earnings outlook, yet it also means less room for error if growth or margins fall short. When the current multiple already exceeds what the fair ratio suggests the market could move toward, it raises a question: how comfortable are you paying up for this narrative to play out?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Benchmark Electronics is split, with clear strengths and clear concerns sitting side by side, so move quickly and review the full picture yourself. To weigh both sides of the argument in one place, start with our breakdown of 2 key rewards and 1 important warning sign.
Looking for more Benchmark Electronics style investment ideas?
If Benchmark Electronics has sharpened your focus, do not stop here. Broaden your opportunity set with targeted stock ideas built from the Simply Wall St screener.
- Target potential mispricings by reviewing a curated set of companies that screen as strong value opportunities through the 29 high quality undervalued stocks.
- Prioritise resilience by checking companies with robust financial footing and cleaner balance sheets using the list of solid balance sheet and fundamentals (23 results).
- Focus on stability and income by assessing businesses that offer higher yields and consistent shareholder payouts in the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com