
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Value Stock Backing Require Action From Subsea 7 (OB:SUBC) Investors?
- Subsea 7 has recently been highlighted as a value-focused offshore contractor, with metrics such as P/E and P/B suggesting the shares trade below sector averages despite a solid operational footing in complex subsea work.
- An additional point of interest for investors is that this value case aligns with an earnings outlook already shaped by long-cycle offshore contracts and renewables exposure, which links market commentary directly to fundamentals rather than short-term sentiment.
- We will now consider how Subsea 7's investment narrative could be influenced by renewed attention on its valuation metrics and earnings outlook.
Look beyond Subsea 7 and compare its value story against hand-picked peers by checking out the 169 high quality undervalued stocks with solid cash flows and balance sheets.
Subsea 7 Investment Narrative Recap
To own Subsea 7, you need to be comfortable with a business tied to complex offshore energy projects, long contract cycles, and sizeable capital commitments. The key short term swing factor is how efficiently those contracts translate into margins and cash flow, given vessel utilization and project mix. The latest value focused news does not materially alter that operational reality.
The biggest near term risk still sits with project and competitive pressure. Tight bidding in markets like Brazil, uncertain renewables activity outside the UK, and exposure to seasonal margin swings can all squeeze profitability. The valuation attention simply sharpens how closely execution on this backlog will be watched.
The recent focus on Subsea 7’s P/E, P/B, and value credentials connects directly to its existing order book and earnings profile. A backlog near US$12b and quarterly order intake of about US$2.5b already underpin revenue visibility. Any shift in how investors view those valuation ratios will likely hinge on whether that contracted work sustains current profitability levels.
Existing commentary around margin strength, including EBITDA margin above 20%, and a growing renewables contribution gives this value story an operational anchor. The Saipem merger proposal and ongoing offshore wind exposure remain important execution tests. If project delivery, vessel utilization, and merger related risks are managed well, the current value narrative has clear catalysts to track.
Subsea 7's narrative projects US$7.9b revenue and US$779.2m earnings by 2029, based on analysts assuming 2.5% yearly revenue growth and an earnings increase of about US$286m from US$493.0m today.
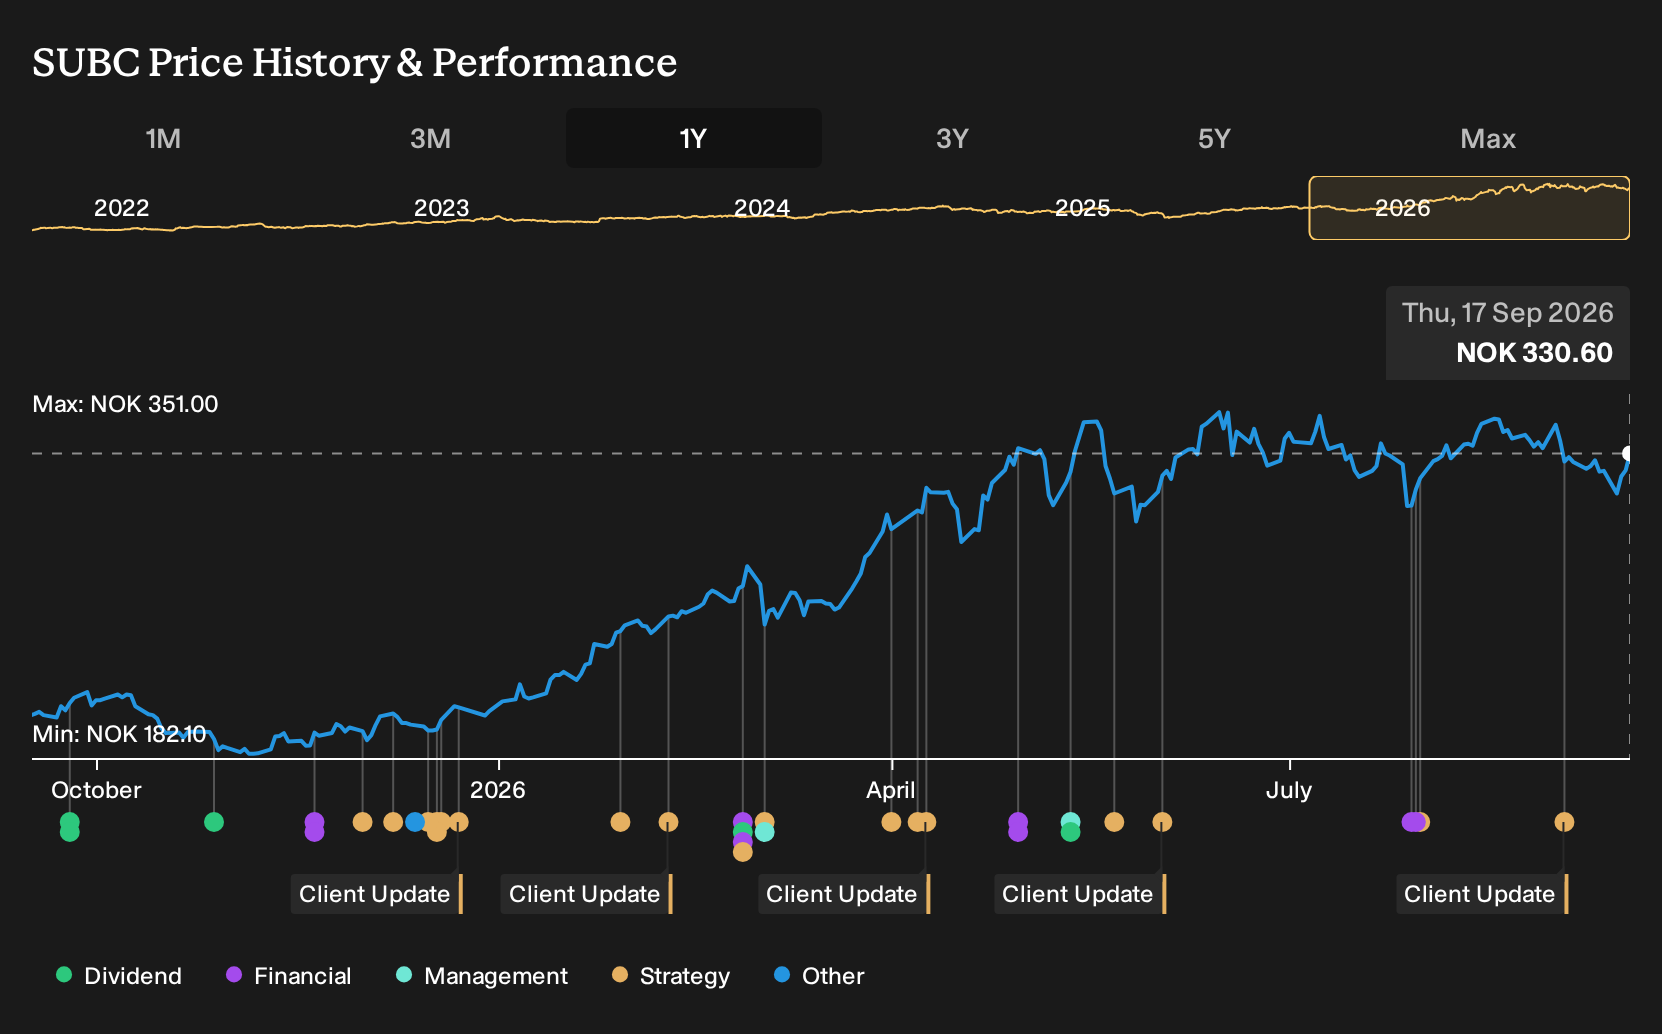
Discover why Subsea 7's fair value suggests a 7% potential upside to its current price before sentiment closes that discount.
Exploring Other Perspectives
One alternate view on Subsea 7 leans hard into decarbonization risk. Under that lens, some analysts were already pencilling in revenue of about US$7.0b and earnings of roughly US$477.3m by 2029, well below consensus. That more cautious camp may reassess after this value focused news, and investors may wish to compare both narratives themselves.
Explore 4 other Subsea 7 fair value estimates, including one that suggests as much as 29% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Subsea 7 research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Subsea 7. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, which makes it easy to evaluate Subsea 7's overall financial health at a glance.
Looking For More Investment Ideas Beyond Subsea 7?
Once you have formed a view on Subsea 7, it can help to set that thesis against a wider watchlist of opportunities with different risk and income profiles.
- For investors who care most about balance sheet strength and financial resilience, consider starting with this list of solid balance sheet and fundamentals (70 results) that filters for companies with robust fundamentals.
- If capital protection and smoother portfolio swings matter to you, focus on a basket of businesses highlighted in our 227 resilient stocks with low risk scores and compare their risk scores against what you see in Subsea 7.
- Those hunting for mispriced quality can broaden their search using a curated 616 high quality undiscovered gems that points to companies with strong fundamentals that are not yet widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com