
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Government Radio Orders Change The Bull Case For OSI Systems Stock (OSIS)?
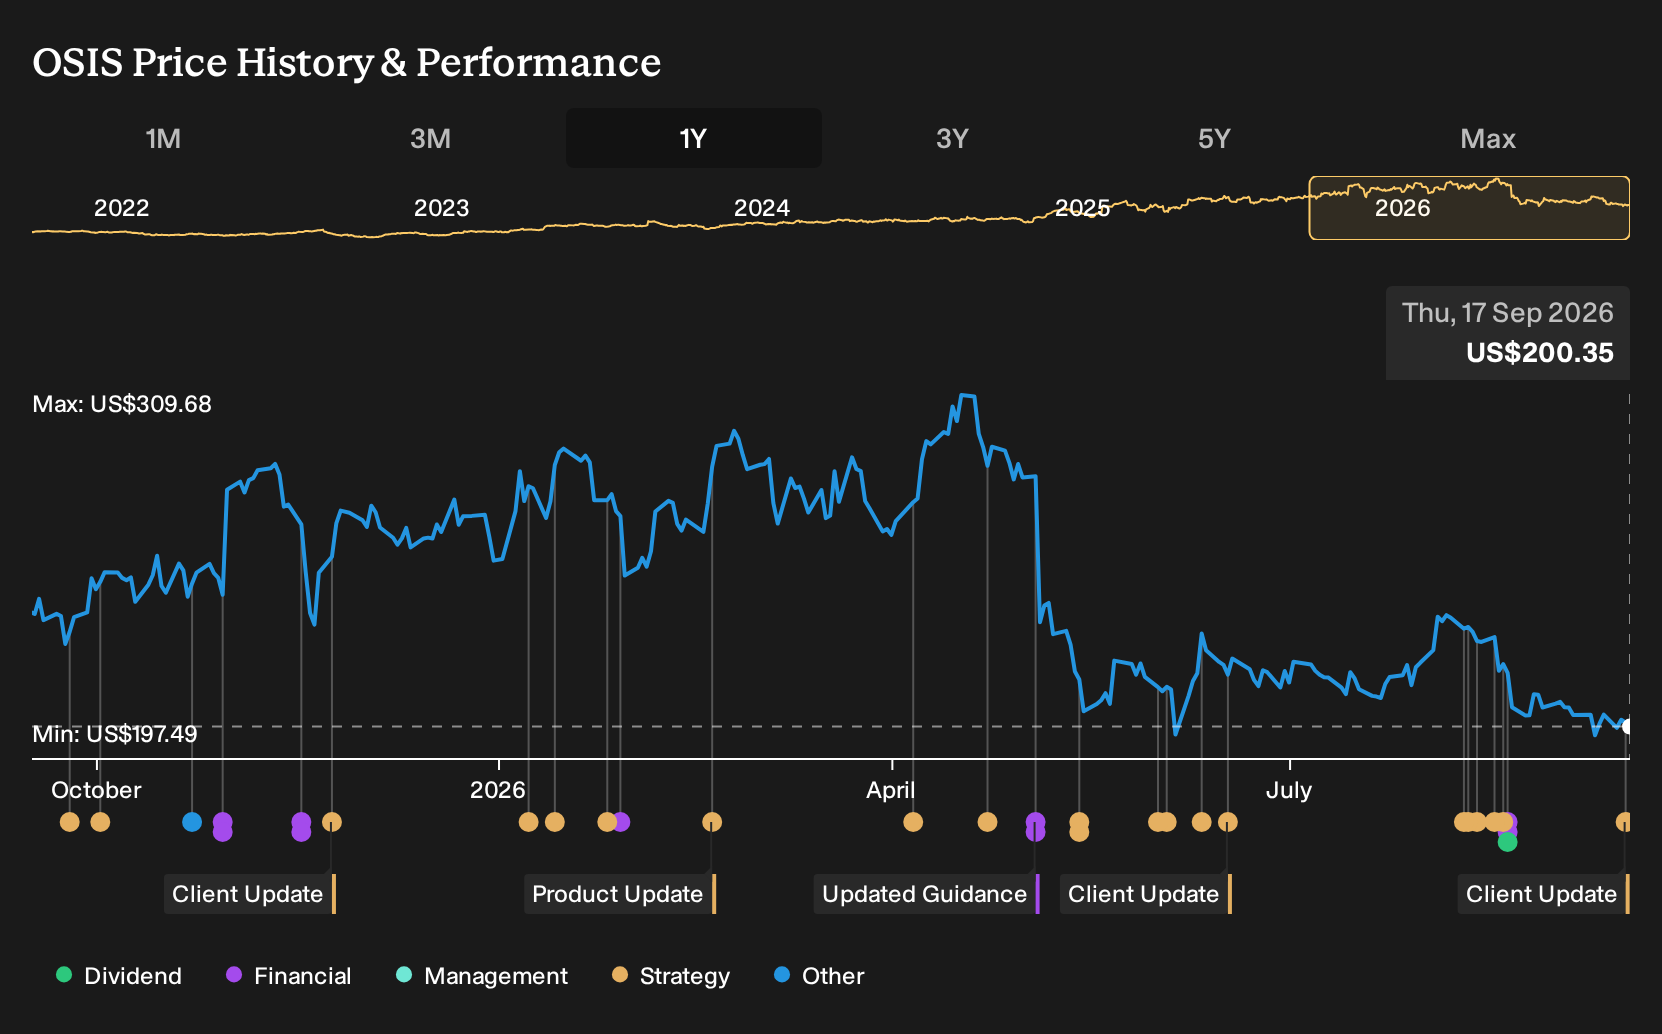
- OSI Systems reported that, earlier this week, its Security division received about US$90 million in U.S. Government orders for RF communication products and its Optoelectronics and Manufacturing unit secured roughly US$8 million of electronic assembly work from a global industrial technology client.
- The twin order wins highlight OSI Systems' exposure to government infrastructure programs and its ability to supply complex assemblies across multiple industrial product lines and geographies.
- Now the focus shifts to how OSI Systems' investment narrative aligns with large U.S. RF communication contracts that deepen government-driven revenue exposure.
OSI Systems Investment Narrative Recap
For OSI Systems, the core belief is that government security spending and industrial demand can keep feeding a healthy backlog across Security and Optoelectronics while management handles working capital swings and debt sensibly. The fresh US$98 million of orders supports the near term revenue pipeline, although it does not remove the longer term reliance on concentrated government budgets and large projects.
In the short term, the key swing factor remains execution on big security contracts and converting backlog into cash without putting strain on receivables. The main risk stays the same: heavy exposure to sovereign customers and higher leverage could pressure cash flow if payments slow or if new awards do not land in step with existing programs.
The US$90 million RF communication order from U.S. Government customers looks most relevant for assessing OSI Systems today. It fits directly into the existing thesis around multi year security and infrastructure funding and reinforces the firm’s role in Very Low Frequency and high frequency systems that support communication upgrades and sustainment work.
In terms of potential catalysts, that award increases visibility on Security division workload and related service opportunities, which matters for margins and backlog quality. It does not eliminate concerns around lumpiness, political risk or R&D focus, so execution on delivery, cost control and follow on contracts will likely shape how much investors credit this order in future results.
OSI Systems' current analyst narrative points to revenues of US$2.2b and earnings of US$229.1 million by 2029, based on a projected 7.1% yearly revenue growth rate and an earnings increase of about US$74.4 million from US$154.7 million today.
Uncover why OSI Systems' fair value indicates a 40% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly US$79 to US$281 per share, so private investors are assigning very different futures to OSI Systems. When you set those divergent views against the reliance on large government contracts and potential service driven opportunities, you get a wide field of possible outcomes that makes it worthwhile to check multiple viewpoints yourself.
Explore 2 other OSI Systems fair value estimates, including one that suggests as much as 61% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your OSI Systems research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OSI Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OSI Systems' overall financial health at a glance.
Looking For More Ideas Beyond OSI Systems?
If you want to put OSI Systems in context and spot other potential opportunities, it helps to scan a broader watchlist of businesses with different strengths and risk profiles.
- For readers who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (23 results) that match that profile.
- If your priority is valuation and you want to see where quality and price expectations intersect, compare OSI Systems with 29 high quality undervalued stocks that currently screen well on fundamentals.
- Income focused investors may want to balance OSI Systems' story with steadier cash return profiles, so consider a set of 6 dividend fortresses that offer higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com