
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Acushnet Holdings (GOLF) Slides As Undervalued Calls Persist, Is The Premium Still Justified?
Acushnet Holdings (GOLF) is under renewed scrutiny after a recent pullback, with the share price down about 9% over the past month and roughly 24% over the past 3 months.
The recent slide in Acushnet Holdings’ share price has softened short term momentum, yet the latest close at US$81.55 still sits against a backdrop of positive total shareholder return of 9.11% over one year and 72.58% over five years. This suggests that recent weakness reflects shifting sentiment on near term risks rather than a clear reset of the longer term story.
Compare Acushnet Holdings with other golf and consumer brands that have pulled back recently yet still screen well on fundamentals through our curated list of solid balance sheet and fundamentals (23 results).
Acushnet Holdings now sits in an awkward spot where a 24% three month slide clashes with steady multi year shareholder gains. Is the latest drop pointing to cracks in the business, or just a reset in sentiment as valuation drifts lower?
Most Popular Narrative: 19% Undervalued
Against the latest close at $81.55, the most followed narrative pegs Acushnet Holdings fair value at $100.40, which implies meaningful upside in the model and raises the question of whether the recent pullback has moved the stock below what its cash generation and growth assumptions would support.
The analysts have a consensus price target of $100.4 for Acushnet Holdings based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be $2.9 billion, earnings will come to $279.5 million, and it would be trading on a PE ratio of 26.1x, assuming you use a discount rate of 7.6%.
See why 3 investors see Acushnet Holdings as 19% undervalued.
Result: Fair Value of $100.40 (UNDERVALUED)
Still, if golfer participation or rounds played slip, or consumer spending tightens, the bullish Acushnet Holdings narrative could reset faster than models imply.
Find out about the key risks to this Acushnet Holdings narrative.
Another View: Multiples Paint A Tougher Picture For Acushnet Holdings
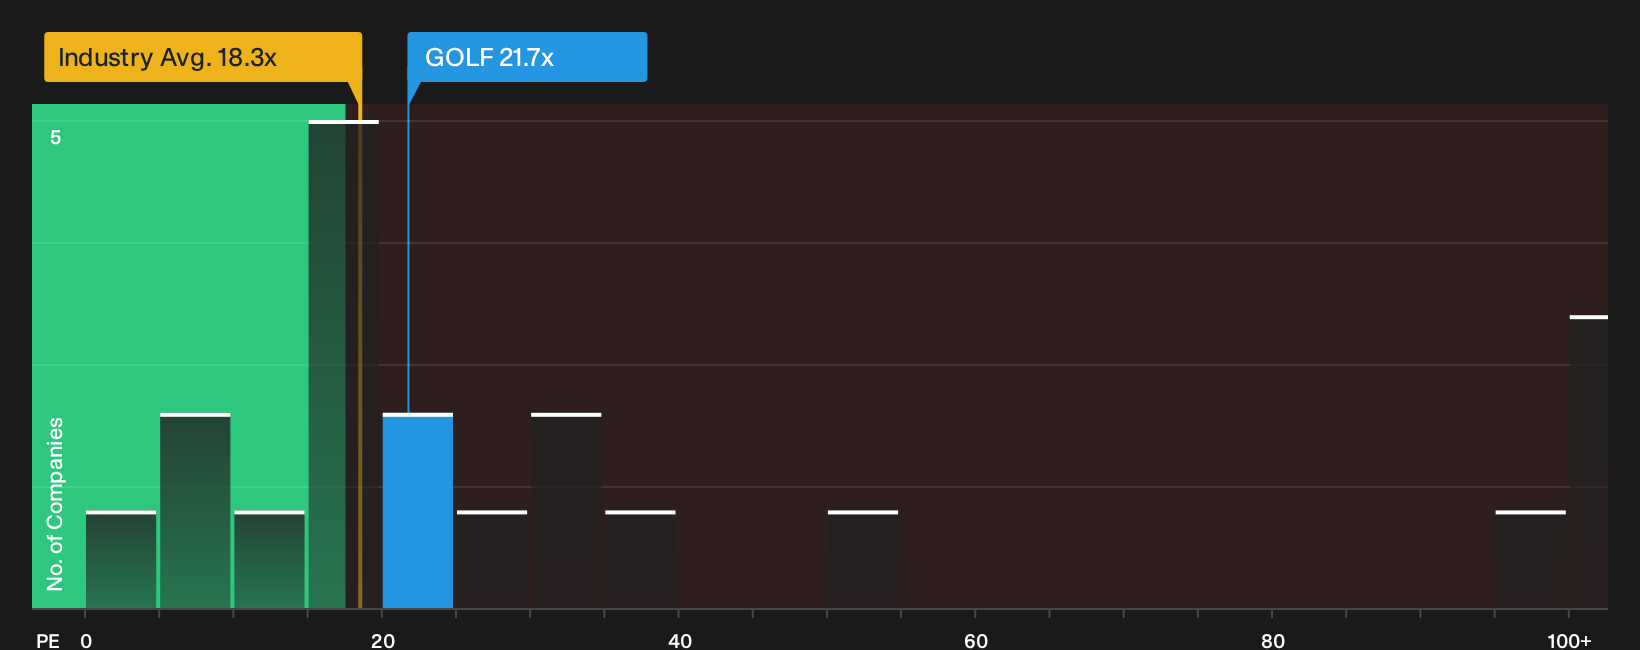
The story flips when you look at Acushnet Holdings through a simple earnings multiple. The stock trades on a P/E of 21.7x, compared with 17.7x for the global Leisure group and 18.9x for peers, while the fair ratio sits lower again at 15.3x.
That spread suggests the market is already paying a premium for GOLF that could compress if sentiment cools, even with other models flagging undervaluation. Which yardstick do you trust most when the signals point in different directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals across Acushnet Holdings can feel confusing, so consider reviewing the same data yourself and weighing both the upside and downside through 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Acushnet Holdings?
If Acushnet Holdings has your attention, do not stop here. Spread your research across other opportunities so one story never defines your whole portfolio.
- Target dependable income by scanning companies that aim to combine yield with resilience through the 6 dividend fortresses.
- Hunt for mispriced quality where strong fundamentals and reasonable valuations intersect using the 29 high quality undervalued stocks.
- Prioritise capital protection by focusing on businesses that show sturdier financial footing with the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com