
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Financial Stocks Investors Are Watching As Volatility Lifts Demand For Income
Central banks are hinting at tighter policy, volatility is picking up and investors are rethinking where to park long term capital. That mix can punish some stocks and create rare openings in others as risk gets repriced and income streams look more valuable. This article walks through three diversified banks and fixed income asset managers from our screener that appear positively exposed to these shifts, and explains what their business models might mean for your portfolio decisions.
The three stocks below are a sample from this theme. The full screen surfaces nine more large banks and fixed income managers with equally compelling stories that are not covered here.
If you want to identify which of these global players best fits your risk, income, and valuation preferences right now, head straight into the Global Diversified Banks & Fixed-Income Asset Managers screener.
Banco BBVA Argentina (BASE:BBAR)
Overview: Banco BBVA Argentina is a full-service Argentine bank that provides retail, commercial, corporate and investment banking plus asset management.
Operations: BBVA Argentina generates ARS 3.19b in revenue entirely from banking activities within Argentina, making it a domestically focused lender.
Market Cap: ARS 4.72t
For a screener built around global diversified banks and fixed-income players, Banco BBVA Argentina offers a pure play on traditional lending, deposits and cash management in a rate sensitive market, with a growing digital footprint that matters when policy tightening reshapes how customers handle money.
"Although BBVA Argentina's investment in digital transformation has enabled growth in digital customer acquisition and operational efficiencies that may support net margin improvement, the rapid advance of agile fintech competitors may accelerate disintermediation, particularly among younger or underbanked segments, which could limit fee-based income and slow customer growth over time."
What happens to Banco BBVA Argentina’s earnings profile if a single pressure point quietly shifts the balance between pricing power and credit risk?
That tipping point is exactly what the full narrative for Banco BBVA Argentina unpacks, showing where digital momentum, pricing power and credit risk may be quietly decoupling.

Man Group (LSE:EMG)
Overview: Man Group is a global investment manager focused on fixed-income and alternative strategies that help clients respond to higher yields and rising volatility.
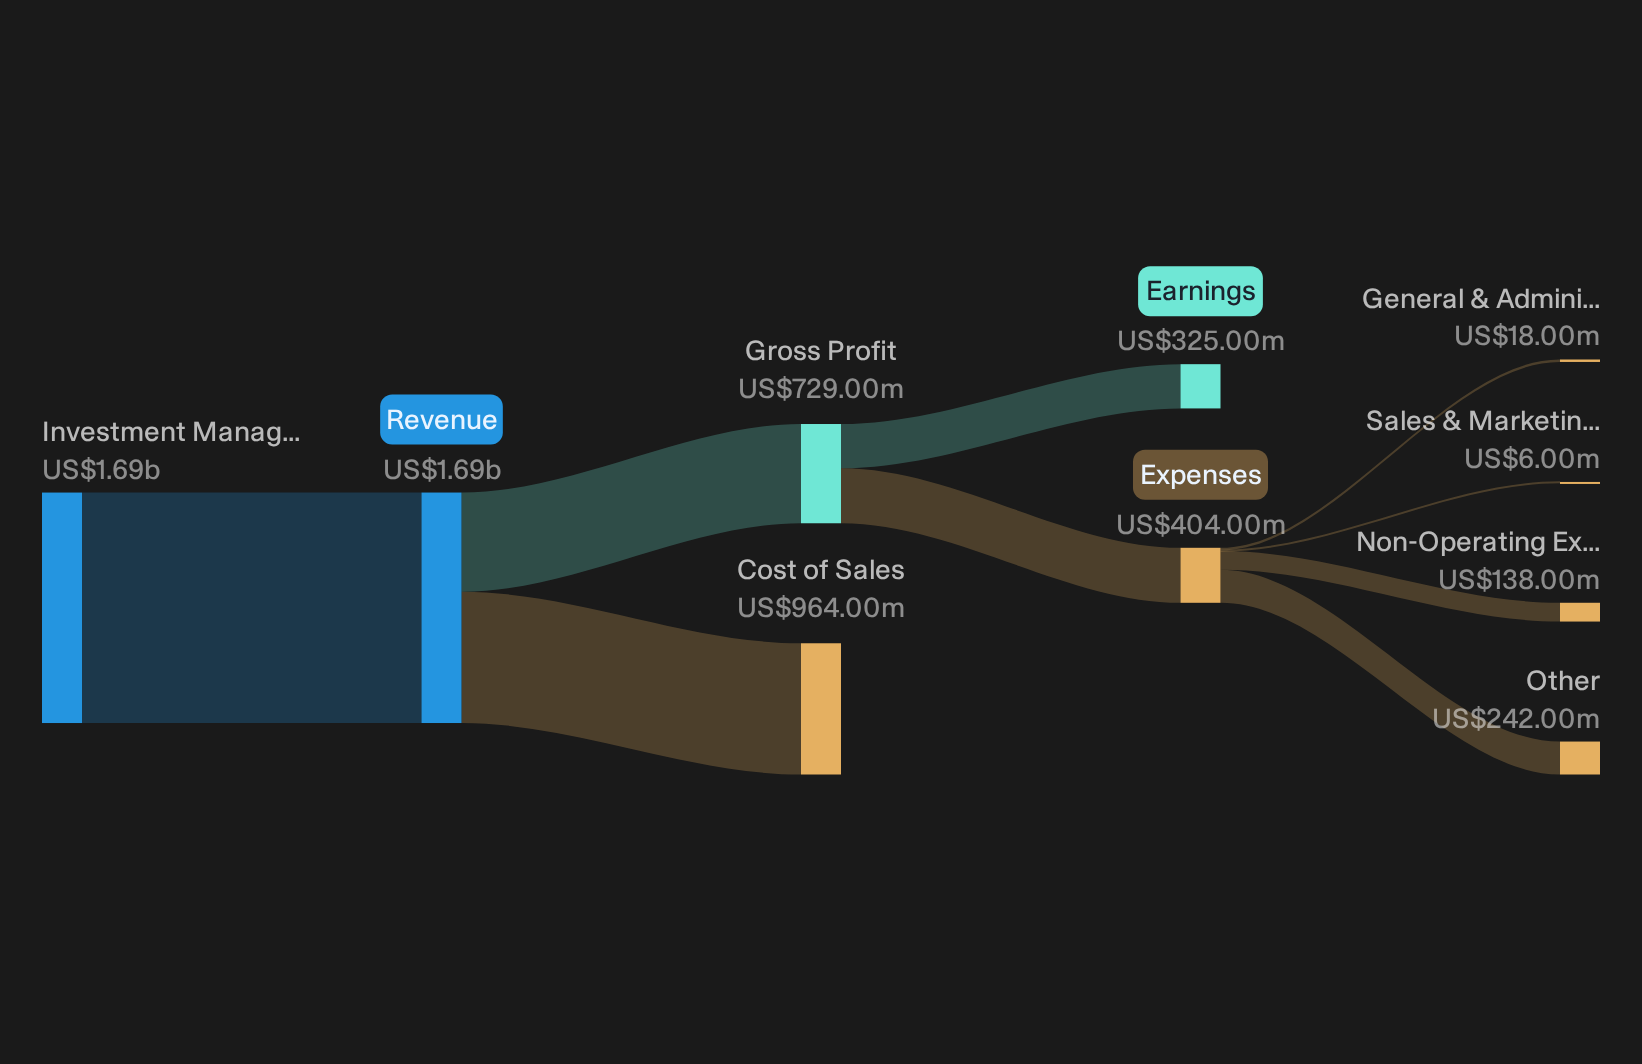
Operations: Man Group generates about US$1.69b in revenue from its Investment Management Business, built around liquid strategies across multiple asset classes.
Market Cap: £3.73b
Man Group matters for this screener because its fixed-income and alternatives toolkit sits exactly where clients turn when rates climb and volatility reshapes how institutions think about risk and income.
"The accelerating adoption of passive, low-fee investment solutions such as ETFs continues to undercut the appeal of actively managed and alternative products like those offered by Man Group, threatening to erode their ability to attract and retain assets over time, which risks stagnating or shrinking future revenue streams."
The main uncertainty is what happens to Man Group’s earnings power if one quiet shift in client fee mix continues to grind away at margins.
If that margin grind is what keeps you cautious, the full narrative for Man Group shows where fee pressure, performance and new product momentum may still be mispriced.
Akbank T.A.S (IBSE:AKBNK)
Overview: Akbank T.A.S is a large Turkish bank providing retail, commercial and corporate banking, plus treasury and asset management services.
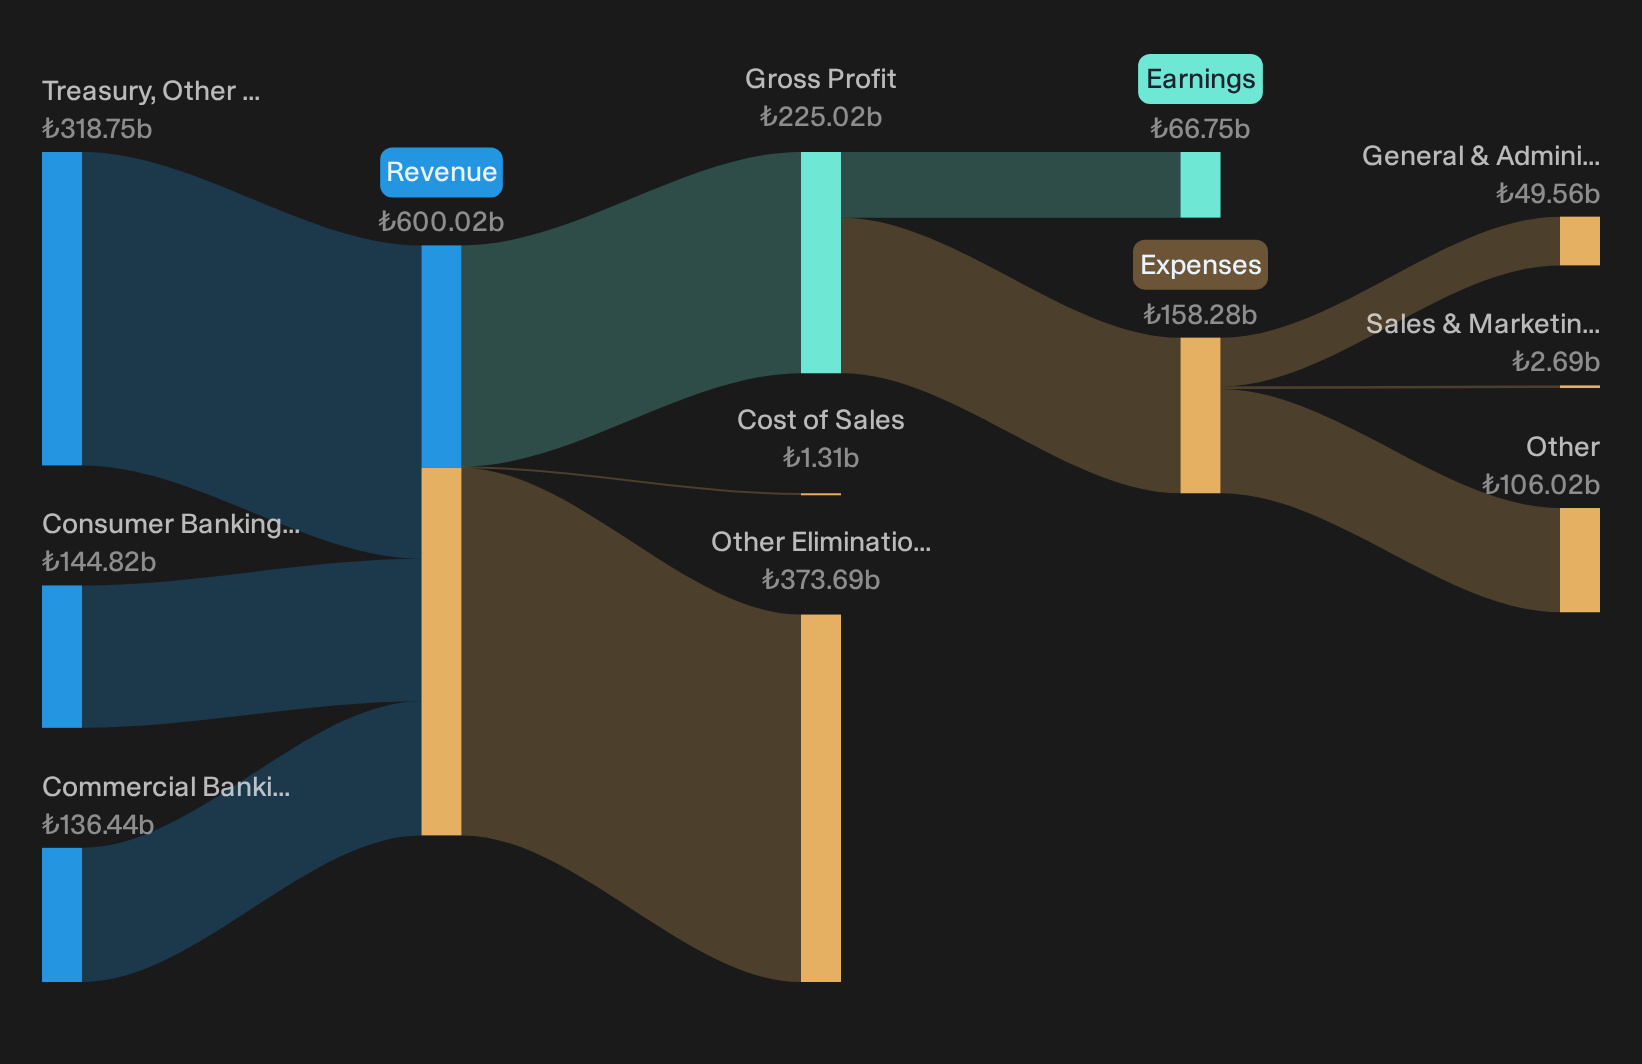
Operations: Akbank T.A.S generates about TRY 318.8b from treasury and other activities, TRY 144.8b from consumer banking and TRY 136.4b from commercial banking.
Market Cap: TRY 372.1b
Akbank T.A.S fits this global banks and fixed-income theme as a broad lender and treasury operator that leans into higher rates through spreads, deposits and balance sheet management rather than narrowly relying on one product or geography.
"Structural advances in digitalization and non-interest income are cited by management as factors that could support higher margins and growth in recurring revenue streams."
The key issue for investors to watch is how changes in funding costs and credit quality affect the durability of those margins.
Those margin swings are exactly what the full narrative for Akbank T.A.S unpacks, highlighting where digital traction, fee mix and credit risk might be quietly decoupling.
Seeking Alternatives Before The Crowd?
Fresh themes are breaking out, momentum is shifting and many opportunities are still under the radar for now. Screen these ideas before they get fully caught by the crowd and consider acting while they remain less widely noticed.
- Spot reliable cash generators with resilient balance sheets before everyone else starts talking about them through the list of solid balance sheet and fundamentals (196 results).
- Explore the momentum in richer yields by scanning high income candidates using the 158 dividend fortresses while the most attractive entry points may still be available.
- Track where long term structural demand is quietly building and filter potential beneficiaries with the 37 power grid technology and infrastructure stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com