
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Guidance Reaffirmed Might Change The Case For Investing In Arcutis Biotherapeutics (ARQT)
- Arcutis Biotherapeutics used a recent Morgan Stanley healthcare conference to reaffirm its 2026 revenue guidance of US$525 million to US$540 million and confirmed that the Phase 2 vitiligo trial remains scheduled for a fourth quarter data readout.
- This combination of steady revenue guidance and an on track dermatology pipeline update gives investors a clearer view of how Arcutis Biotherapeutics is trying to balance commercial execution with R&D progress.
- This article examines how Arcutis Biotherapeutics' investment narrative is influenced by reaffirmed 2026 revenue guidance presented at the Morgan Stanley conference.
Scan how Arcutis Biotherapeutics' reaffirmed 2026 targets compare with other potential breakout stories by reviewing the hand picked 16 high quality undiscovered gems.
Arcutis Biotherapeutics Investment Narrative Recap
The big picture for Arcutis Biotherapeutics is simple. Investors need to believe that ZORYVE can keep gaining traction across multiple skin disorders while the firm funds a focused but relatively narrow pipeline. The reiterated 2026 revenue guidance indicates that management sees its commercial plan as intact. In the near term, execution on ZORYVE uptake and payer coverage appears to remain the key operational driver.
The short term risk remains concentration. Most of the business depends on one franchise in a category where payer decisions and competing non steroidal options can quickly change prescription habits. The Phase 2 vitiligo readout is important for broadening the story, but it does not change that core dependency today.
The reaffirmed 2026 revenue range ties directly to the most recent update. Management used the Morgan Stanley healthcare conference to repeat the US$525 million to US$540 million target, which indicates confidence in existing psoriasis and atopic dermatitis plans. That message matters for readers watching for cracks in the launch or signs of changes in prescription momentum.
Vitiligo also sits in the foreground now. Arcutis Biotherapeutics confirmed the Phase 2 vitiligo trial remains on schedule for a fourth quarter data readout. A clean dataset would support the idea that ZORYVE can move beyond current labels and start to offset single product risk over time. A weak outcome would raise additional questions about the depth of the pipeline.
Arcutis Biotherapeutics is modeled to reach US$889.8 million in revenue and US$342.4 million in earnings by 2029, based on analyst assumptions of 24.2% yearly revenue growth and an earnings increase of about US$313.9 million from US$28.5 million today.
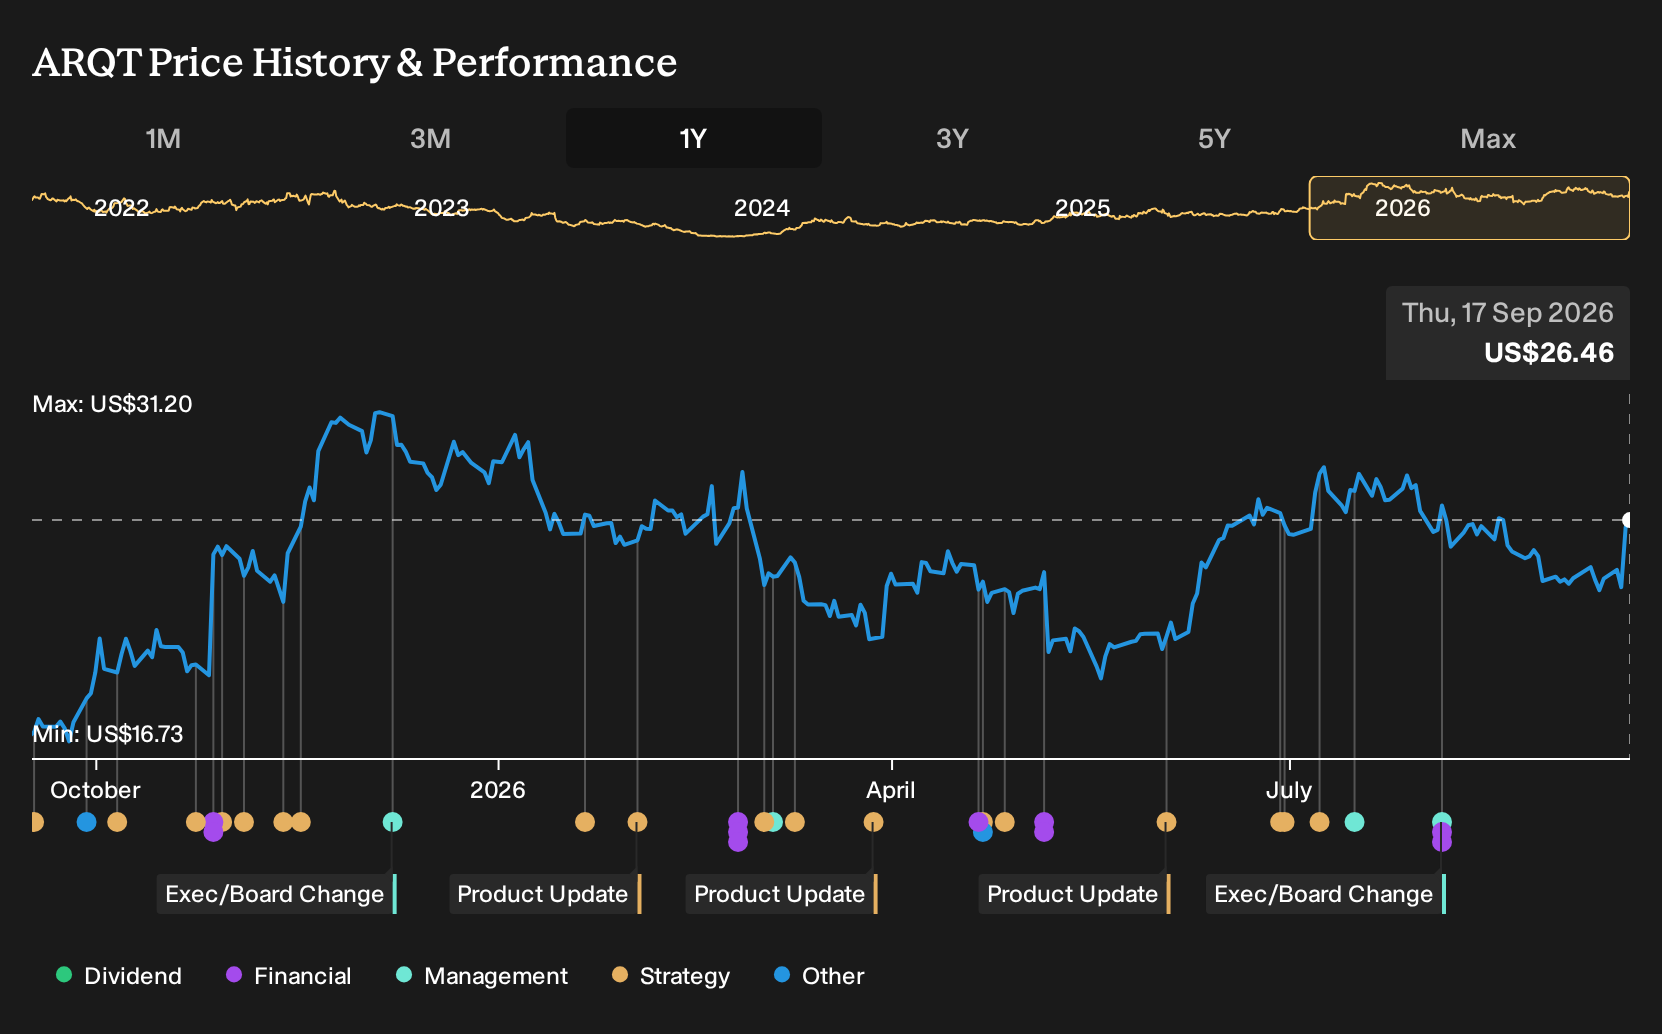
Uncover how Arcutis Biotherapeutics' fair value indicates a 39% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You are getting three fair value opinions from the Simply Wall St Community, with estimates ranging from about US$36.88 to US$85.69 per share, so sentiment runs wide around Arcutis Biotherapeutics. When you set that against heavy reliance on ZORYVE and shifting payer behavior, the spread makes sense. Explore the full range of views before deciding how this story fits your portfolio.
Explore 2 other Arcutis Biotherapeutics fair value estimates, including one that suggests as much as 224% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Arcutis Biotherapeutics research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Arcutis Biotherapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arcutis Biotherapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arcutis Biotherapeutics?
If the Arcutis Biotherapeutics story has you thinking about what else might fit your watchlist, it can help to scan a wider mix of opportunities with clear filters rather than scrolling through tickers at random.
- For investors who want quality and value in the same place, review a focused list of businesses flagged as attractively priced through the 29 high quality undervalued stocks.
- If capital preservation is high on your agenda, narrow your search to companies that score well on financial resilience using the 30 resilient stocks with low risk scores.
- When you care most about balance sheet strength and underlying fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) to see which businesses meet a stricter quality bar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com