
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Raised 2026 Outlook Could Be A Game Changer For Levi Strauss (LEVI)
- Levi Strauss reported strong recent momentum in lifestyle categories such as tops, dresses, shorts, and premium women's apparel, supported by direct-to-consumer channels. Management raised fiscal 2026 revenue and earnings guidance to reflect this broader product mix.
- The push beyond core denim into higher value lifestyle pieces suggests Levi Strauss is leaning on direct-to-consumer sales to support margins and reduce reliance on wholesale partners.
- We will look at how Levi Strauss's investment narrative evolves as lifestyle category strength shapes its fiscal 2026 outlook.
Scan beyond Levi Strauss and see how other apparel stocks with direct to consumer momentum and lifestyle expansion stack up in our hand picked 29 high quality undervalued stocks list.
Levi Strauss Investment Narrative Recap
For a shareholder, the core belief is that Levi Strauss can keep shifting from a pure denim label into a broader lifestyle brand while using its direct to consumer muscle to support profitability. The recent guidance raise tied to tops, dresses and premium womenswear speaks directly to that thesis. The key near term swing factor is whether these categories can carry enough weight to matter at the group level.
The biggest risk right now is execution drag. Lifestyle categories, DTC investments and exits from smaller brands all ask a lot of the cost base at the same time that tariffs, Asia softness and denim fashion risk sit in the background. The latest update helps the story but does not remove those pressures.
The most relevant recent update is Levi Strauss lifting its fiscal 2026 revenue and earnings guidance off the back of lifestyle strength and direct to consumer contribution. Higher expectations raise the bar. Investors now need the womens and tops push to keep pulling its weight while the retail channel mix holds margins.
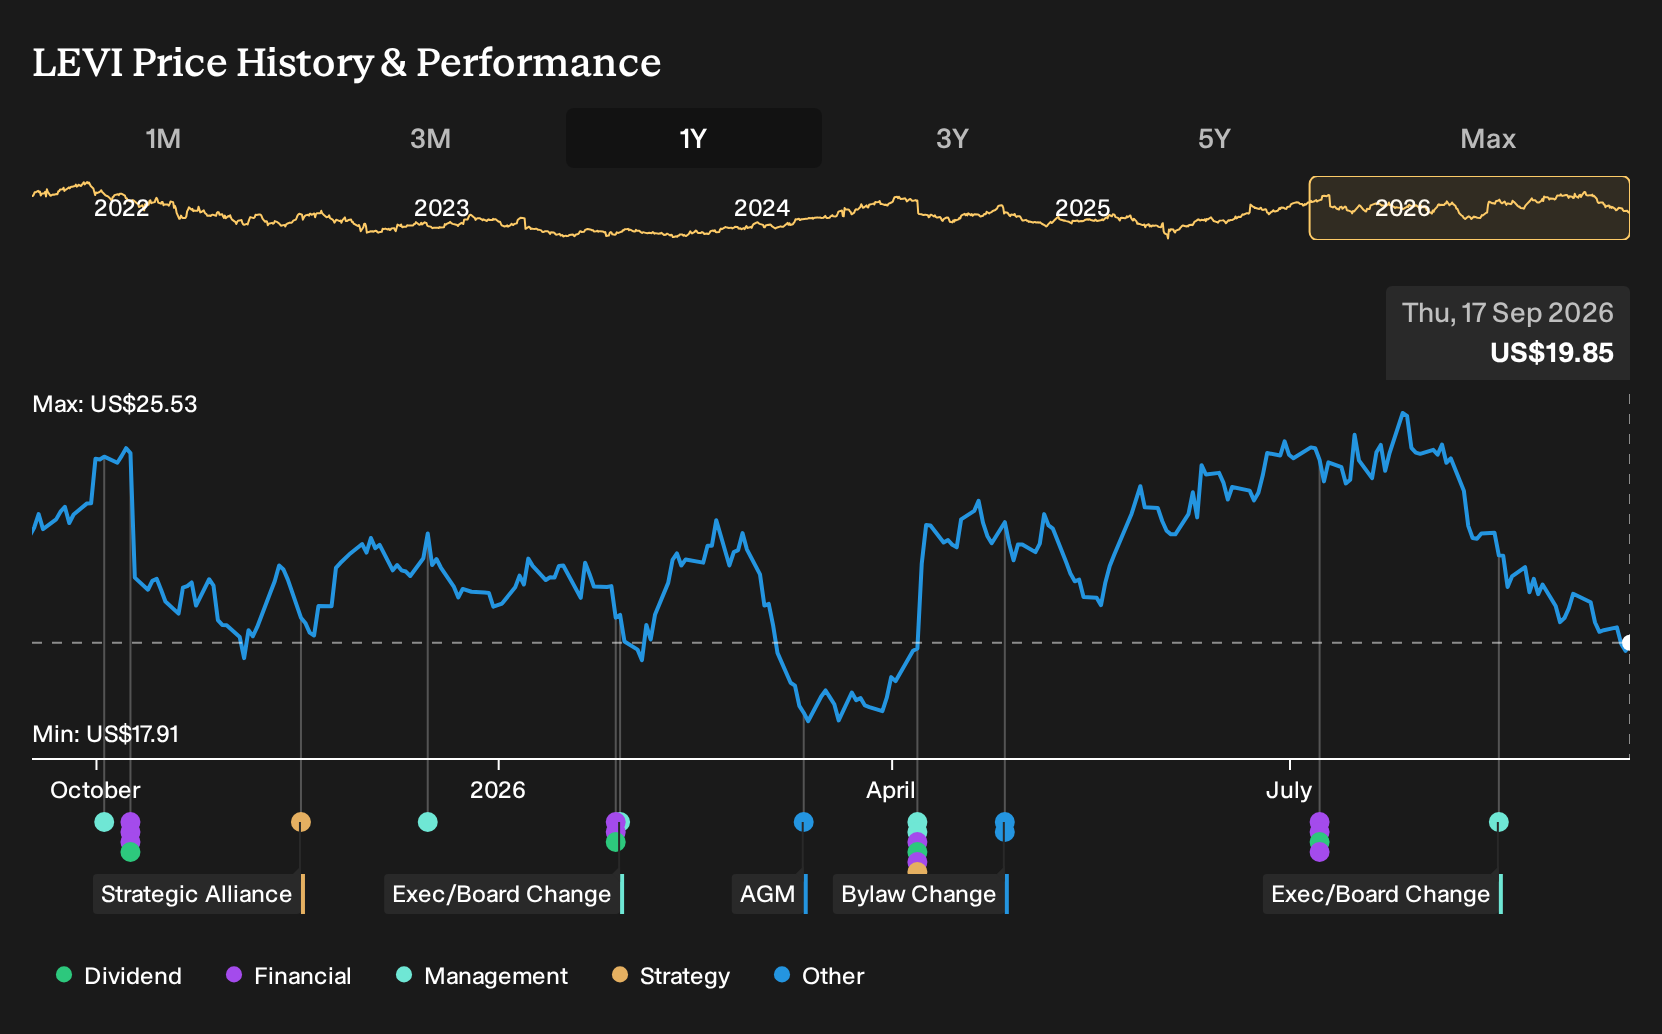
That guidance change also lands against a valuation backdrop where the stock trades on a P/E of 13.8x, below both the US market and the US Luxury group, and has pulled back over the past month and year. If the expanded product mix and DTC focus keep supporting earnings growth and high return on equity, the reset expectations could become an important proof point for the Levi Strauss thesis.
Levi Strauss Forecasts and What Needs To Go Right
Levi Strauss' narrative projects US$7.7b revenue and US$839.5m earnings by 2029. This implies 5.1% yearly revenue growth and an earnings increase of about US$285m from current earnings of US$554.1m.
Uncover why Levi Strauss' fair value indicates a 42% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One optimistic twist in the alternate Levi Strauss narrative is how bullish analysts frame direct to consumer as the real earnings engine. Before this guidance raise, the most upbeat forecasts were already pencilling in US$8.2b of revenue and US$927.0m of earnings by 2029. That is far above consensus. It shows how wide views can be and why you might want to compare several narratives as this new lifestyle update beds in.
Explore 3 other Levi Strauss fair value estimates, including one that suggests up to 42% potential upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Levi Strauss research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Levi Strauss. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Levi Strauss' overall financial health at a glance.
Looking For More Investment Ideas Beyond Levi Strauss?
If Levi Strauss has sharpened your interest in brands using direct relationships with shoppers and disciplined balance sheets, it can help to set up a wider watchlist of potential opportunities.
- If you want potential value combined with quality fundamentals, scan through our hand picked 29 high quality undervalued stocks that may fit a similar thesis to Levi Strauss in different corners of the market.
- For investors who care most about resilience and sleep at night risk levels, narrow your list using our 30 resilient stocks with low risk scores and see which companies score well on stability.
- If financial strength is your priority before anything else, start building a wider bench using our list of solid balance sheet and fundamentals (23 results) so you can compare Levi Strauss with other robust operators.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com